Bank of Japan’s 31-Year-High Rate: Why It Matters for India
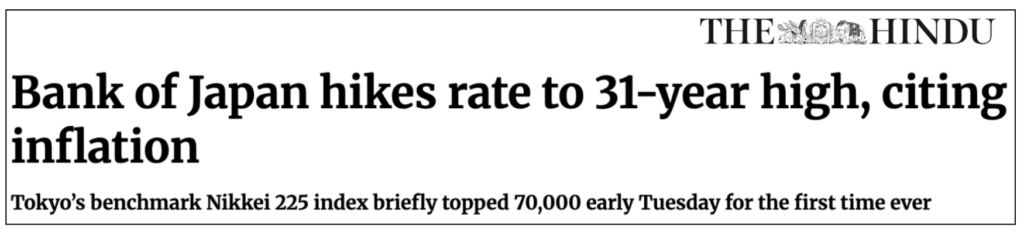
Why in News?
The Bank of Japan (BoJ) has raised its policy interest rate to a 31-year high, citing persistent inflation. The move marks the decisive end of Japan’s decades-long experiment with ultra-loose, near-zero interest-rate policy — the longest such episode by any major central bank.
For years, Japan kept borrowing costs at or below zero to fight deflation. With prices and wages now rising durably, the BoJ has shifted to monetary tightening. Because Japanese money is woven through global markets, a higher yield in Japan reverberates far beyond Tokyo — including through the yen carry trade and the flow of foreign capital into emerging markets like India.
- The Bank of Japan lifted its policy rate to its highest level in about 31 years, the clearest break yet from zero-rate policy.
- The stated trigger is sustained inflation running near or above the BoJ’s 2% target, backed by stronger wage growth.
- The decision ends an era of quantitative and qualitative easing (QQE), negative interest rates and yield-curve control that defined Japanese policy.
- A higher Japanese yield narrows the gap with other economies and can pull global capital back toward Japan, unwinding the yen carry trade.
The development matters in the context of:
- Why it matters for the rupee: shifts in global rate differentials move capital flows, the rupee and India’s bond yields.
- Why it matters for markets: an unwinding carry trade can spark sudden, synchronised sell-offs across emerging-market equities and currencies.
- Why it matters strategically: Japan is a major source of investment and concessional finance for India, so its monetary stance touches trade and capital ties.
UPSC Relevance
Prelims Relevance
- Bank of Japan as Japan’s central bank; meaning of the policy/repo-equivalent rate
- Concept of the yen carry trade and how its unwinding works
- Quantitative easing, negative interest rates and yield-curve control
- Difference between FPI (foreign portfolio investment) and FDI
- Meaning of an interest-rate differential and its link to currency value
- Imported inflation and exchange-rate pass-through to domestic prices
- Role of the RBI in managing the rupee and forex reserves
- Bond yield basics and the inverse yield-price relationship
Mains Relevance
GS Paper 3
- How a major central bank’s monetary shift transmits into India’s capital flows, currency and bond markets
- Tools available to the RBI to cushion external monetary shocks and currency volatility
GS Paper 3
- The carry trade as a channel of global financial contagion for emerging markets
GS Paper 2
- India-Japan economic and strategic ties amid shifting global monetary conditions
Essay
- When distant decisions decide domestic destinies in a connected economy
- The price of cheap money and the discipline of its withdrawal
Background and Context
What the Bank of Japan did — and why
The BoJ has reversed the most unconventional monetary stance among major economies.
- The Bank of Japan is Japan’s central bank; like the RBI, it sets the policy interest rate and steers money supply through monetary policy.
- For decades, Japan battled deflation — persistently falling prices — by holding rates near or below zero to encourage spending and borrowing.
- It deployed quantitative easing (QE) (large-scale bond buying), negative interest rates, and yield-curve control (YCC) (capping long-term bond yields).
- With inflation now sustained near the 2% target and wages rising, the BoJ has raised its rate to a 31-year high, formally exiting ultra-loose policy.
- The shift signals confidence that Japan has finally escaped its long deflationary trap.
The yen carry trade — explained simply
Cheap Japanese money funded bets across the world; that logic is now reversing.
- A carry trade means borrowing in a currency where interest rates are very low and investing the money where returns are higher.
- Because Japan’s rates were near zero for years, global investors borrowed cheap yen and put it into higher-yielding assets abroad — US bonds, emerging-market equities, even cryptocurrencies.
- The profit is the gap (the ‘carry’) between near-zero Japanese borrowing costs and the higher yield earned elsewhere.
- When Japan raises rates, borrowing in yen becomes costlier, and the yen tends to strengthen, shrinking that profit.
- Investors then unwind the trade — selling foreign assets and repaying yen loans — which can trigger sharp, synchronised sell-offs in global markets.
How it reaches India — capital flows and the rupee
The transmission runs through interest-rate differentials and portfolio money.
- A higher Japanese yield narrows the interest-rate differential between Japan and emerging markets, making Indian assets relatively less attractive at the margin.
- Some foreign portfolio investors (FPIs) may pull money out of Indian equities and bonds to repay yen loans or chase safer yields, pressuring share prices.
- Outflows and a stronger yen can weaken the rupee against the dollar, since FPIs sell rupees to exit.
- A weaker rupee raises the cost of imports — crude oil, electronics, edible oils — feeding imported inflation. See our note on inflation.
- Indian bond yields can rise if foreign demand for government debt softens, lifting borrowing costs.
The US Fed and the global rate map
Japan’s move is one piece of a wider tug-of-war over global capital.
- Global capital chases the best risk-adjusted return, so it is the relative stance of central banks that matters, not Japan’s alone.
- If the US Federal Reserve holds rates high while Japan tightens too, emerging markets face a double squeeze on capital.
- A narrower Japan-US yield gap can strengthen the yen and unsettle the dollar-funded trades that dominate global finance.
- Episodes of carry-trade unwinding — as seen in past spikes of volatility — tend to hit emerging-market currencies and equities first.
- India’s relatively strong growth and large forex reserves offer a buffer, but it is not insulated from global repricing.
India-Japan economic ties
Japan is among India’s most important long-term economic partners.
- Japan is a major source of foreign direct investment (FDI) into India — autos, electronics, manufacturing and infrastructure. For the wider picture, see India-Japan relations.
- It provides large Official Development Assistance (ODA) and concessional loans, including for flagship projects like the Mumbai-Ahmedabad high-speed rail.
- The two are partners in the Quad and share a deep strategic and supply-chain agenda.
- Japanese monetary normalisation can raise the cost of yen-denominated financing for some Indian projects over time.
- A stronger, more confident Japanese economy can also mean steadier long-term investment in India.
RBI’s room to respond
India’s central bank has tools to smooth, not eliminate, external shocks.
- The RBI can intervene in the forex market using its foreign-exchange reserves to curb sharp rupee swings.
- It can adjust its own repo rate to keep India’s yields competitive without choking growth.
- Macroprudential measures and a flexible-but-managed exchange rate help absorb volatility.
- A credible inflation-targeting framework anchors expectations even when external pressure rises.
- Deep domestic savings and a large home market reduce India’s dependence on any single source of foreign capital.
Way Forward
Build external resilience
- Maintain healthy forex reserves and a flexible exchange rate to absorb sudden capital swings.
- Deepen domestic bond and equity markets so India relies less on volatile foreign portfolio flows.
Diversify capital sources
- Court stable, long-horizon FDI over hot portfolio money to reduce contagion risk.
- Broaden funding partners and currencies so no single global rate cycle dominates India’s costs.
Coordinate policy and communication
- Keep monetary and fiscal policy aligned and clearly signalled to steady investor expectations.
- Track global central-bank moves closely so the RBI can act early, not reactively.
The episode is a reminder that in an interconnected financial system, a rate decision in Tokyo can move the rupee in Mumbai. India’s best defence is structural — strong fundamentals, ample reserves, deep domestic markets and credible, well-communicated policy.
Conclusion
The Bank of Japan‘s shift to a 31-year-high policy rate closes a remarkable chapter of near-zero money that shaped global finance for decades. As cheap yen stops fuelling the worldwide carry trade, capital is repricing across markets — and emerging economies like India sit squarely in the path of that adjustment.
For India, the spillovers run through FPI flows, the rupee, bond yields and imported inflation. None of these is catastrophic on its own, but together they test the cushioning power of the RBI and the resilience of India’s macro fundamentals. The lesson is durable: in a connected world, monetary policy is never purely domestic.
UPSC Practice Questions
Prelims MCQ 1
With reference to the yen carry trade, consider the following statements:
- It involves borrowing in a low-interest-rate currency to invest in higher-yielding assets elsewhere.
- A rate hike by the Bank of Japan tends to encourage an unwinding of the trade.
- An unwinding of the carry trade typically strengthens emerging-market currencies.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 1 and 2 are correct: the carry trade borrows cheap yen to invest for higher yields, and a BoJ rate hike makes yen borrowing costlier, prompting unwinding. Statement 3 is wrong — unwinding usually pulls capital out of emerging markets, weakening their currencies, not strengthening them.
Prelims MCQ 2
An increase in the Bank of Japan’s policy rate, other things being equal, is most likely to:
(a) Increase foreign portfolio inflows into Indian equities
(b) Strengthen the Indian rupee against the US dollar
(c) Encourage some investors to repay yen loans and reduce risk exposure
(d) Lower Indian government bond yields
Answer: (c) Encourage some investors to repay yen loans and reduce risk exposure
Explanation:
Higher Japanese rates make yen borrowing costlier, so carry-trade investors repay yen loans and trim risky positions. This tends to pull capital out of emerging markets, can weaken the rupee, and may raise (not lower) Indian bond yields.
UPSC Mains Questions
- Explain the concept of the carry trade and discuss how the unwinding of the yen carry trade following monetary tightening by the Bank of Japan can transmit financial volatility to emerging economies like India. (250 words)
- Interest-rate decisions by major central banks shape capital flows to and from India. Examine the channels through which such decisions affect the rupee, foreign portfolio investment and domestic inflation, and assess the policy tools available to the RBI. (250 words)
- Discuss the significance of India-Japan economic ties and analyse how Japan’s exit from ultra-loose monetary policy could affect investment and financing flows to India. (150 words)
Sources: The Hindu and Reserve Bank of India.
Frequently Asked Questions
What did the Bank of Japan do?
The Bank of Japan, Japan’s central bank, raised its policy interest rate to a roughly 31-year high, citing sustained inflation. The move ends decades of ultra-loose, near-zero-rate policy that Japan used to fight deflation. It signals confidence that prices and wages are now rising durably, allowing a shift toward normal monetary tightening.
What is the yen carry trade?
The yen carry trade is when investors borrow Japanese yen at very low interest rates and invest the money in higher-yielding assets abroad, such as foreign bonds or emerging-market shares. The profit is the gap between cheap yen borrowing costs and the higher returns earned elsewhere. It thrives only while Japanese rates stay extremely low.
Why does it matter for India?
When Japan raises rates, borrowing yen becomes costlier and the yen often strengthens, so investors unwind the carry trade by selling foreign assets. Some foreign portfolio money may exit Indian equities and bonds, pressuring share prices, weakening the rupee, lifting bond yields and adding to imported inflation through costlier imports.
How can a stronger yen weaken the rupee?
As carry-trade investors repay yen loans, they sell assets in markets like India and buy back yen. Selling rupees to exit pushes the rupee down against the dollar, while demand for the yen lifts it. A weaker rupee then raises the cost of imports such as crude oil, feeding domestic inflation.
What can the RBI do about it?
The RBI can sell dollars from its large foreign-exchange reserves to steady the rupee, adjust its own repo rate to keep Indian yields competitive, and use macroprudential measures to limit volatility. A credible inflation-targeting framework and deep domestic savings give India a meaningful cushion, though not full insulation, against external shocks.
Why was Japan’s rate near zero for so long?
Japan suffered decades of deflation — persistently falling prices — after its 1990s asset-bubble collapse. To revive spending and borrowing, the Bank of Japan cut rates to near or below zero and used tools like quantitative easing and yield-curve control. Only when inflation and wages turned durably positive did it begin raising rates again.