CAG on Ladki Bahin: Excess spend and budgetary lapses in Maharashtra’s flagship scheme
Why in News?
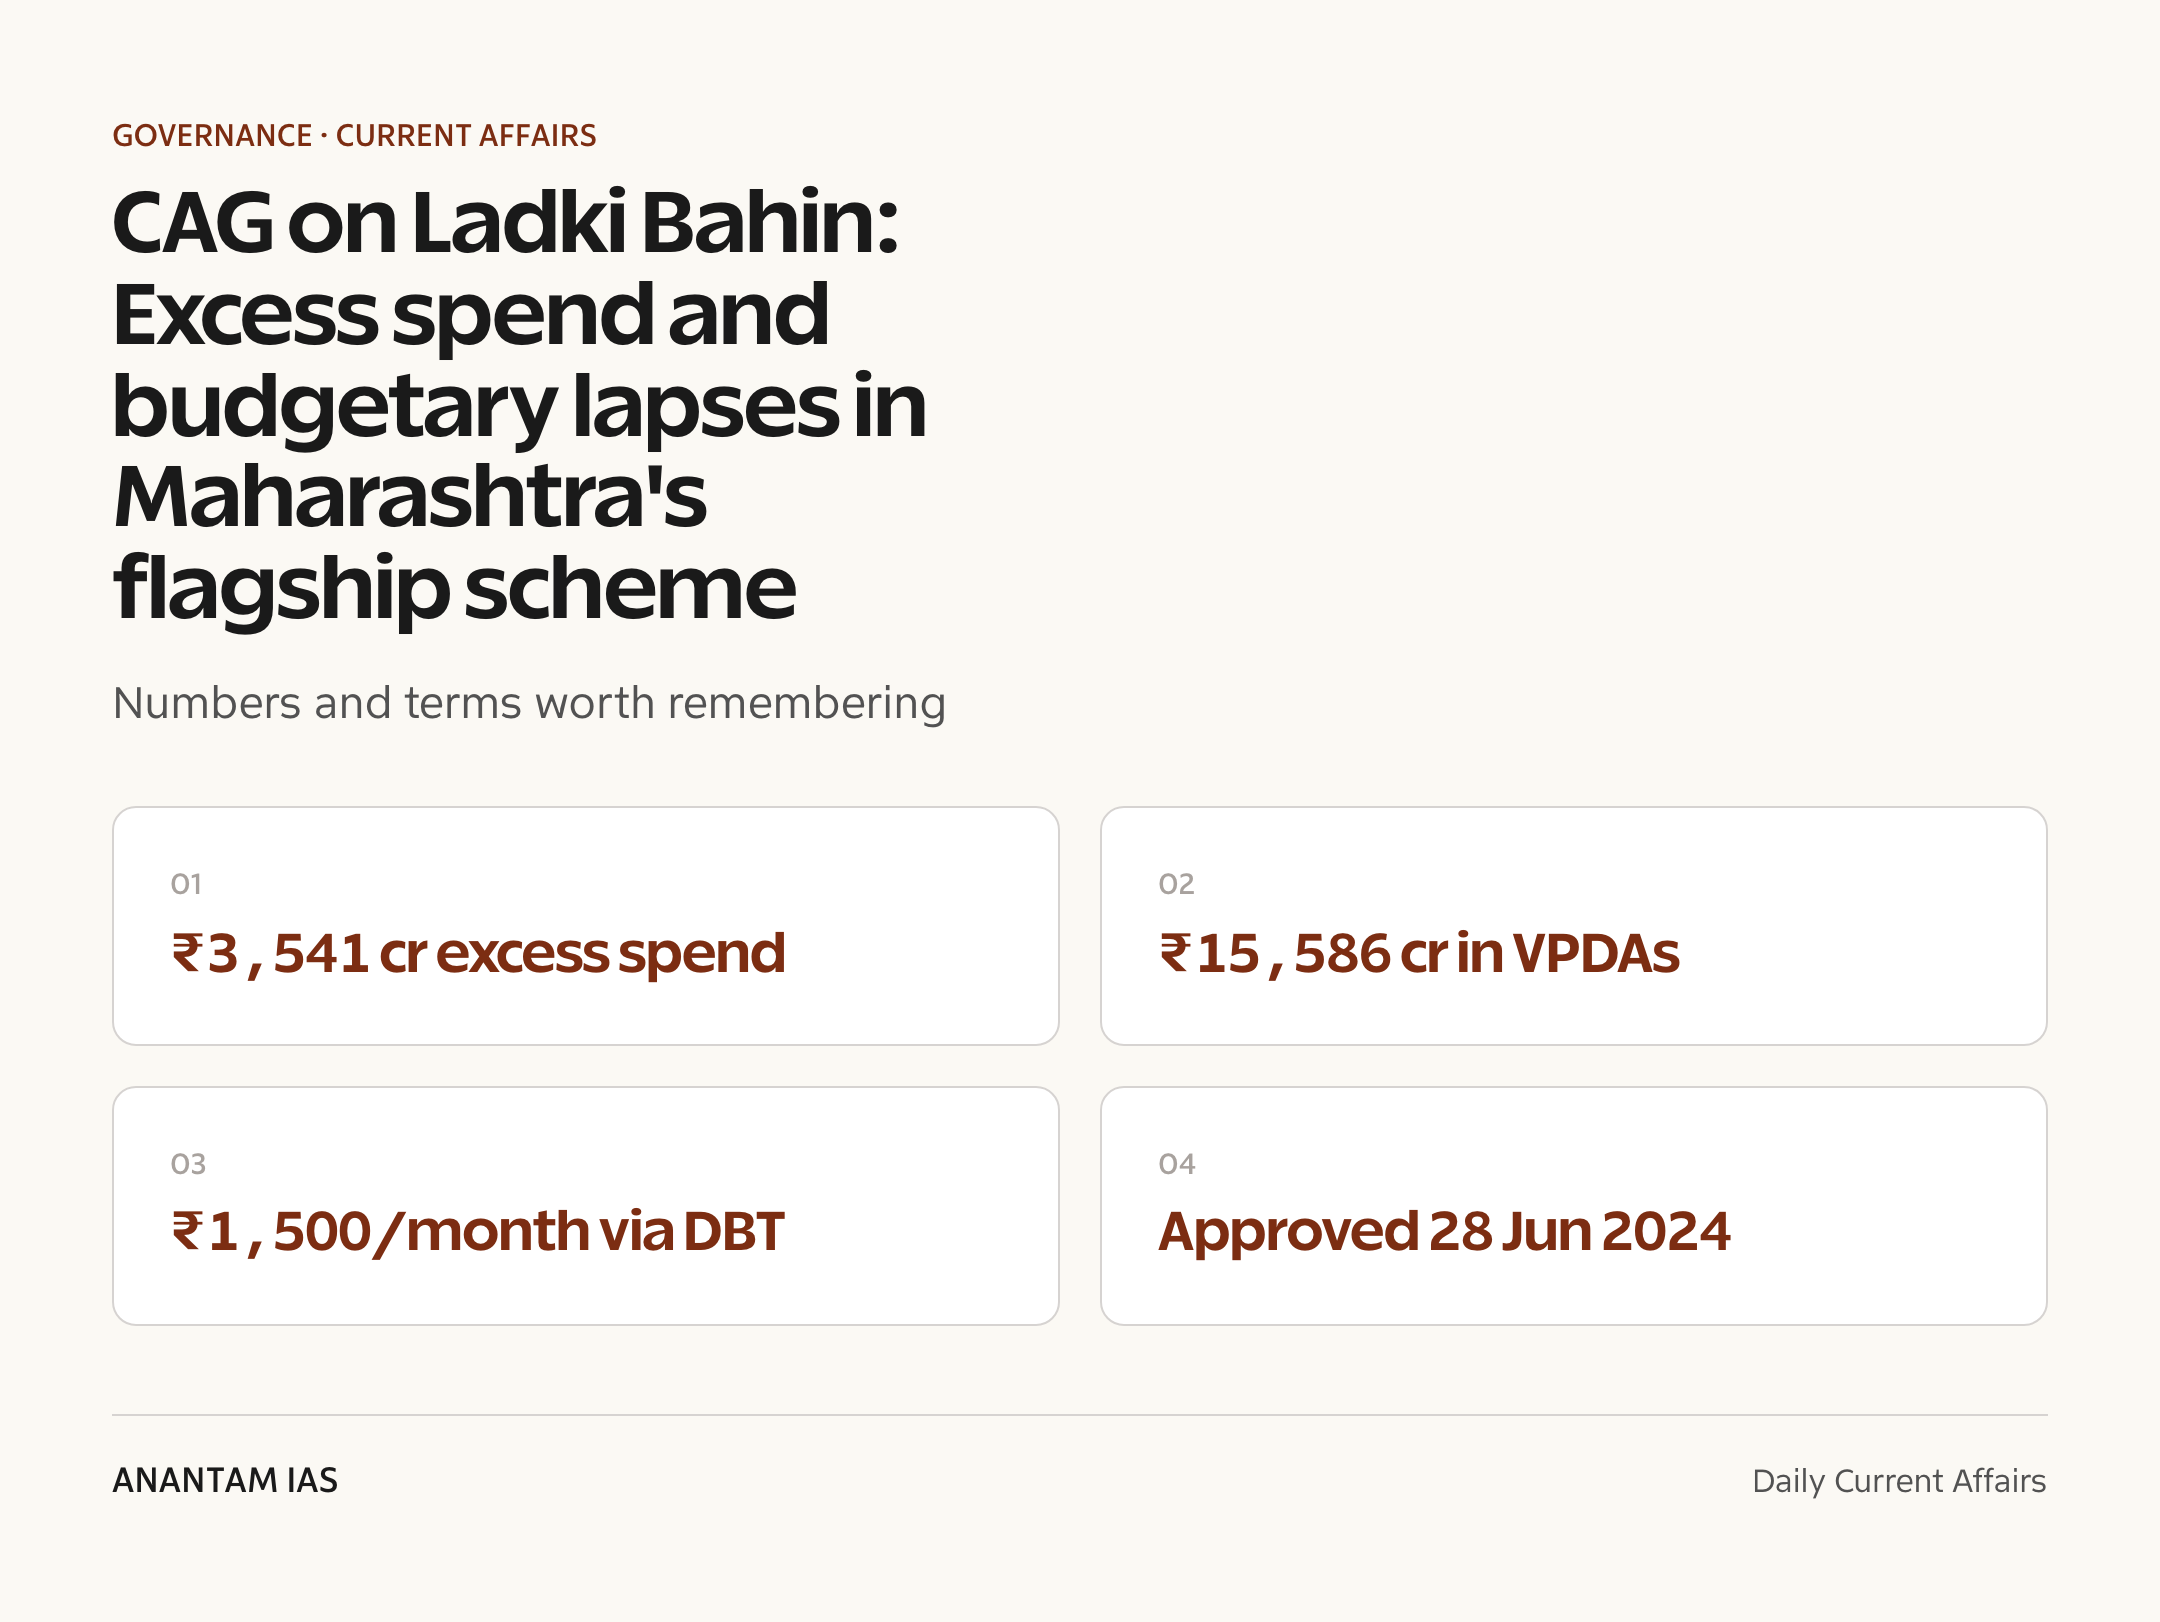
The Comptroller and Auditor General (CAG) has flagged excess expenditure of ₹3,541.16 crore, large-scale parking of funds in deposit accounts and weak financial management in Maharashtra’s flagship Mukhyamantri Majhi Ladki Bahin Yojana. The findings appear in the CAG’s State Finances Audit Report 2024-25, tabled in the Maharashtra legislature on 10 July 2026, The Hindu reported citing PTI.
The state’s Women and Child Development Department spent ₹33,237.24 crore on the scheme against an authorised budget of ₹29,693.09 crore — with no specific justification for the overshoot. Another ₹15,586 crore drawn between January and March 2025 was parked in Virtual Personal Deposit Accounts without immediate expenditure needs.
- ₹3,541.16 crore spent in excess of the authorised budget — expenditure the legislature never sanctioned in advance.
- The grant of ₹29,693.09 crore itself leaned on ₹26,200 crore of supplementary provisions and ₹3,490.75 crore re-appropriated from the Lek Ladki Yojana.
- ₹15,586 crore drawn between January and March 2025 went to Virtual Personal Deposit Accounts (VPDAs) — “contrary to principles of budgetary discipline and financial propriety”, the CAG said.
- The report noted “significant deficiencies in budget estimation, expenditure control, and financial management“.
- Women’s welfare spending jumped from ₹261.78 crore to more than ₹33,500 crore in a year — a shift towards transfers over capital asset formation, the CAG observed.
The development matters in the context of:
- A textbook illustration of legislative control over public finance — appropriation, supplementary demands, excess grants and audit — on a live welfare scheme.
- It feeds the freebies versus welfare debate: women-centric cash transfers now run in a dozen states, and their fiscal design faces growing scrutiny.
- For GS2, it connects DBT-based scheme design with accountability institutions — the CAG, the state PAC and the legislature.
UPSC Relevance
Prelims Relevance
- CAG of India — Articles 148 to 151; appointed by the President; removal like a Supreme Court judge; term 6 years or age 65.
- DPC Act, 1971 — the CAG’s (Duties, Powers and Conditions of Service) Act, enacted under Article 149.
- Article 151(2) — CAG reports on state accounts go to the Governor, then to the state legislature.
- State Finances Audit Report — the CAG’s annual report on a state’s finances and budgetary management.
- Articles 204-205 — withdrawals from a state’s Consolidated Fund need an Appropriation Act; overshoots need an excess grant.
- PD / Virtual Personal Deposit Accounts — treasury accounts where drawn funds are parked; expenditure is booked without money being spent.
- Mukhyamantri Majhi Ladki Bahin Yojana — approved 28 June 2024; ₹1,500 per month via DBT to Maharashtra women aged 21 to 65.
- Direct Benefit Transfer (DBT) — launched 2013; rides on the JAM trinity.
- Public Accounts Committee — examines CAG reports and recommends regularisation of excess expenditure.
Mains Relevance
GS Paper 2
- Government policies and interventions: design flaws in large cash-transfer schemes — beneficiary estimation, budgeting, expenditure control.
- Transparency and accountability: the CAG and the PAC as checks on executive spending.
- Welfare schemes for vulnerable sections: women-centric transfers — empowerment gains versus fiscal-governance risks.
- State legislatures: how excess expenditure and fund parking erode legislative control over the purse.
GS Paper 3
- Government budgeting: appropriation, supplementary demands, re-appropriation and excess grants in practice.
- State finances: revenue-heavy transfers crowding out capital expenditure and asset creation.
Essay
- Welfare that outruns the budget: can populism and prudence coexist in Indian states?
- Audit is the conscience of the exchequer — institutions matter more than intentions.
- Cash transfers empower women, but who keeps the treasury honest?
Background and Context
What the CAG Audit Found
The State Finances Audit Report 2024-25 reads like a case study in how a flagship scheme can outrun every budgetary guardrail in a single year.
- The Women and Child Development Department spent ₹33,237.24 crore against an authorised budget of ₹29,693.09 crore — an unexplained excess of ₹3,541.16 crore.
- The grant was itself improvised: ₹26,200 crore came through supplementary provisions and ₹3,490.75 crore was re-appropriated from the Lek Ladki Yojana, a girl-child scheme.
- ₹15,586 crore drawn between January and March 2025 — the fiscal year’s last quarter — was moved to Virtual Personal Deposit Accounts (VPDAs).
- The CAG said the funds “were drawn from the treasury without actual expenditure needs”, calling the parking a serious financial irregularity that undermined legislative control over public finances.
- The report recorded “significant deficiencies in budget estimation, expenditure control, and financial management“.
- Women’s welfare spending rose from ₹261.78 crore the previous year to over ₹33,500 crore — a shift towards welfare-oriented transfers over capital asset formation, the CAG noted.
Ladki Bahin Yojana: Design of the Scheme
Behind the audit numbers sits one of India’s largest state-level cash transfer programmes for women.
- The Mukhyamantri Majhi Ladki Bahin Yojana was approved on 28 June 2024, with women’s economic independence as its stated aim.
- Eligible women aged 21 to 65 years receive ₹1,500 per month through Direct Benefit Transfer.
- It’s implemented by the Women and Child Development Department — the same department the CAG faulted for weak budget estimation and expenditure control.
- It joined a national wave of women-centric transfers — Ladli Behna (Madhya Pradesh), Lakshmir Bhandar (West Bengal), Gruha Lakshmi (Karnataka), Kalaignar Magalir Urimai Thogai (Tamil Nadu), Maiya Samman (Jharkhand).
- DBT was meant to fix leakages in delivery; this audit shows the risk has migrated upstream — from who receives the money to how it is budgeted and drawn.
The CAG: Constitutional Anchor of Public Audit
The institution making these findings is a constitutional authority, not an arm of any government.
- Article 148: the CAG is appointed by the President; removal only in the manner of a Supreme Court judge, on proved misbehaviour or incapacity.
- Article 149: Parliament prescribes the CAG’s duties and powers — done through the DPC Act, 1971.
- Article 150: Union and state accounts are kept in a form prescribed by the President on the CAG’s advice.
- Article 151(2): audit reports on a state’s accounts go to the Governor, who has them laid before the state legislature — exactly the route this report took.
- The CAG conducts financial, compliance and performance audits; the annual State Finances Audit Report assesses a state’s budgetary management.
- Dr B.R. Ambedkar called the CAG possibly the most important officer of the Constitution — the guardian of the public purse.
Legislative Control: Where Excess Expenditure Breaks the Chain
The Constitution builds a strict chain of legislative authorisation over every rupee a state spends — and excess expenditure snaps it.
- Article 202: the state lays an annual financial statement before the legislature; Article 203 puts expenditure through votable demands for grants.
- Article 204: no money leaves the Consolidated Fund of the State except under an Appropriation Act — spending beyond it has no legal sanction when incurred.
- Article 205: overshoots must return as an excess grant, regularised by the legislature after the Public Accounts Committee examines the CAG’s findings.
- Supplementary demands are legal, but routinely funding a flagship scheme through supplementary provisions and re-appropriation signals the original budget was never realistic.
- Unexplained excess spending means the executive bypassed the legislature’s authority — the core of the no-spending-without-representation principle.
PD Accounts: How Parked Funds Defeat the Budget
The ₹15,586 crore moved into VPDAs is the report’s most instructive finding, because the money looked spent while it sat idle.
- A Personal Deposit (PD) account — here in virtual form as a VPDA — is a treasury device where a designated officer holds funds drawn from the Consolidated Fund.
- Once transferred, the amount is booked as expenditure even though no benefit has reached anyone — inflating reported spending.
- The classic motive is beating the lapse rule: unspent provisions lapse on 31 March, so departments draw and park funds in March to “save” them.
- The practice distorts fiscal indicators, weakens cash management — the state may borrow while cash idles — and escapes the legislature’s year-wise control.
- The CAG recommended withdrawals be strictly linked to actual and immediate expenditure needs, with realistic assessment of beneficiary coverage at budget formulation itself.
- The Union’s just-in-time release framework for centrally sponsored schemes tackles the same disease — money leaves the treasury only when payouts are due.
The Bigger Debate: Cash Transfers, Populism and State Finances
The audit lands in the middle of India’s running argument over welfare transfers and fiscal prudence.
- Women-centric transfers have real welfare logic — income support, financial inclusion and greater household bargaining power for women.
- The fiscal worry is compositional: the CAG itself noted the shift towards transfers over capital asset formation; revenue-heavy budgets leave less for capacity-building infrastructure.
- The RBI’s studies of state budgets have repeatedly cautioned states about the growing burden of subsidies and income transfers on revenue expenditure.
- In S. Subramaniam Balaji vs State of Tamil Nadu (2013), the Supreme Court held that pre-poll promises implemented through appropriations aren’t “corrupt practices” — pushing the freebies-versus-welfare question back to fiscal institutions and voters.
- That’s why audit matters: courts won’t police welfare populism, so budgetary discipline, CAG audit and PAC scrutiny are the accountability instruments that remain.
Way Forward
Budget honestly for DBT schemes
- Build scheme budgets on a realistic beneficiary database — registry-based estimation of coverage and monthly outgo, as the CAG recommends.
- Treat supplementary demands as exceptions for genuine shocks, not a routine second budget for flagship schemes.
Restore treasury discipline
- Prohibit parking of scheme funds in PD/VPDA accounts; adopt just-in-time release so money leaves the Consolidated Fund only against actual payout files.
- Publish a live DBT dashboard — funds drawn versus funds paid — so parked balances are visible in-year, not a year later in audit.
Close the accountability loop
- The state Public Accounts Committee should examine the report promptly; the legislature should regularise the excess under Article 205 with recorded justification.
- Pair financial audit with a performance audit of outcomes — did ₹33,000-plus crore measurably improve women’s economic independence?
Conclusion
The CAG hasn’t questioned whether Maharashtra should pay women ₹1,500 a month — that’s a political choice for elected governments. What the audit questions is the plumbing: a flagship scheme financed by improvised supplementary grants, overshooting its budget by ₹3,541 crore without explanation, and parking ₹15,586 crore where money looks spent but isn’t.
For aspirants, this one story stitches together the CAG’s constitutional mandate, the appropriation-to-excess-grant chain, PD accounts and the welfare-populism debate. The durable lesson: in a DBT era, welfare credibility depends as much on budgetary discipline as on delivery to the last beneficiary.
UPSC Practice Questions
Prelims MCQ 1
With reference to the Comptroller and Auditor General (CAG) of India, consider the following statements:
- The CAG is appointed by the President and can be removed from office in the same manner as a judge of the Supreme Court.
- Audit reports of the CAG relating to the accounts of a state are submitted to the Governor, who causes them to be laid before the state legislature.
- The duties and powers of the CAG are exhaustively laid down in the Constitution and cannot be prescribed by Parliament through legislation.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 1 and 2 are correct (Articles 148 and 151(2)). Statement 3 is wrong: Article 149 expressly empowers Parliament to prescribe the CAG’s duties and powers, which it did through the CAG’s (Duties, Powers and Conditions of Service) Act, 1971.
Prelims MCQ 2
The CAG’s State Finances Audit Report 2024-25 criticised the transfer of Ladki Bahin scheme funds to Virtual Personal Deposit Accounts (VPDAs) primarily because such parking of funds:
(a) earns market interest for the implementing department (b) shows money as spent in government accounts without actual expenditure, undermining legislative control (c) delays Direct Benefit Transfer payments to beneficiaries by a full quarter (d) converts revenue expenditure into capital expenditure in the state’s books
Answer: (b) shows money as spent in government accounts without actual expenditure, undermining legislative control
Explanation:
Funds moved to PD/VPDA accounts are booked as expenditure though unspent — typically to evade the 31 March lapse of budget provisions. The CAG called this contrary to budgetary discipline and financial propriety, since it erodes the legislature’s control over public finances.
UPSC Mains Questions
- The CAG’s audit of Maharashtra’s Ladki Bahin Yojana suggests the weakest link in India’s welfare architecture is no longer last-mile delivery but budgetary discipline. Discuss with reference to the constitutional framework for legislative control over state expenditure.
- Direct cash-transfer schemes for women have spread rapidly across Indian states. Examine their contribution to social justice alongside the fiscal-governance risks they carry, and suggest safeguards that reconcile welfare commitments with budgetary integrity.
- “Audit is the last mile of financial accountability.” In the light of recent CAG findings on state welfare schemes, evaluate the effectiveness of the CAG-PAC mechanism, and suggest reforms.
Sources: The Hindu (PTI) and Comptroller and Auditor General of India.
Frequently Asked Questions
What did the CAG flag in the Ladki Bahin scheme?
The CAG State Finances Audit Report 2024-25 flagged excess expenditure of ₹3,541.16 crore over the authorised budget, parking of ₹15,586 crore in Virtual Personal Deposit Accounts, and significant deficiencies in budget estimation, expenditure control and financial management by Maharashtra’s Women and Child Development Department.
What is the Mukhyamantri Majhi Ladki Bahin Yojana?
It’s Maharashtra’s flagship cash-transfer scheme, approved on 28 June 2024, paying eligible women aged 21 to 65 years ₹1,500 per month through Direct Benefit Transfer. Its stated aim is women’s economic independence, and it’s among India’s largest state-level income transfer programmes for women.
What is a Virtual Personal Deposit Account (VPDA)?
A PD or VPDA is a treasury account where funds drawn from the Consolidated Fund sit with a designated officer. The amount is booked as expenditure even though it hasn’t been spent, so departments use it to stop unspent budgets lapsing on 31 March — a practice the CAG treats as a financial irregularity.
Why must excess expenditure be regularised?
Under Article 204, money can leave the Consolidated Fund of a State only under an Appropriation Act. Spending beyond that authorisation lacks legislative sanction, so Article 205 requires the government to seek an excess grant, which the legislature approves after the Public Accounts Committee examines the CAG’s findings.
Which constitutional articles govern the CAG?
Articles 148 to 151. Article 148 covers appointment by the President and removal like a Supreme Court judge; Article 149 lets Parliament prescribe duties through the DPC Act, 1971; Article 150 covers the form of accounts; Article 151 routes audit reports to the President or Governor for the legislature.
How is this news useful for UPSC preparation?
It links GS2 governance with GS3 budgeting in one live example: CAG audit, legislative financial control, excess grants, PD accounts and the freebies-versus-welfare debate. Prelims can test the CAG’s articles and DBT facts; Mains can ask about accountability institutions or the fiscal design of cash-transfer schemes.