Environmental Accounts: Connecting Natural Assets and Economic Activity
Why in News?
On 7 October 2026, the Ministry of Statistics and Programme Implementation released its environmental accounts strategy for 2026–2030 to expand coverage and address data gaps.
- The roadmap extends the earlier strategy and identifies priorities for developing environmental-economic accounts.
- Its scope includes forests, minerals, soil, land and water, alongside carbon stocks, biodiversity and environment-related activities.
- MoSPI follows the System of Environmental-Economic Accounting, endorsed by the United Nations Statistical Commission.
- The document offers guidance for States and Union Territories; publication does not mean every proposed account is already complete.
- Economic production can rise while a natural-resource stock declines; reading both together changes the sustainability assessment.
- Comparable environmental and economic data help identify which activities depend on particular resources and where monitoring is missing.
UPSC Relevance
Prelims Relevance
- SEEA: System of Environmental-Economic Accounting.
- MoSPI: India’s environmental-economic accounting strategy.
- Stock measured at a point in time; flow measured over a period.
- Physical accounts and monetary accounts.
- Depletion, extraction and revaluation.
Mains Relevance
GS Paper 3
- Natural-resource accounting and sustainable development.
- Statistical capacity for environmental policy.
GS Paper 2
- Coordination across ministries, States and statistical agencies.
Essay
- Measuring prosperity beyond current production.
Background and Context
What Environmental Accounts Add
Environmental accounting connects information about nature with the economy through consistent definitions, classifications and accounting periods, rather than collecting unrelated environmental indicators.
- SEEA organizes resource stocks, resource use and associated economic information. Its value lies in linking measurements that otherwise sit in separate departmental reports, making relationships between production and natural assets easier to examine.
- GDP measures production during a period; it is not a complete balance sheet of nature. Higher output alone cannot establish whether the resource base supporting future production is being maintained or reduced.
- Asset accounts record what exists at the beginning and end of an accounting period. They also explain changes between those dates, so a declining stock becomes a question about causes, not merely totals.
- Flow accounts follow natural inputs entering the economy, products moving through it and residuals returning to the environment. Connecting these flows helps show how production depends on materials and produces environmental pressures.
- The Indian roadmap identifies subjects for expansion and stronger data coverage. It should be read as a programme for improving measurement, not evidence that a complete national environmental balance sheet has been produced.
How Stocks and Flows Fit Together
A stock account reconciles two snapshots by identifying the changes between them; a flow account follows activity during that same period.
- A physical stock might be timber volume in a forest at the start of the year. Timber removed during the year is a flow, measured over time rather than at a single date.
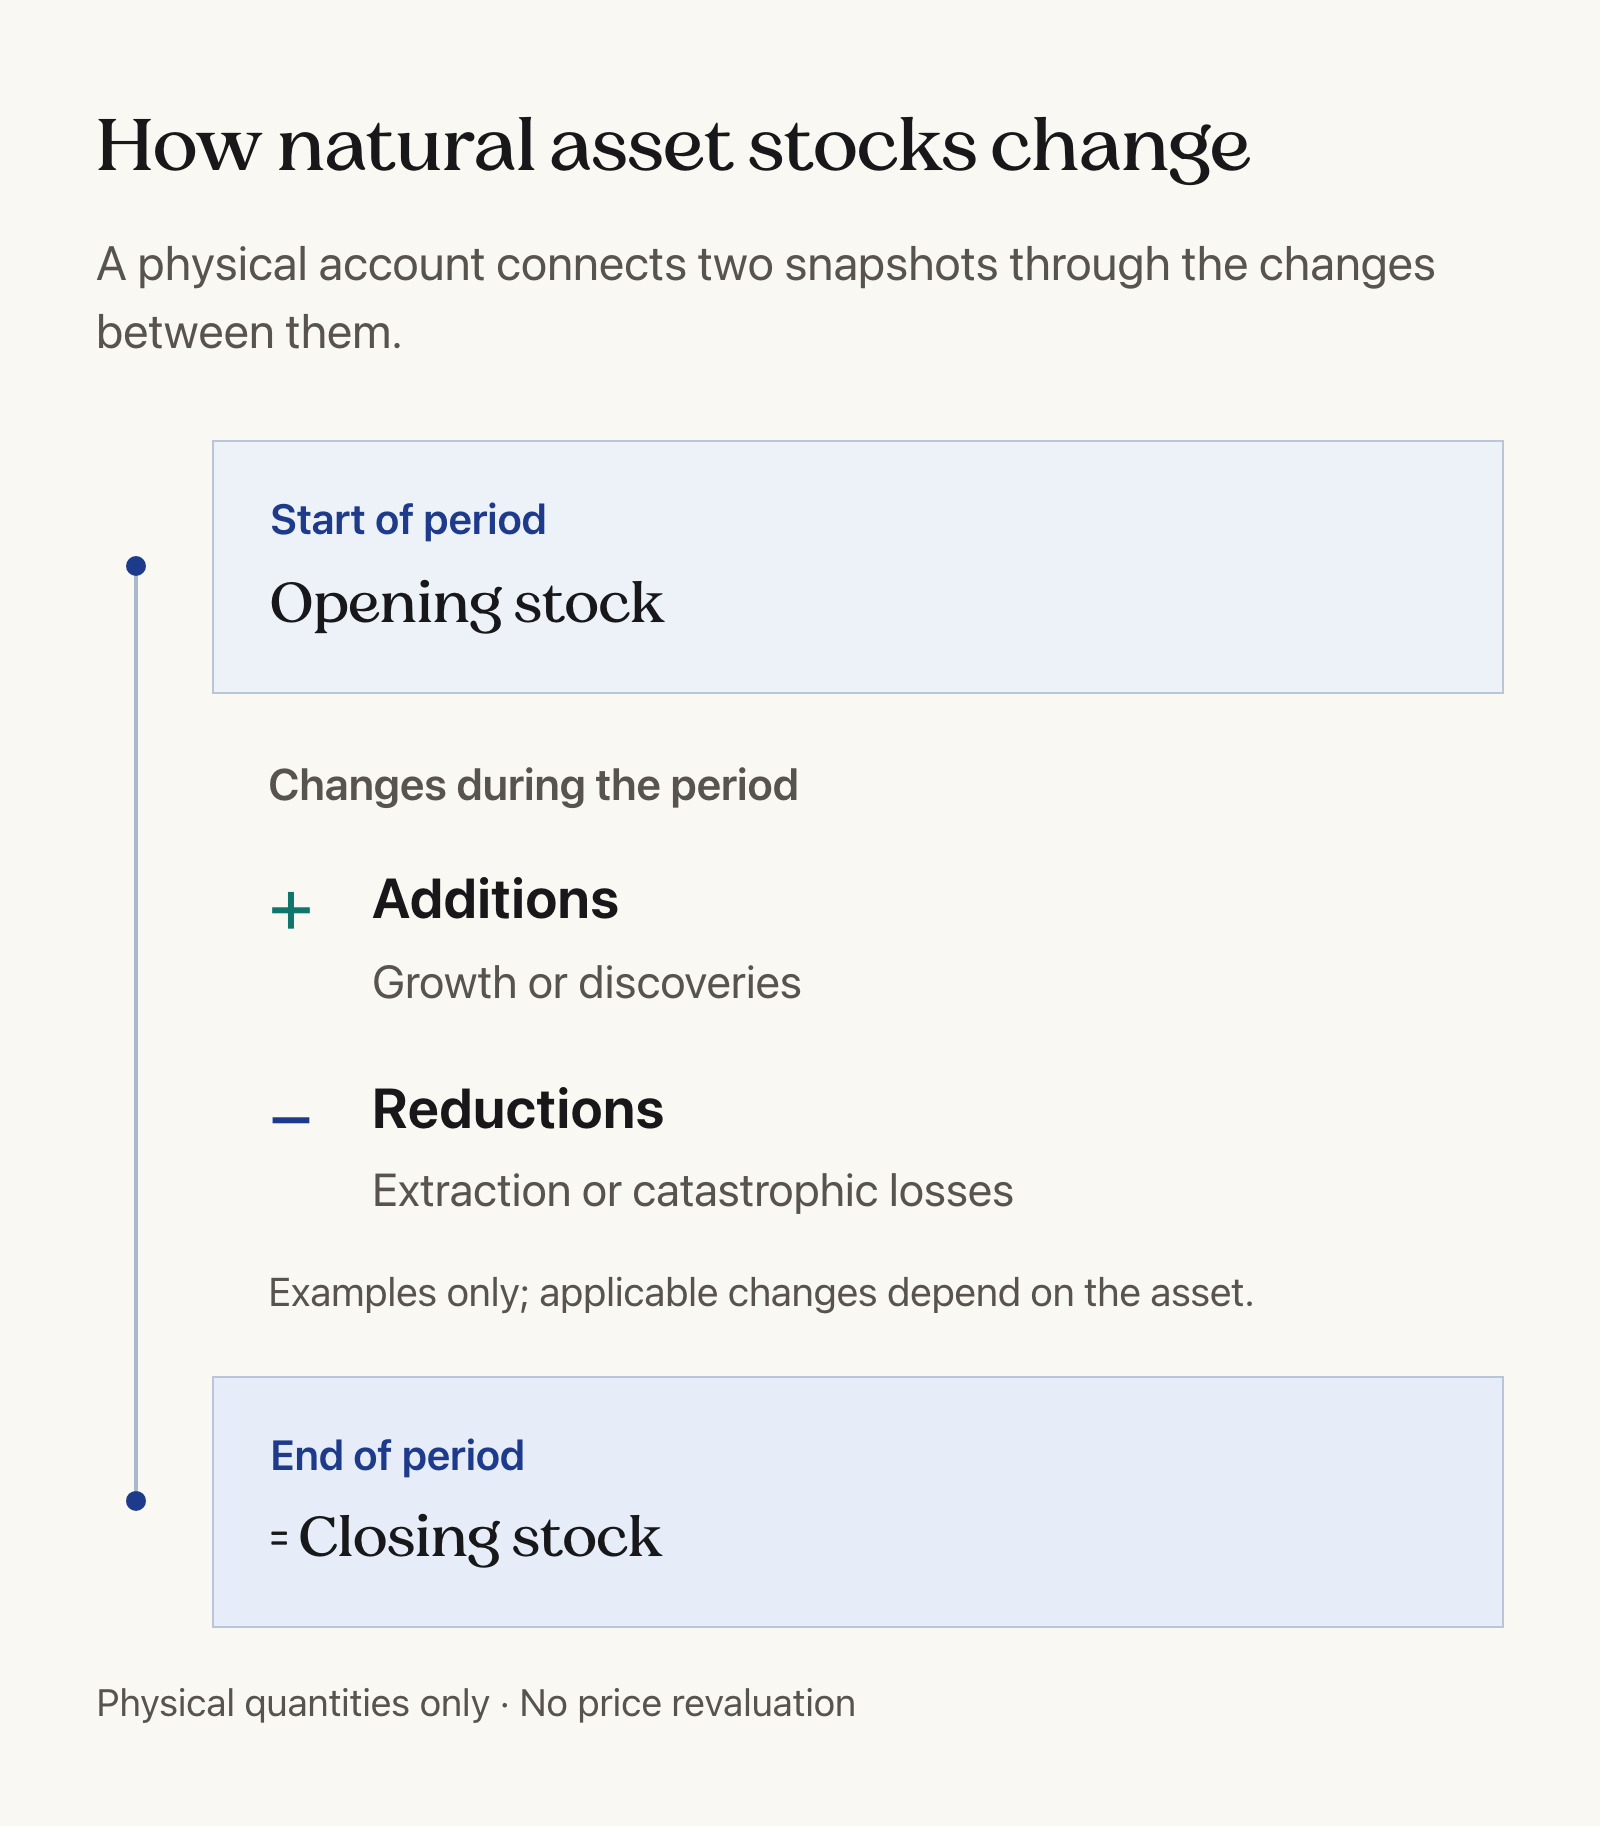
- Opening stock plus additions minus reductions equals closing stock in a physical asset account. Additions and reductions must be classified carefully: growth, discoveries, extraction and catastrophic losses do not describe the same process.
- Extraction records removal by economic units; it is not automatically identical to depletion for renewable resources. Regeneration matters when assessing whether resource use is reducing the available stock rather than drawing on replenishment.
- Depletion concerns resource use that reduces the stock after accounting for regeneration. A forest fire can also reduce timber stocks, but that loss should not be confused with timber extracted for economic activity.
- An economy may earn income from selling an extracted resource while its remaining natural assets shrink. Reading the production flow alongside the stock change exposes this distinction without assuming that all extraction is unsustainable.
Physical Measures, Monetary Values and Limits
Physical and monetary accounts answer different questions; combining them adds insight only when their coverage, timing and valuation assumptions remain transparent.
- Physical accounts use units such as tonnes, cubic metres or hectares, depending on the asset. They can record environmental assets even where no economic value has been assigned, avoiding dependence on market prices alone.
- Monetary accounts express eligible assets and flows in money using accounting valuation principles. Where observable market prices are unavailable, estimates require methods and assumptions; the resulting value is not an unquestionable price for nature.
- Revaluation is recorded separately in monetary stock accounts because prices can change even when physical quantity does not. A higher monetary asset value cannot, by itself, demonstrate that the underlying resource has recovered.
- Environmental expenditure records economic activity directed towards protection or resource management. Spending on restoration does not prove equivalent ecological recovery; outcomes still require evidence about the relevant asset, condition or resource stock.
- The strategy is not a replacement GDP release. It supports a broader evidence base for policy, while gaps in coverage, comparability and valuation must remain visible rather than disappear inside an invented green-GDP total.
Way Forward
Make the Accounts Usable
- Publish definitions, coverage and uncertainty with each account so users can distinguish observed changes from methodological revisions.
- Coordinate sectoral and State datasets around compatible classifications and accounting periods, while retaining locally meaningful resource information.
- Read physical quantities beside monetary values; identify whether a change comes from resource use, regeneration, reclassification or prices.
Conclusion
- Environmental accounts make the relationship between current production and the underlying natural-resource base easier to examine. Their contribution is disciplined measurement, not a claim that every ecological value can be converted into money.
- For an answer on sustainable development, connect economic flows with changes in natural stocks, then discuss data quality and valuation limits. Treat India’s new strategy as a roadmap whose implementation still needs to be assessed.
UPSC Practice Questions
Prelims MCQ 1
With reference to environmental-economic accounts, consider the following statements:
- Physical asset accounts reconcile opening stocks with closing stocks through additions and reductions.
- A rise in an asset’s monetary value necessarily proves an increase in its physical quantity.
- Environmental expenditure alone establishes an equivalent improvement in ecological condition.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (a) Only one
Explanation:
Only the first statement is correct. Price changes can raise monetary values without increasing quantities, and expenditure needs separate outcome evidence.
Prelims MCQ 2
Which entry specifically explains changes in the monetary value of an environmental asset caused by price movements?
(a) Extraction (b) Revaluation (c) Natural growth (d) Catastrophic loss
Answer: (b) Revaluation
Explanation:
Monetary asset accounts include revaluation separately from physical additions and reductions to identify effects of changing asset prices.
UPSC Mains Questions
- Explain how environmental-economic accounts improve the assessment of sustainable development. Discuss their principal measurement limitations. (150 words)
- Distinguish natural-resource stocks from economic flows. How can India’s environmental accounting strategy strengthen evidence-based resource management? (250 words)
Sources: PIB, Ministry of Statistics and Programme Implementation and United Nations Statistics Division, SEEA Central Framework.
Frequently Asked Questions
What is environmental-economic accounting?
Environmental-economic accounting connects environmental information with economic accounts through consistent definitions and classifications. It records resource stocks and flows so policy can consider natural assets alongside production and income.
Does the new strategy replace GDP?
No. The 2026–2030 document is a roadmap for expanding and strengthening environmental accounts. Its release does not introduce a replacement GDP measure or establish that all proposed accounts have been completed.
How is a stock different from a flow?
A stock is measured at a point in time, such as timber standing at the start of a year. A flow is measured during a period, such as timber extracted during that year.
Why can monetary values and physical quantities move differently?
A resource’s price can change while its physical quantity remains unchanged. Monetary accounts record this through revaluation, making it important to examine physical accounts before inferring that an environmental asset has improved.
Does spending more on restoration prove environmental improvement?
No. Expenditure records activity undertaken for environmental protection or resource management. Evidence about resource stocks or ecological condition is still needed to determine whether the spending produced the intended improvement.