The RBI’s Growing Fiscal Role: Surplus Transfers and the Central Bank’s Expanding Footprint
Why in News?
The Reserve Bank of India’s annual transfer of surplus to the Union government has grown so large that it now shapes the Centre’s fiscal arithmetic, not just its balance sheet. For 2024-25 the RBI paid a record ₹2.69 lakh crore dividend, a jump of roughly 27% over the ₹2.1 lakh crore transferred for 2023-24 and far above the ₹87,416 crore of 2022-23. The Hindu, examining this trend, argued that the central bank’s footprint has steadily crept into fiscal territory.
Behind the headline number sit deeper questions. The surplus is governed by Section 47 of the RBI Act, 1934 and sized by the Economic Capital Framework (ECF), whose revision in May 2025 widened the risk-buffer band the bank must hold. Alongside dividends, the RBI’s open market operations, foreign-exchange interventions and special liquidity windows carry quasi-fiscal consequences — reviving an old debate about the line between monetary and fiscal policy and the independence of the central bank.
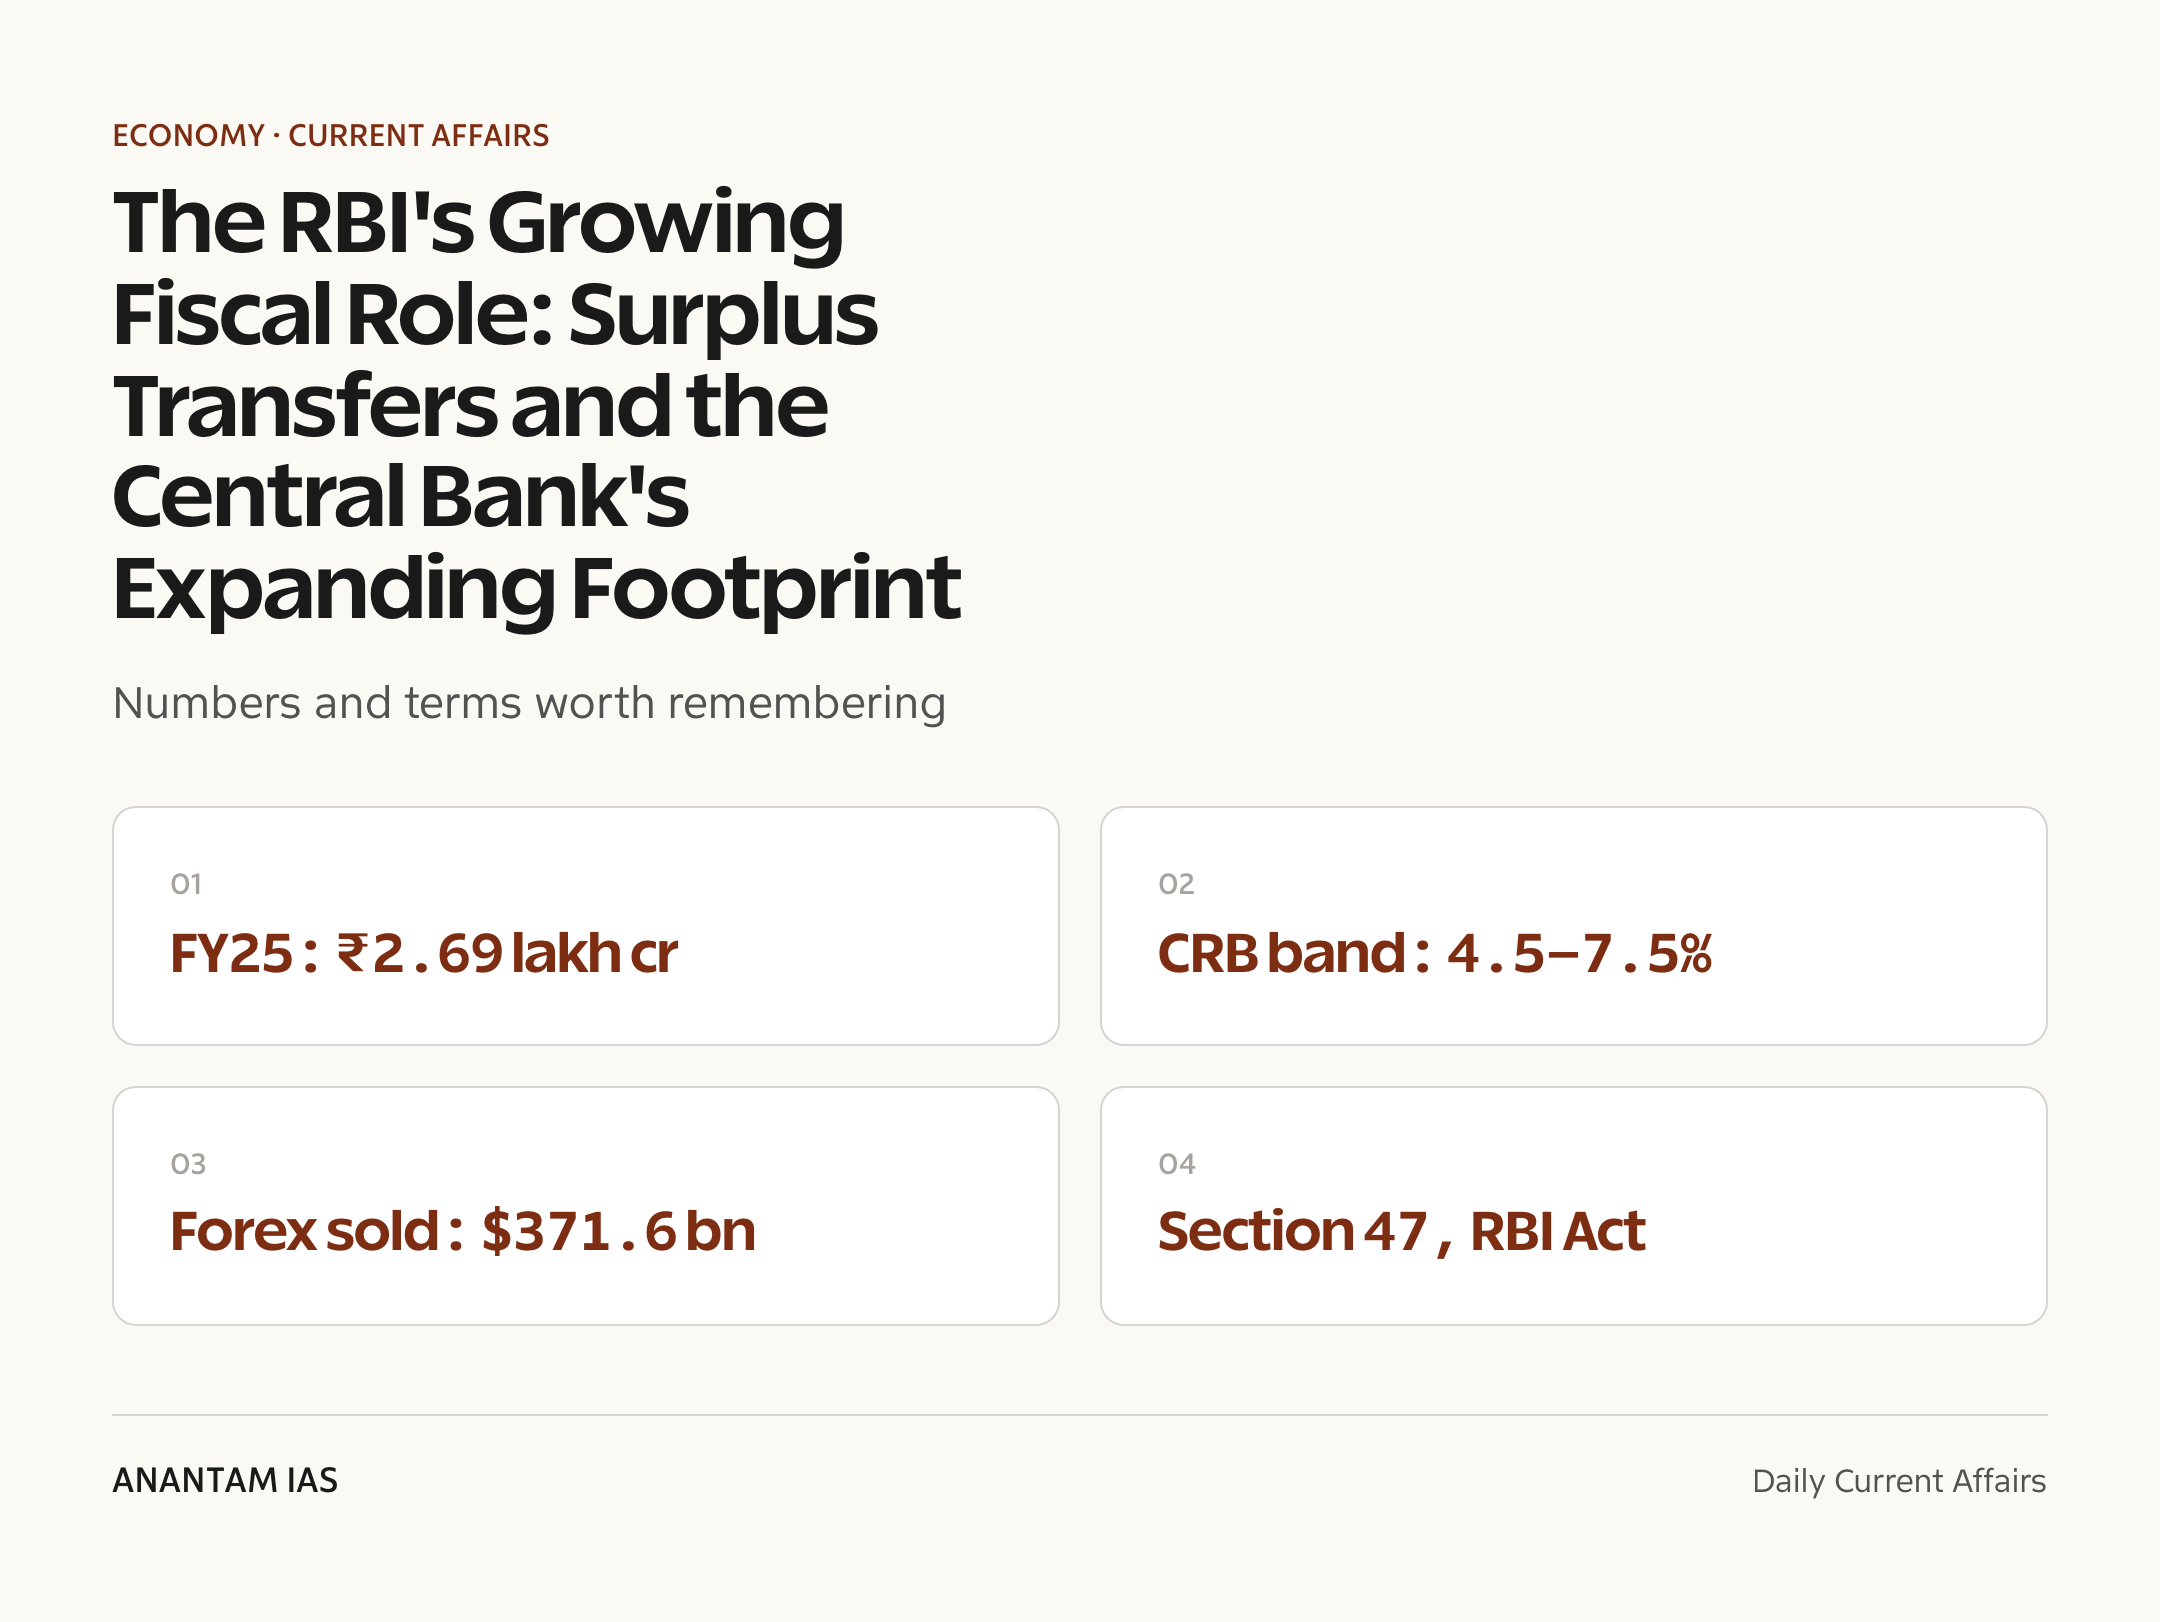
- For FY 2024-25 the RBI’s Central Board approved a record surplus transfer of ₹2.69 lakh crore to the government — about a 27% rise over FY24.
- The payout was sized under a revised Economic Capital Framework adopted by the Central Board on 15 May 2025 at its 616th meeting, chaired by Governor Sanjay Malhotra.
- The Contingent Risk Buffer (CRB) band was widened from the earlier 5.5%–6.5% to 4.5%–7.5% of the balance sheet; the board set the CRB at the upper bound of 7.5%.
- A large slice of the surplus came from forex operations — the RBI sold about $371.6 billion of foreign currency in FY25 to steady the rupee, more than double the prior year, generating valuation and trading gains.
- The scale of transfers, plus the RBI’s bond purchases and liquidity tools, has sharpened the debate on the monetary-fiscal boundary and central-bank independence.
The development matters in the context of:
- A central bank’s surplus is what remains after meeting expenses and setting aside provisions and reserves; the residual passes to the owner — in India, the Union government.
- The ECF, recommended by the Bimal Jalan Committee (2018) and adopted in August 2019, is the methodology that decides how much risk provisioning the RBI keeps and how much surplus it distributes.
- anantamias has separately covered the FY25 dividend announcement; this note treats the broader analytical question of how the RBI’s role has expanded into fiscal space.
UPSC Relevance
Prelims Relevance
- Section 47 of the RBI Act, 1934 mandates that the RBI’s surplus, after provisions, be paid to the Central government.
- The Economic Capital Framework (ECF) governs risk provisioning and surplus distribution; it was recommended by the Bimal Jalan Committee (2018) and adopted in August 2019.
- The Contingent Risk Buffer (CRB) is a provision against monetary, financial and operational risks; the original band was 5.5%–6.5%, revised in May 2025 to 4.5%–7.5% of the balance sheet.
- For FY 2024-25 the surplus transfer was a record ₹2.69 lakh crore; FY24 was ₹2.1 lakh crore and FY23 was ₹87,416 crore.
- The RBI’s income comes mainly from interest on domestic and foreign securities, gains on forex operations and seigniorage from currency issue.
- Open Market Operations (OMOs) are RBI purchases or sales of government securities to manage rupee liquidity; large-scale bond buying can indirectly support government borrowing.
- Direct monetisation of the deficit — the RBI printing money to fund the government — was effectively ended by the 1997 agreement that phased out ad hoc treasury bills and is fenced by the FRBM Act, 2003.
- The surplus is approved by the RBI Central Board; the financial year for these accounts now aligns with the government’s April–March year.
- Forex and gold revaluation gains are unrealised and held in revaluation accounts, not counted as distributable income unless realised through actual sales.
Mains Relevance
GS Paper 3
- Examine how the size and composition of RBI surplus transfers affect the Union government’s fiscal deficit and borrowing programme, and the risks of fiscal dependence on the central bank.
- Discuss the quasi-fiscal dimension of the RBI’s operations — OMOs, forex intervention and special liquidity windows — and the rationale of the Economic Capital Framework in balancing buffers against payouts.
GS Paper 2
- Evaluate the case for central-bank independence in India and how large, growing surplus transfers and the monetary-fiscal interface test the autonomy of the RBI vis-a-vis the executive.
Essay
- Where money policy ends and the budget begins — the eroding boundary between the central bank and the treasury.
- Independence with accountability: can an institution that funds the state also discipline it?
Background and Context
How the RBI earns and what it transfers
The surplus is a by-product of how a central bank holds its assets, not a profit motive.
- The RBI earns interest on its holdings of government securities (domestic) and foreign sovereign bonds, plus returns on deposits and gold.
- It also books gains from forex operations — buying and selling dollars to manage rupee volatility — and earns seigniorage, the difference between the face value of currency and its production cost.
- From this income it deducts expenditure (printing costs, agency charges, staff) and transfers to reserves and the Contingent Risk Buffer.
- Whatever remains is the distributable surplus, paid to the Centre under Section 47 of the RBI Act, 1934 — there is no separate tax; the central bank’s residual is the government’s revenue.
- For a refresher on the institution’s wider mandate, see our note on the Reserve Bank of India.
The Economic Capital Framework and the Jalan Committee
How much the RBI keeps versus distributes is decided by a formal framework, not discretion alone.
- After a 2018 standoff between the RBI and the Finance Ministry over how much reserve the bank should hold, a six-member committee under former Governor Bimal Jalan was set up to review economic capital.
- Its Economic Capital Framework, adopted in August 2019, splits the RBI’s economic capital into a realised-equity component (the CRB) and a revaluation-balances component (unrealised gains on forex and gold).
- The framework defined the Contingent Risk Buffer (CRB) band at 5.5%–6.5% of the balance sheet; any realised equity above the band could be transferred as surplus.
- In May 2025 the board adopted a revised ECF, widening the CRB band to 4.5%–7.5% and setting the actual buffer at 7.5% given the macroeconomic environment.
- The framework is meant to depoliticise the transfer decision — anchoring it to a rule rather than year-to-year bargaining between the bank and the government.
When dividends become fiscal arithmetic
Surplus transfers have grown large enough to influence the Union Budget’s deficit maths.
- The ₹2.69 lakh crore FY25 payout exceeded the dividend the government had budgeted, easing pressure on the fiscal deficit and the borrowing calendar.
- Such transfers are non-tax revenue — a windfall that can fund spending or trim market borrowing, but one that is volatile and tied to global rates and the rupee.
- A large slice of the FY25 surplus traced to forex sales of about $371.6 billion, more than double the prior year, which realised valuation gains as the rupee was defended.
- Reliance on a buoyant central-bank dividend can mask underlying fiscal slippage and is hard to repeat if forex gains or interest income fall.
- Read more on the wider picture in our explainer on the fiscal deficit.
Quasi-fiscal operations and the monetary-fiscal boundary
Beyond dividends, several RBI tools carry fiscal-like consequences that blur the policy line.
- Open Market Operations (OMOs) — RBI purchases of government bonds to inject liquidity — lower yields and indirectly ease the cost of government borrowing, even when the aim is purely monetary.
- Forex intervention to manage the rupee builds or runs down reserves and creates revaluation gains or losses that feed into the surplus.
- Special liquidity windows, sectoral refinancing and crisis facilities can allocate credit in ways that resemble fiscal choices.
- Direct monetisation of the deficit — the RBI printing money to fund the Centre — was largely ended after the 1997 supplemental agreement phased out ad hoc treasury bills, and is constrained by the FRBM Act, 2003; but bond buying and forex operations keep the boundary porous.
- The Hindu’s argument is that the cumulative effect of these instruments expands the RBI’s fiscal footprint well beyond its dividend cheque.
The independence question
A central bank that funds the state and steadies its bond market must guard its autonomy.
- Central-bank independence rests on insulating monetary decisions from short-term political and fiscal pressures — a credibility anchor for inflation control.
- Large, growing transfers create an incentive for the executive to view the RBI as a revenue source, risking pressure to under-provision or distribute more.
- The ECF, by tying transfers to a rule and a buffer range, is a safeguard — but a wide band still leaves the buffer level to board judgement.
- Independence is not absence of accountability: the RBI answers to Parliament, publishes accounts and operates the inflation-targeting framework agreed with the government.
- The balance, as commentators note, lies in transparent, rule-based surplus decisions and clear separation between liquidity management and deficit financing.
Way Forward
Rule-based, transparent transfers
- Disclose the ECF computation and CRB rationale each year so the surplus is seen as rule-driven, not negotiated.
- Communicate the volatility of forex-linked income so the Budget does not over-rely on a buoyant dividend.
Guard the monetary-fiscal line
- Keep OMOs and liquidity tools transparently anchored to monetary objectives, not to financing the deficit.
- Preserve the post-1997 firewall against direct monetisation and respect FRBM discipline on the fiscal side.
Strengthen the RBI’s institutional autonomy with clear board processes, fixed tenures and published minutes, so independence rests on rules rather than personalities.
Conclusion
The RBI’s surplus has grown from a routine accounting residual into a number that moves the Union Budget. Behind it sits a deliberate architecture — Section 47, the Economic Capital Framework and the Contingent Risk Buffer — designed to balance financial safety against the government’s claim on the bank’s earnings. The May 2025 revision and the record ₹2.69 lakh crore transfer show that architecture in action.
The harder challenge is conceptual. As OMOs, forex intervention and large dividends pull the central bank deeper into fiscal territory, the line between managing money and funding the state grows fainter. Keeping that line visible — through rule-based transfers, transparency and a firewall against deficit financing — is what will protect both the credibility of monetary policy and the independence of the institution behind it.
UPSC Practice Questions
Prelims MCQ 1
With reference to the RBI’s surplus transfer to the government, consider the following statements:
- The transfer of the RBI’s surplus to the Central government is mandated by Section 47 of the RBI Act, 1934.
- The Economic Capital Framework governing this transfer was recommended by the Bimal Jalan Committee.
- The surplus is paid to the government only after Parliament passes a separate appropriation bill.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 1 and 2 are correct — Section 47 of the RBI Act, 1934 requires the surplus to be paid to the Centre, and the Economic Capital Framework was recommended by the Bimal Jalan Committee (2018) and adopted in 2019. Statement 3 is wrong: the transfer is approved by the RBI’s Central Board, not contingent on a separate appropriation bill.
Prelims MCQ 2
The Contingent Risk Buffer (CRB) of the Reserve Bank of India is best described as:
(a) A statutory cash reserve that commercial banks keep with the RBI (b) A provision the RBI holds against monetary, financial and operational risks, sized as a band of its balance sheet (c) A fund earmarked exclusively for recapitalising public sector banks (d) The portion of foreign-exchange reserves pledged to the IMF
Answer: (b) A provision the RBI holds against monetary, financial and operational risks, sized as a band of its balance sheet
Explanation:
Under the Economic Capital Framework, the CRB is the realised-equity buffer the RBI maintains against monetary, financial and operational risks. Its band was 5.5%–6.5% of the balance sheet and was revised in May 2025 to 4.5%–7.5%, with the buffer set at 7.5%. It is unrelated to the Cash Reserve Ratio kept by commercial banks.
UPSC Mains Questions
- The Reserve Bank of India’s surplus transfers have grown large enough to shape the Union government’s fiscal arithmetic. Examine the role of the Economic Capital Framework and the Contingent Risk Buffer in sizing these transfers, and the risks of fiscal dependence on the central bank. (250 words)
- “The boundary between monetary and fiscal policy is becoming harder to draw.” In the light of the RBI’s open market operations, forex interventions and dividend transfers, discuss the challenges to central-bank independence in India. (250 words)
Source: The Hindu.
Frequently Asked Questions
Why does the RBI transfer a surplus to the government?
The RBI is owned by the Union government, so its income left over after expenses, provisions and reserves — the surplus — belongs to the Centre. Section 47 of the RBI Act, 1934 requires this residual to be paid to the government. It is non-tax revenue, not a profit dividend in the corporate sense.
What is the Economic Capital Framework (ECF)?
The ECF is the methodology that decides how much risk provisioning the RBI keeps and how much surplus it can distribute. Recommended by the Bimal Jalan Committee and adopted in August 2019, it splits economic capital into a realised-equity buffer (the CRB) and unrealised revaluation balances on forex and gold. It was revised in May 2025.
What is the Contingent Risk Buffer and what was changed in 2025?
The Contingent Risk Buffer (CRB) is the realised-equity provision the RBI holds against monetary, financial and operational risks. Its band was 5.5%–6.5% of the balance sheet. In May 2025 the revised ECF widened the band to 4.5%–7.5%, and the board set the buffer at the upper bound of 7.5%.
How big was the FY 2024-25 surplus transfer?
For 2024-25 the RBI transferred a record ₹2.69 lakh crore to the Central government — roughly 27% more than the ₹2.1 lakh crore of 2023-24 and far above the ₹87,416 crore of 2022-23. A large share came from forex operations, with the RBI selling about $371.6 billion to steady the rupee.
What does ‘quasi-fiscal’ mean for a central bank?
Quasi-fiscal operations are central-bank actions that resemble government spending or taxation. RBI bond purchases (OMOs) ease the cost of government borrowing, forex intervention reshapes reserves, and special liquidity windows allocate credit. These have budget-like effects even when the stated aim is monetary, blurring the monetary-fiscal boundary.
Why does this raise central-bank independence concerns?
Independence shields monetary decisions from short-term fiscal and political pressure, anchoring inflation credibility. When transfers grow large, the government may treat the RBI as a revenue source and push for higher payouts or lower buffers. Rule-based transfers under the ECF and a firewall against deficit financing are the safeguards.