RBI Overhauls TReDS: Easier MSME Onboarding and Credit-Guarantee Cover for Financiers
Why in News?
The Reserve Bank of India has issued revised directions consolidating the rules that govern the Trade Receivables Discounting System (TReDS) — an RBI-regulated electronic platform on which Micro, Small and Medium Enterprises (MSMEs) sell their unpaid invoices to lenders for early cash. The new framework folds scattered instructions into a single Master Direction and reworks how sellers join, who can lend, and who can stand guarantee.
The overhaul matters because delayed payments are a chronic drain on MSME working capital. By simplifying onboarding, permitting credit-guarantee and insurance cover for financiers, and admitting government-notified guarantee funds and insurers onto the platform, the RBI is trying to deepen trade-receivables financing and pull more small firms into the formal credit system.
- The RBI has consolidated existing TReDS instructions into a single Master Direction, replacing a patchwork of earlier circulars.
- MSME onboarding is simplified; operators must build validation checks so only genuine MSMEs participate and dues are credited to the seller’s own bank account.
- Financiers may now obtain credit-guarantee cover and insurance for factoring units financed on the platform.
- Insurance companies and government-notified credit guarantee fund trusts are allowed to participate on TReDS.
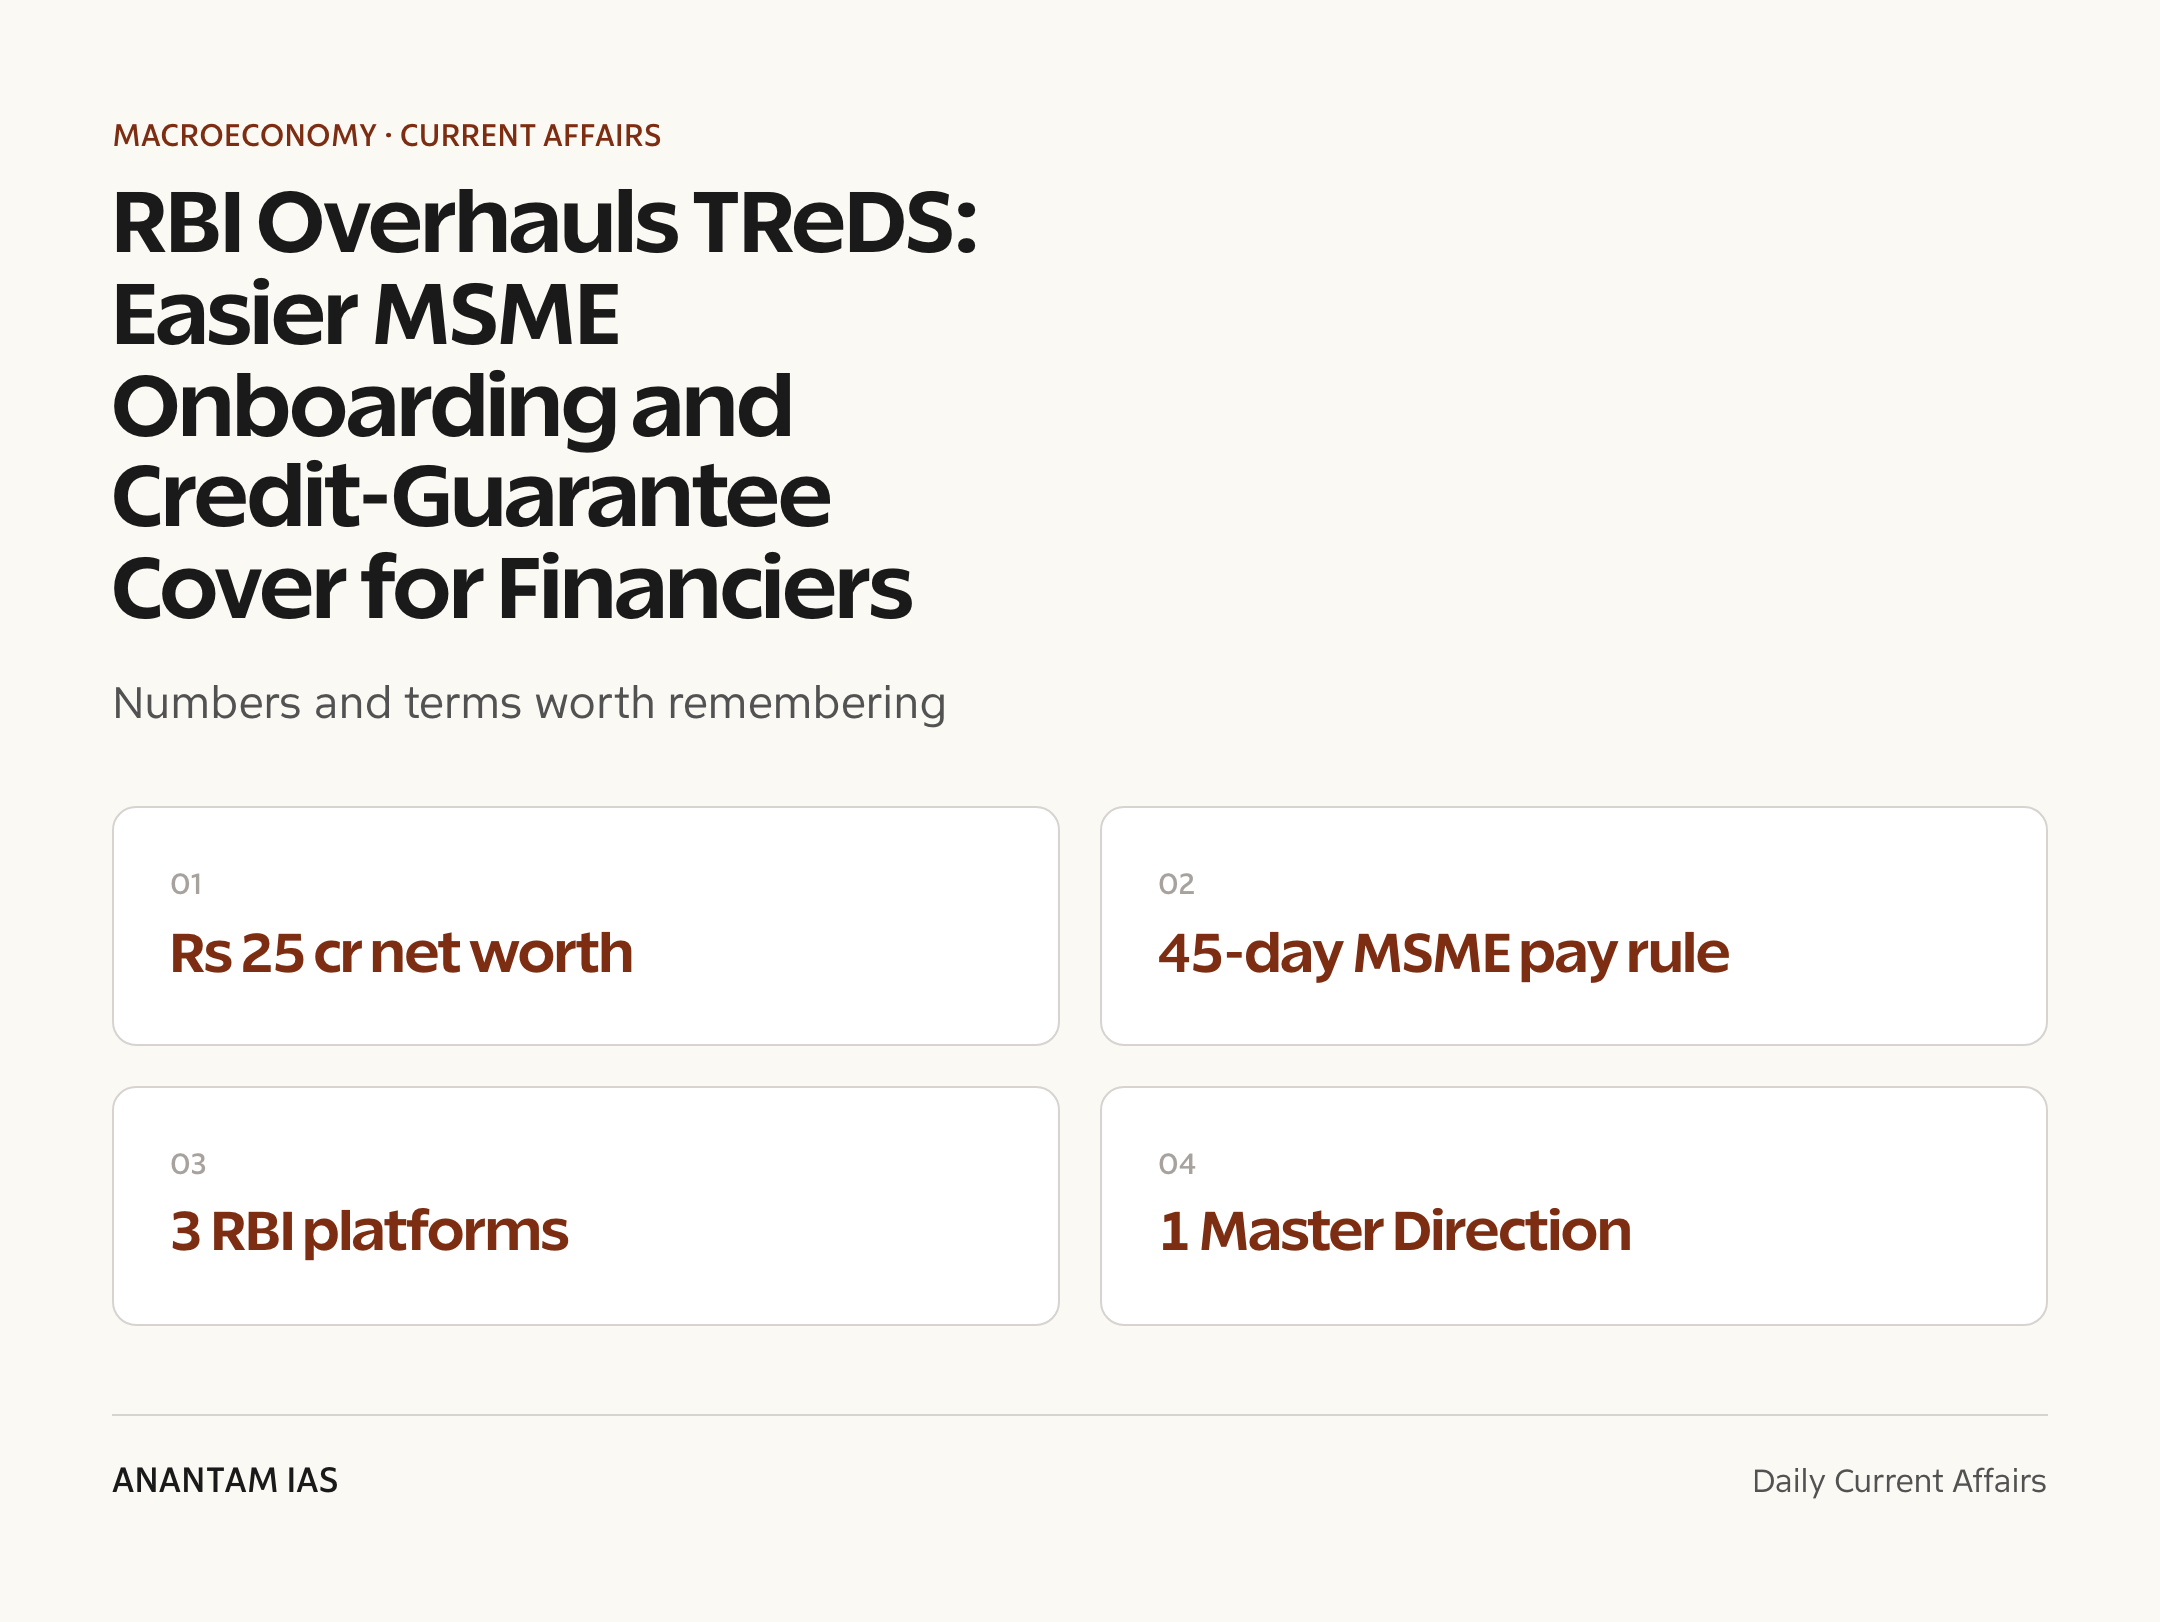
- The minimum net-worth floor for TReDS operators is aligned at Rs 25 crore, matching other non-bank payment system operators.
The development matters in the context of:
- TReDS platforms have operated since 2017 (RXIL, M1xchange, Invoicemart) under RBI’s 2014 guidelines and the Payment and Settlement Systems Act, 2007.
- Mandatory onboarding of large companies and CPSEs above turnover thresholds was earlier pushed to widen the buyer base.
UPSC Relevance
Prelims Relevance
- TReDS: an RBI-regulated electronic platform for financing/discounting MSME trade receivables through multiple financiers via factoring and bill discounting.
- Factoring: a financier buys a business’s receivables (invoices) at a discount, giving the seller immediate cash and assuming collection.
- Factoring Regulation Act, 2011, amended in 2021 to widen the pool of eligible lenders (allowing non-NBFC entities to undertake factoring).
- MSMED Act, 2006: governs MSME definition and the delayed-payment provisions, including the 45-day payment rule.
- 45-day rule: buyers must pay MSME suppliers within 45 days of acceptance, with compound interest at three times the bank rate on delay.
- TReDS is authorised as a payment system under the Payment and Settlement Systems Act, 2007, supervised by the RBI.
- Revised operator net-worth floor: Rs 25 crore, aligned with other non-bank payment system operators.
- Participants now include sellers (MSMEs), buyers, financiers, insurers and government-notified credit guarantee funds.
- Financial inclusion: bringing underserved small firms into the formal financial system at affordable cost.
Mains Relevance
GS Paper 3
- Demonstrates how regulatory design can ease the working-capital squeeze on MSMEs, a sector contributing roughly a third of GDP and the bulk of non-farm employment.
- Illustrates the link between financial inclusion, credit-risk sharing through guarantees, and formalisation of small enterprises.
- Shows the role of digital public infrastructure (electronic discounting platforms) in widening access to institutional credit.
- Ties to the broader delayed-payments problem and the MSMED Act enforcement gap that TReDS partly addresses.
Essay
- Small enterprises and the architecture of trust: how guarantees and digital platforms can unlock credit for those at the margins of formal finance.
- Reform is incremental — institutions matter more than slogans in fixing the delayed-payment burden on India’s small businesses.
Background and Context
What TReDS is and why it exists
TReDS is the RBI’s answer to a simple but stubborn problem: small suppliers wait too long to be paid.
- The Trade Receivables Discounting System is an electronic platform where MSMEs upload invoices owed by their corporate or government buyers and auction them to multiple financiers for early payment.
- It works through factoring and bill discounting — the financier advances cash against the invoice at a discount, recovering the full amount from the buyer on the due date.
- Competitive bidding among financiers is meant to lower the discount rate, giving MSMEs cheaper, collateral-light working capital.
- Three RBI-authorised platforms — RXIL, M1xchange and Invoicemart — have run since 2017 under the Payment and Settlement Systems Act, 2007.
The MSME delayed-payments problem
TReDS sits on top of a long-standing structural weakness in how MSMEs get paid.
- MSMEs depend on larger buyers who often stretch payment cycles, locking up the small firm’s working capital and forcing costly informal borrowing.
- The MSMED Act, 2006 mandates payment within 45 days of acceptance, with penal compound interest on delay, but enforcement through MSE Facilitation Councils remains slow.
- By converting an unpaid invoice into immediate cash, TReDS offers a market route around the enforcement gap.
- Thin participation and onboarding friction have limited TReDS volumes relative to the size of MSME receivables outstanding.
The factoring framework behind the platform
TReDS rests on India’s factoring law, which was widened to bring in more lenders.
- The Factoring Regulation Act, 2011 created the legal basis for assignment of receivables and registration of factoring transactions.
- The 2021 amendment removed restrictive thresholds and let entities beyond a narrow set of NBFCs undertake factoring, expanding the lender pool.
- A wider lender base on TReDS is meant to raise competition for invoices and improve pricing for sellers.
- The revised directions build on this by inviting insurers and government credit guarantee funds into the same ecosystem.
What the revised directions change
The RBI’s overhaul touches onboarding, risk cover, participants and operator strength.
- Simpler onboarding: operators must run validation mechanisms to confirm a seller is a genuine MSME and ensure proceeds reach only the seller’s bank account.
- Guarantee cover for financiers: lenders may obtain credit-guarantee cover for factoring units from any government-set-up credit guarantee fund trust, plus insurance.
- New participants: insurance companies and government-notified credit guarantee funds are permitted to operate on TReDS.
- Operator net worth: aligned at Rs 25 crore with other non-bank payment system operators, with existing entities given time to comply.
- Consolidation: scattered earlier instructions are merged into one Master Direction for clarity.
Why it matters for financial inclusion
Guarantees and a broader participant base are designed to coax more lending toward small firms.
- Credit-guarantee and insurance cover reduce the financier’s downside, encouraging lending to MSMEs that might otherwise be seen as risky.
- Admitting insurers and guarantee funds spreads risk across more institutions, a classic financial-inclusion lever.
- Cleaner onboarding rules protect against misuse while lowering the entry barrier for genuine small suppliers.
- A stronger operator net-worth floor improves the resilience of the platforms handling these transactions.
Way Forward
Pair the eased onboarding with active outreach so that the smallest and informal MSMEs — not just larger ones already on the platform — actually use TReDS.
Tighten enforcement of the MSMED Act 45-day rule alongside market routes, so TReDS complements rather than substitutes for the buyer’s legal obligation to pay on time.
Track whether guarantee cover translates into lower discount rates for sellers, and calibrate guarantee-fund parameters to avoid moral hazard among financiers.
Conclusion
The revised TReDS directions are an incremental but meaningful step: by easing onboarding, sharing risk through guarantees and insurers, and strengthening operators, the RBI is trying to make trade-receivables financing a genuine working-capital lifeline for small firms.
The test will be uptake. A simpler platform with deeper risk-cover only delivers if more MSMEs sell invoices on it and see cheaper, faster cash — the real measure of whether the reform dents the delayed-payment problem.
UPSC Practice Questions
Prelims MCQ 1
With reference to the Trade Receivables Discounting System (TReDS), consider the following statements: 1. It is an electronic platform regulated by the Reserve Bank of India for financing MSME trade receivables. 2. It operates as an authorised payment system under the Payment and Settlement Systems Act, 2007. 3. Only banks are permitted to act as financiers on the platform. Which of the statements given above is/are correct?
1 and 2 only 2 and 3 only 1 and 3 only 1, 2 and 3
Answer: 1 and 2 only
Explanation:
TReDS is an RBI-regulated electronic platform authorised under the Payment and Settlement Systems Act, 2007 (statements 1 and 2 correct). Multiple financiers — not just banks — participate, and the revised directions further widen participation to insurers and government credit guarantee funds, so statement 3 is incorrect.
Prelims MCQ 2
Consider the following statements regarding the legal framework for MSME receivables financing in India: 1. The MSMED Act, 2006 requires buyers to pay MSME suppliers within 45 days of acceptance of goods or services. 2. The Factoring Regulation (Amendment) Act, 2021 narrowed the set of entities permitted to undertake factoring. Which of the statements given above is/are correct?
1 only 2 only Both 1 and 2 Neither 1 nor 2
Answer: 1 only
Explanation:
The MSMED Act, 2006 sets a 45-day payment limit with penal interest on delay (statement 1 correct). The 2021 amendment to the Factoring Regulation Act widened, not narrowed, the pool of eligible lenders by removing restrictive thresholds, so statement 2 is incorrect.
UPSC Mains Questions
- Delayed payments remain a chronic drain on MSME working capital. Examine how the Trade Receivables Discounting System (TReDS) and the recent revisions to its framework address this problem, and what limits their effectiveness. (250 words)
- “Risk-sharing instruments such as credit guarantees can widen the flow of formal credit to small enterprises.” Critically analyse this statement in the light of the RBI’s revised TReDS directions. (250 words)
- Discuss the role of digital platforms and the factoring framework in advancing financial inclusion for MSMEs in India. (150 words)
Sources: Reserve Bank of India and Business Standard.
Frequently Asked Questions
What is TReDS in simple terms?
TReDS, the Trade Receivables Discounting System, is an RBI-regulated electronic platform where MSMEs sell their unpaid invoices to financiers for immediate cash, instead of waiting for the buyer to pay. Multiple financiers bid for the invoice, which helps the small firm get cheaper working capital.
What has the RBI changed in the revised TReDS directions?
The RBI consolidated scattered rules into a single Master Direction, simplified how MSMEs join the platform, allowed financiers to obtain credit-guarantee and insurance cover, permitted insurers and government credit guarantee funds to participate, and aligned the minimum net-worth of operators at Rs 25 crore with other non-bank payment system operators.
How does TReDS help with the MSME delayed-payments problem?
Small suppliers often wait months for large buyers to pay, locking up their cash. TReDS converts an unpaid invoice into immediate funds, offering a market route around the slow enforcement of the MSMED Act’s 45-day payment rule. It complements, but does not replace, the buyer’s legal duty to pay on time.
What is factoring and how is it linked to TReDS?
Factoring is when a financier buys a business’s receivables (invoices) at a discount, giving the seller cash now and collecting from the buyer later. TReDS runs on factoring and bill discounting. The Factoring Regulation Act, 2011, amended in 2021, widened the pool of lenders allowed to do factoring, deepening the platform’s financier base.
Why does the Rs 25 crore net-worth requirement matter?
Aligning the minimum net worth of TReDS operators at Rs 25 crore — the same floor as other non-bank payment system operators — strengthens the financial resilience of the platforms handling MSME transactions. Existing operators are given a transition window to meet the requirement.
Who can participate on TReDS after the revision?
Sellers (MSMEs), buyers (corporates, CPSEs and government entities), and financiers participate, and the revised directions additionally admit insurance companies and government-notified credit guarantee fund trusts. This broadens the base of institutions sharing the credit risk of MSME lending.