Small Finance Bank

Why in news:
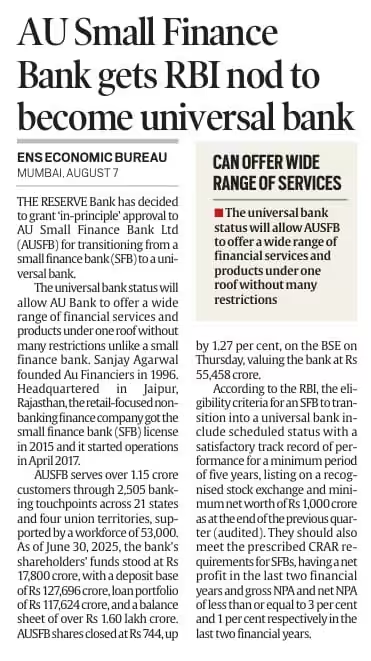
The Reserve Bank of India (RBI) has granted in-principle approval to AU Small Finance Bank (AU SFB) to transition into a Universal Bank. This is a significant upgrade, allowing AU SFB to offer a wider range of financial products and services without the regulatory limitations that apply to Small Finance Banks (SFBs).
UPSC CSE Relevance:
UPSC has asked questions on banking sector every year.
UPSC PYQ 2021:
With reference to “Urban Cooperative Banks’ in India, consider the following statements:
- They are supervised and regulated by local boards set up by the State Governments.
- They can issue equity shares and preference shares.
- They were brought under the purview of the Banking Regulation Act, 1949 through an Amendment in 1966.
Which of the statements given above is/are correct?
A 1 only
B 2 and 3 only
C 1 and 3 only
D 1, 2 and 3
Differentiated Banks:
A differentiated license will allow a bank to offer products only in select areas. Main aim is to promote financial inclusion and payments. Differentiated banks licensing was launched in 2015. The differentiated banks are of two types namely payment banks and small finance banks.
About Small Finance Bank:
- Aim: Small Finance Banks (SFBs) are specialised financial institutions established with the primary goal of fostering financial inclusion by offering basic banking services to underserved and unbanked segments of society.
- Set up based upon recommendations of Nachiket Mor Committee.
- Register under: Registered under Companies Act, 2013
- Licensed under: Banking Regulation Act, 1949
- Who is eligible: Resident Indians, Private Companies, Societies, NBFCs, MFIs, Local Area Banks
- Small Finance Banks must be listed as scheduled banks and must demonstrate a consistent and satisfactory performance record for at least five years.
- Capital Requirement: 200 crore (except for some SFBs)
- Deposit Insurance: Yes it is available
- Loan: At least 50 per cent of its loan portfolio must consist of loans and advances of up to ₹25 lakh.
- CRR and SLR Applicable
- Requirement: They must allocate at least 75% of their Adjusted Net Bank Credit (ANBC) towards priority sector lending.
- Regulated by RBI.
Universal Bank:
Universal Banks are financial institutions that offer a comprehensive range of financial services, extending beyond traditional commercial and investment banking. These may include insurance, wealth management, and other allied services—all under one roof.
Eligibility:
Net Worth: The Small Finance Bank must have a minimum net worth of ₹1,000 crore.
Regulatory Status:
- The SFB must be a scheduled commercial bank.
- It must demonstrate a satisfactory performance record over a minimum of five years.
Financial Health:
- Profitability: The bank should have recorded net profits in each of the last two financial years.
- Asset Quality:
- Gross Non-Performing Assets (GNPA): ≤ 3%
- Net Non-Performing Assets (NNPA): ≤ 1%
- Both figures are evaluated over the past two financial years.
Stock Listing:
- The bank’s shares must be listed on a recognized stock exchange in India.
Promoter Restrictions:
- No new promoters can be added during the transition process.
- No changes are allowed to the existing promoter structure.
- The promoter shareholding dilution plan approved by RBI must remain unchanged.
Loan Book Diversification:
Preference will be given to SFBs that have a well-diversified loan portfolio, ensuring reduced concentration risk.
Practice Question (UPSC PYQ):
Q: What is the purpose of setting up of Small Finance Banks (SFBs) in India?
- To supply credit to small business units
- To supply credit to small and marginal farmers
- To encourage young entrepreneurs to set up business particularly in rural areas.
Select the correct answer using the code given below:
(a) 1 and 2 only
(b) 2 and 3 only
(c) 1 and 3 only
(d) 1, 2 and 3