GST in India: Complete Guide for UPSC
Complete UPSC guide to GST in India — 101st Amendment, GST Council, CGST/SGST/IGST/UTGST, rate slabs, compensation cess, impact on federalism, e-way bill, and exam strategy.
GST in India: Complete Guide for UPSC
The Goods and Services Tax is the biggest indirect tax reform in India’s post-independence history. It replaced a maze of over 17 central and state taxes with one unified levy on the supply of goods and services. GST came into force on 1 July 2017 through the 101st Constitutional Amendment Act, 2016 — and it reshaped not just how India taxes, but how its federal structure works. For UPSC, GST appears across Prelims, Mains GS-III, and even Essay papers. You need to understand the mechanics, the constitutional backbone, and the political economy around it.
Constitutional Basis: The 101st Amendment Act, 2016
GST doesn’t rest on ordinary legislation alone. It required changing the Constitution itself — because taxation powers were divided between the Centre and states, and neither could levy a unified tax alone.
What the 101st Amendment Did
The Constitution (One Hundred and First Amendment) Act, 2016 made four core changes:
- Article 246A — Inserted a new article giving both Parliament and state legislatures concurrent power to legislate on GST. Parliament has exclusive power over inter-state supply. This was unprecedented: before this, the Seventh Schedule gave the Centre and states distinct, non-overlapping tax domains.
- Article 269A — Tax on inter-state supply of goods and services is levied and collected by the Centre but apportioned between the Centre and states as the GST Council recommends.
- Article 279A — Created the GST Council, a constitutional body to make recommendations on all GST-related matters.
- Amendments to Schedules — Several entries in the Union List and State List were deleted or modified to remove the older taxes subsumed under GST.
The amendment required ratification by at least half of state legislatures — and it got it. This level of federal buy-in was itself remarkable.
Taxes Subsumed Under GST
| Central Taxes Removed | State Taxes Removed |
|---|---|
| Central Excise Duty | VAT / Sales Tax |
| Service Tax | Entertainment Tax (except local bodies) |
| CST (Central Sales Tax) | Luxury Tax |
| Additional Customs Duty (CVD) | Entry Tax / Octroi |
| Special Additional Duty of Customs | Purchase Tax |
| Countervailing Duty | Taxes on advertisements |
Petroleum products (crude, diesel, petrol, ATF, natural gas) and alcohol for human consumption are outside GST for now. States still collect excise on alcohol; petroleum remains under the old regime.
The Four Types of GST: CGST, SGST, IGST, UTGST
This is the section UPSC tests most directly. You must know not just the acronyms but how each works.
CGST — Central Goods and Services Tax
Levied by the Central Government on intra-state transactions (where both buyer and seller are in the same state). Revenue goes entirely to the Centre. Governed by the CGST Act, 2017.
SGST — State Goods and Services Tax
Levied by the State Government on the same intra-state transaction simultaneously with CGST. Revenue goes entirely to the state. Each state has its own SGST Act but all are mirror images of the CGST Act.
So on a single intra-state sale — say, a shirt sold in Maharashtra — both CGST and SGST apply. If the rate is 12%, the buyer pays 6% CGST + 6% SGST. The Centre gets half, Maharashtra gets half.
IGST — Integrated Goods and Services Tax
Levied by the Central Government on inter-state transactions and imports. When goods or services move from one state to another, IGST applies. The Centre collects the full IGST and then apportions the state’s share to the destination state. Governed by the IGST Act, 2017.
This solves the old problem of cascading taxes and origin-state vs destination-state disputes. Under GST, consumption-state gets the revenue — so Tamil Nadu gets the GST when a Delhi consumer buys a product made in Tamil Nadu and shipped to Delhi.
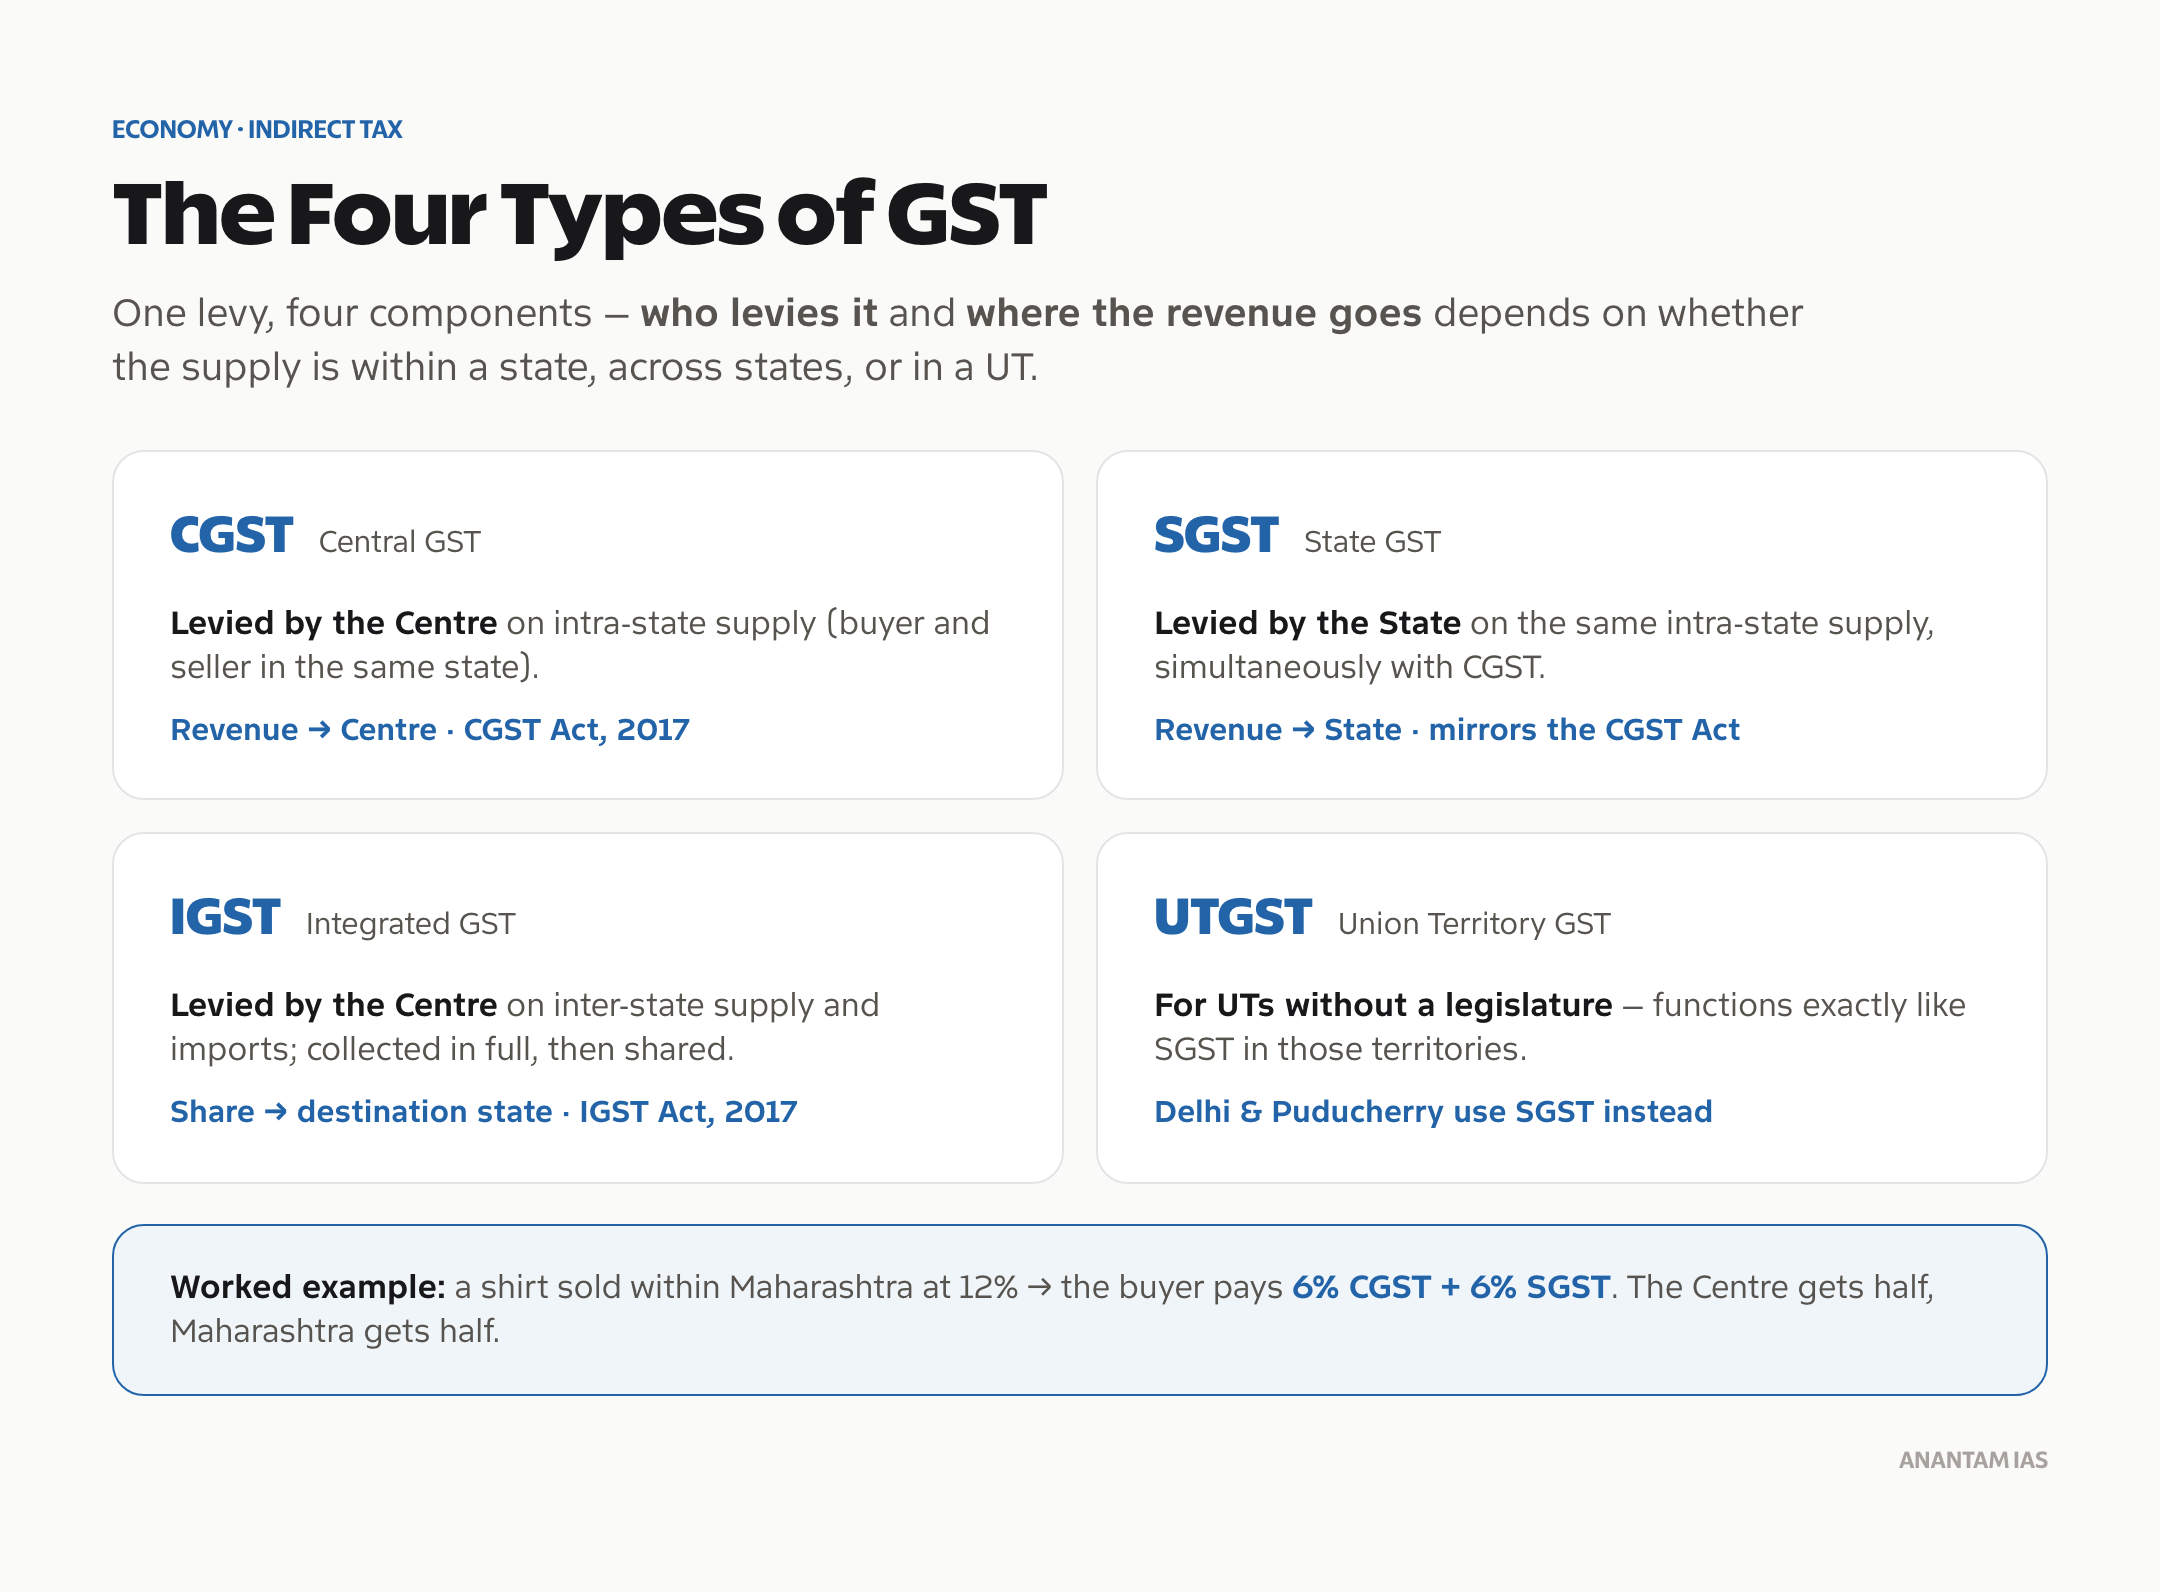
UTGST — Union Territory Goods and Services Tax
Levied in Union Territories that don’t have their own legislature (Dadra & Nagar Haveli and Daman & Diu, Lakshadweep, Andaman & Nicobar Islands, Chandigarh). It functions exactly like SGST but for UTs. Delhi and Puducherry — which have legislatures — use SGST.
Input Tax Credit (ITC)
The anti-cascading feature of GST. Businesses can claim credit for the GST paid on inputs (raw materials, services) and set it off against their output GST liability. This eliminates the “tax on tax” problem that plagued the old regime. CGST credit can offset CGST and IGST. SGST credit can offset SGST and IGST. IGST credit can offset IGST, CGST, and SGST — in that order.
GST Rate Slabs: The Tiered Structure
GST operates on a multi-rate structure, not a single rate. The GST Council decides which goods and services go in which slab.
| Rate | Category | Examples |
|---|---|---|
| 0% (Exempt) | Essential items | Fresh vegetables, milk, eggs, unprocessed cereals, books, newspapers, salt |
| 5% | Basic necessities | Packaged food, life-saving drugs, footwear under ₹1000, transport services |
| 12% | Standard goods | Processed food, smartphones, computers, business-class air travel |
| 18% | Most services, many goods | Restaurant services, IT services, financial services, most manufactured goods |
| 28% | Luxury & sin goods | Cars, cigarettes, aerated beverages, cement, air conditioners |
A small category of items also attracts a Compensation Cess over and above the 28% rate — luxury cars, tobacco products, aerated drinks. This cess funded compensation to states for GST-related revenue losses.
The Compensation Cess Issue
When GST was introduced, states feared revenue loss from subsuming their taxes. The Centre promised to compensate states for 5 years (till June 2022) for any shortfall below a guaranteed 14% annual revenue growth baseline. The compensation came from a cess levied on luxury and demerit goods.
COVID-19 devastated GST revenues in 2020-21. The Centre couldn’t fully pay compensation, leading to a major Centre-state dispute. States were given the option to borrow from the market backed by the Centre’s guarantee. The compensation cess was extended beyond June 2022 — till March 2026 — to repay the back-loaded borrowings. This episode exposed a structural weakness in the GST federal compact.
The GST Council: Constitutional Federal Body
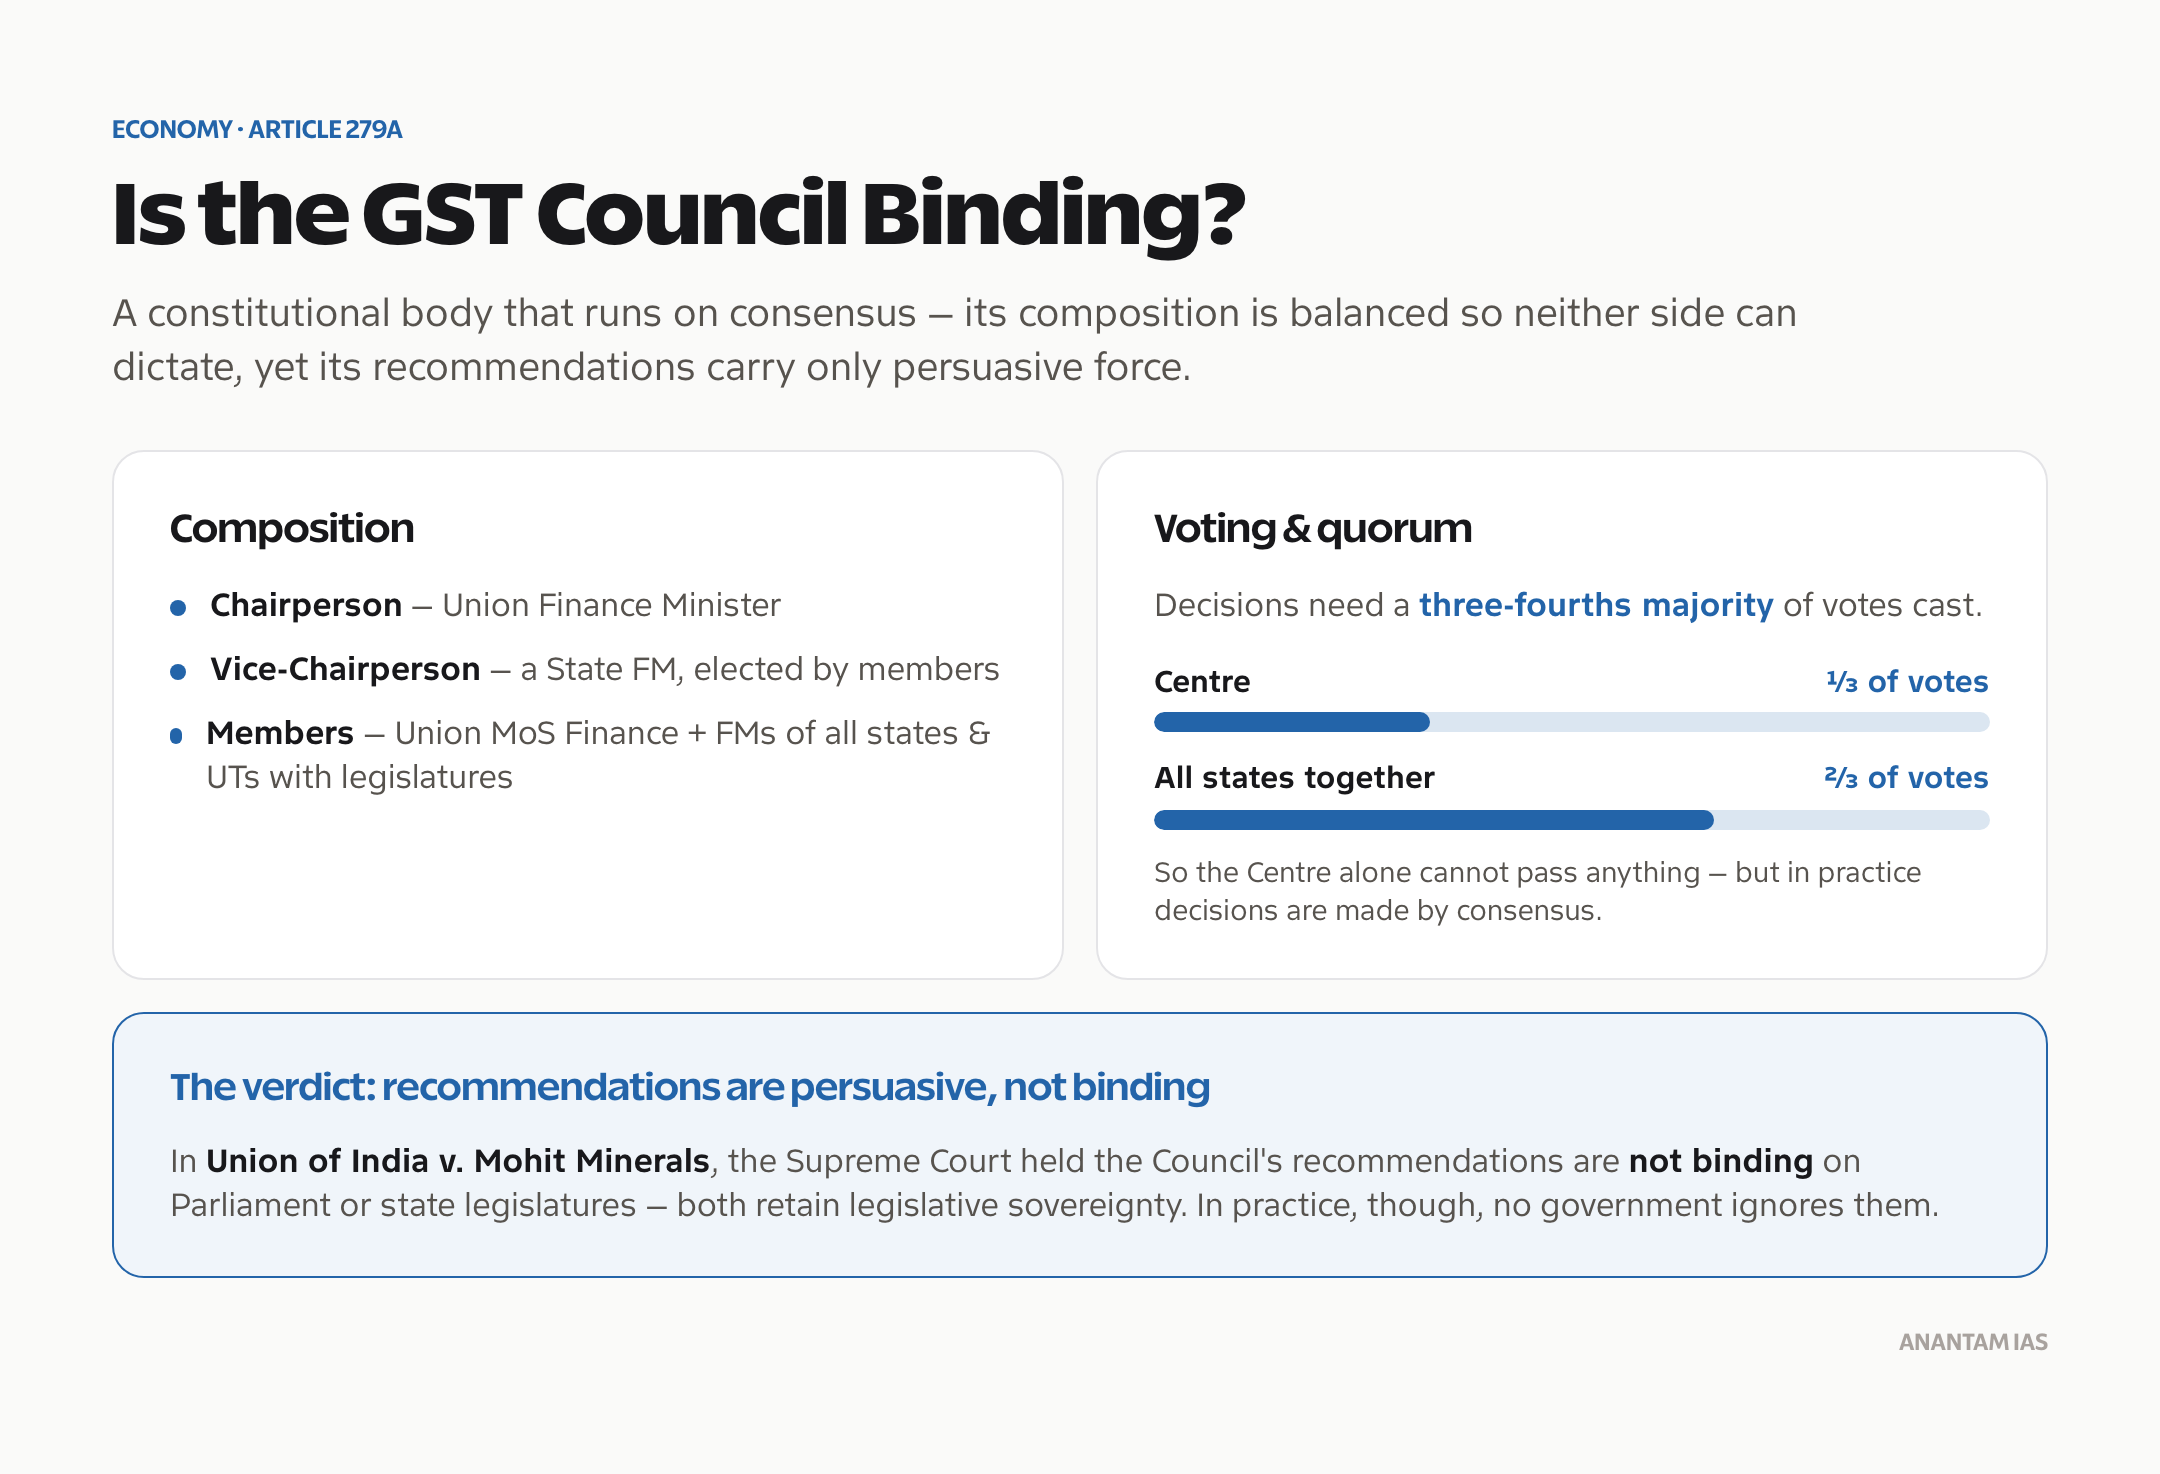
The GST Council (Article 279A) is the apex decision-making body for GST. It’s a constitutional innovation — a permanent inter-governmental body that runs on consensus.
Composition
- Chairperson: Union Finance Minister
- Vice Chairperson: State Finance Minister (elected by members)
- Members: Union Minister of State for Finance + Finance Ministers of all states and UTs with legislatures
Voting and Quorum
Decisions need a three-fourths majority of votes cast. Voting weights:
- Centre’s vote = one-third of total votes cast
- All states together = two-thirds of total votes cast
So the Centre alone cannot pass anything — states collectively have more weight. But practically, decisions are made by consensus, not by voting.
Functions
The GST Council recommends:
- Taxes, cesses, surcharges to be subsumed
- Goods and services exempt from GST
- GST rate slabs and thresholds
- Model GST laws, principles of apportionment, dispute resolution
- Special provisions for Northeast states, hill states, Jammu & Kashmir
Is the GST Council’s Recommendation Binding?
This became a live constitutional question in Union of India v. Mohit Minerals (2022). The Supreme Court held that the recommendations of the GST Council are not binding on Parliament or state legislatures — they are merely persuasive. The Centre and states retain their legislative sovereignty. In practice, though, no government ignores Council recommendations.
Impact on Indian Federalism
GST fundamentally altered Centre-state fiscal relations — for better and worse.
Arguments That GST Strengthened Cooperative Federalism
- Created the GST Council — a permanent, constitutional platform for Centre-state dialogue
- States gained taxation power over services (which they didn’t have before)
- The destination-based principle benefits consuming states (largely poorer ones)
- The Council has worked largely by consensus, setting a precedent for cooperative decision-making
Arguments That GST Weakened State Autonomy
- States surrendered their independent VAT and sales tax — a core fiscal instrument
- The Centre sets the floor of taxation; states can’t compete on tax rates to attract business
- Revenue autonomy of states has declined — they depend on Centre for IGST settlements
- The compensation mechanism was Centre-controlled, leading to disputes
- Alcohol and petroleum carve-outs are politically motivated, not principled — they preserve state autonomy only selectively
The Finance Commission has noted that GST has made state revenues more volatile and pro-cyclical, since they now move with consumption patterns rather than stable tax bases.
E-Way Bill: The Compliance Backbone
The e-way bill is an electronic document required for movement of goods worth more than ₹50,000 across state borders (and in most states, within states too). It’s generated on the GST Network (GSTN) — the IT backbone of GST — before goods are transported.
Why It Matters
- Replaced the old system of state-level check posts and entry taxes
- Eliminated the notorious truck queues at state borders that cost billions in logistics inefficiency
- Enables real-time tracking and reduces tax evasion
- Logistics costs fell post-GST partly because inter-state movement became faster
The e-way bill was introduced nationally from April 2018 after initial delays.
GSTN — The Technology Layer
The Goods and Services Tax Network is a non-government, not-for-profit company that runs the GST portal. It processes returns, payments, and e-way bills. The government holds 49% and private financial institutions hold 51% — though effective control is with the government. The GSTN has faced criticism for technical glitches in the initial rollout.
GST Revenue Performance: Key Data
| Year | GST Revenue (₹ Crore) | Monthly Average |
|---|---|---|
| 2017-18 (Jul-Mar) | ~7.19 lakh | ~80,000 |
| 2019-20 | 12.22 lakh | ~1.02 lakh |
| 2020-21 | 11.36 lakh | ~94,700 (COVID impact) |
| 2021-22 | 14.83 lakh | ~1.24 lakh |
| 2022-23 | 18.10 lakh | ~1.51 lakh |
| 2023-24 | 20.18 lakh | ~1.68 lakh |
The ₹2 lakh crore monthly milestone was breached for the first time in April 2024. GST revenues have grown substantially, vindicating the reform’s potential — though compliance gaps remain.
Key Differences: Pre-GST vs Post-GST
| Parameter | Pre-GST | Post-GST |
|---|---|---|
| Tax structure | Multiple taxes, multiple rates | Unified, four broad rate slabs |
| Cascading effect | Yes (tax on tax) | No (ITC available across chain) |
| Centre-state overlap | Separate, non-overlapping | Concurrent, coordinated |
| Inter-state movement | Multiple check posts, CST | IGST + e-way bill, seamless |
| Service tax | Only Centre | Both Centre and states |
| Threshold for registration | Varied by state and tax | ₹40 lakh turnover (₹20 lakh for services) |
| Compliance | Multiple returns, multiple portals | Single GSTN portal |
Issues and Challenges with GST
Compliance burden on MSMEs: Small businesses — especially those without digital infrastructure — found the transition to monthly GSTR-1, GSTR-3B, and annual GSTR-9 returns burdensome. Multiple return format changes added confusion.
Rate rationalisation is incomplete: The rate structure has more than four slabs in practice (0%, 0.25%, 3%, 5%, 12%, 18%, 28% plus cess). The inverted duty structure — where input rates exceed output rates — creates refund backlogs and cash flow problems in sectors like textiles.
Exclusion of petroleum and alcohol: Keeping these outside GST creates an incomplete single market. States are reluctant to include petroleum because it’s their biggest revenue source. But industries can’t claim ITC on fuel costs, raising their production costs.
IGST settlement delays: Disputes between Centre and states over IGST apportionment have occurred, with states complaining of delayed settlements.
Fake ITC fraud: Criminal networks have exploited the ITC mechanism by generating fake invoices to claim fraudulent input tax credits. The government estimates thousands of crores have been lost to such fraud.
Frequently Asked Questions
101st Constitutional Amendment Act, 2016 introduced GST by inserting Articles 246A, 269A, and 279A. It gave Parliament and state legislatures concurrent power to levy GST and created the constitutional GST Council.nn2. What is the difference between CGST, SGST, and IGST?
CGST is the Centre’s share on intra-state transactions; SGST is the state’s share on the same transaction. Together they equal the total GST rate. IGST applies to inter-state transactions and is collected entirely by the Centre, which then apportions the state’s share to the destination state.
3. Who chairs the GST Council?
The Union Finance Minister chairs the GST Council. All state Finance Ministers are members. The Centre’s vote counts for one-third; all states together count for two-thirds. Decisions need a three-fourths majority.
4. Which products are kept outside GST?
Petroleum products (crude oil, petrol, diesel, ATF, natural gas) and alcohol for human consumption are outside GST. These were kept out to protect state revenue, but their exclusion creates an incomplete unified market.
5. What is the GST compensation cess?
It’s a cess levied on luxury goods and sin goods (above the 28% rate) to fund compensation to states for revenue losses after GST implementation. States were guaranteed 14% annual revenue growth for five years. The cess was extended beyond 2022 to repay COVID-period borrowings.