India’s External Position: FCNR(B)-Led Inflows Near $32 Billion
Why in News?
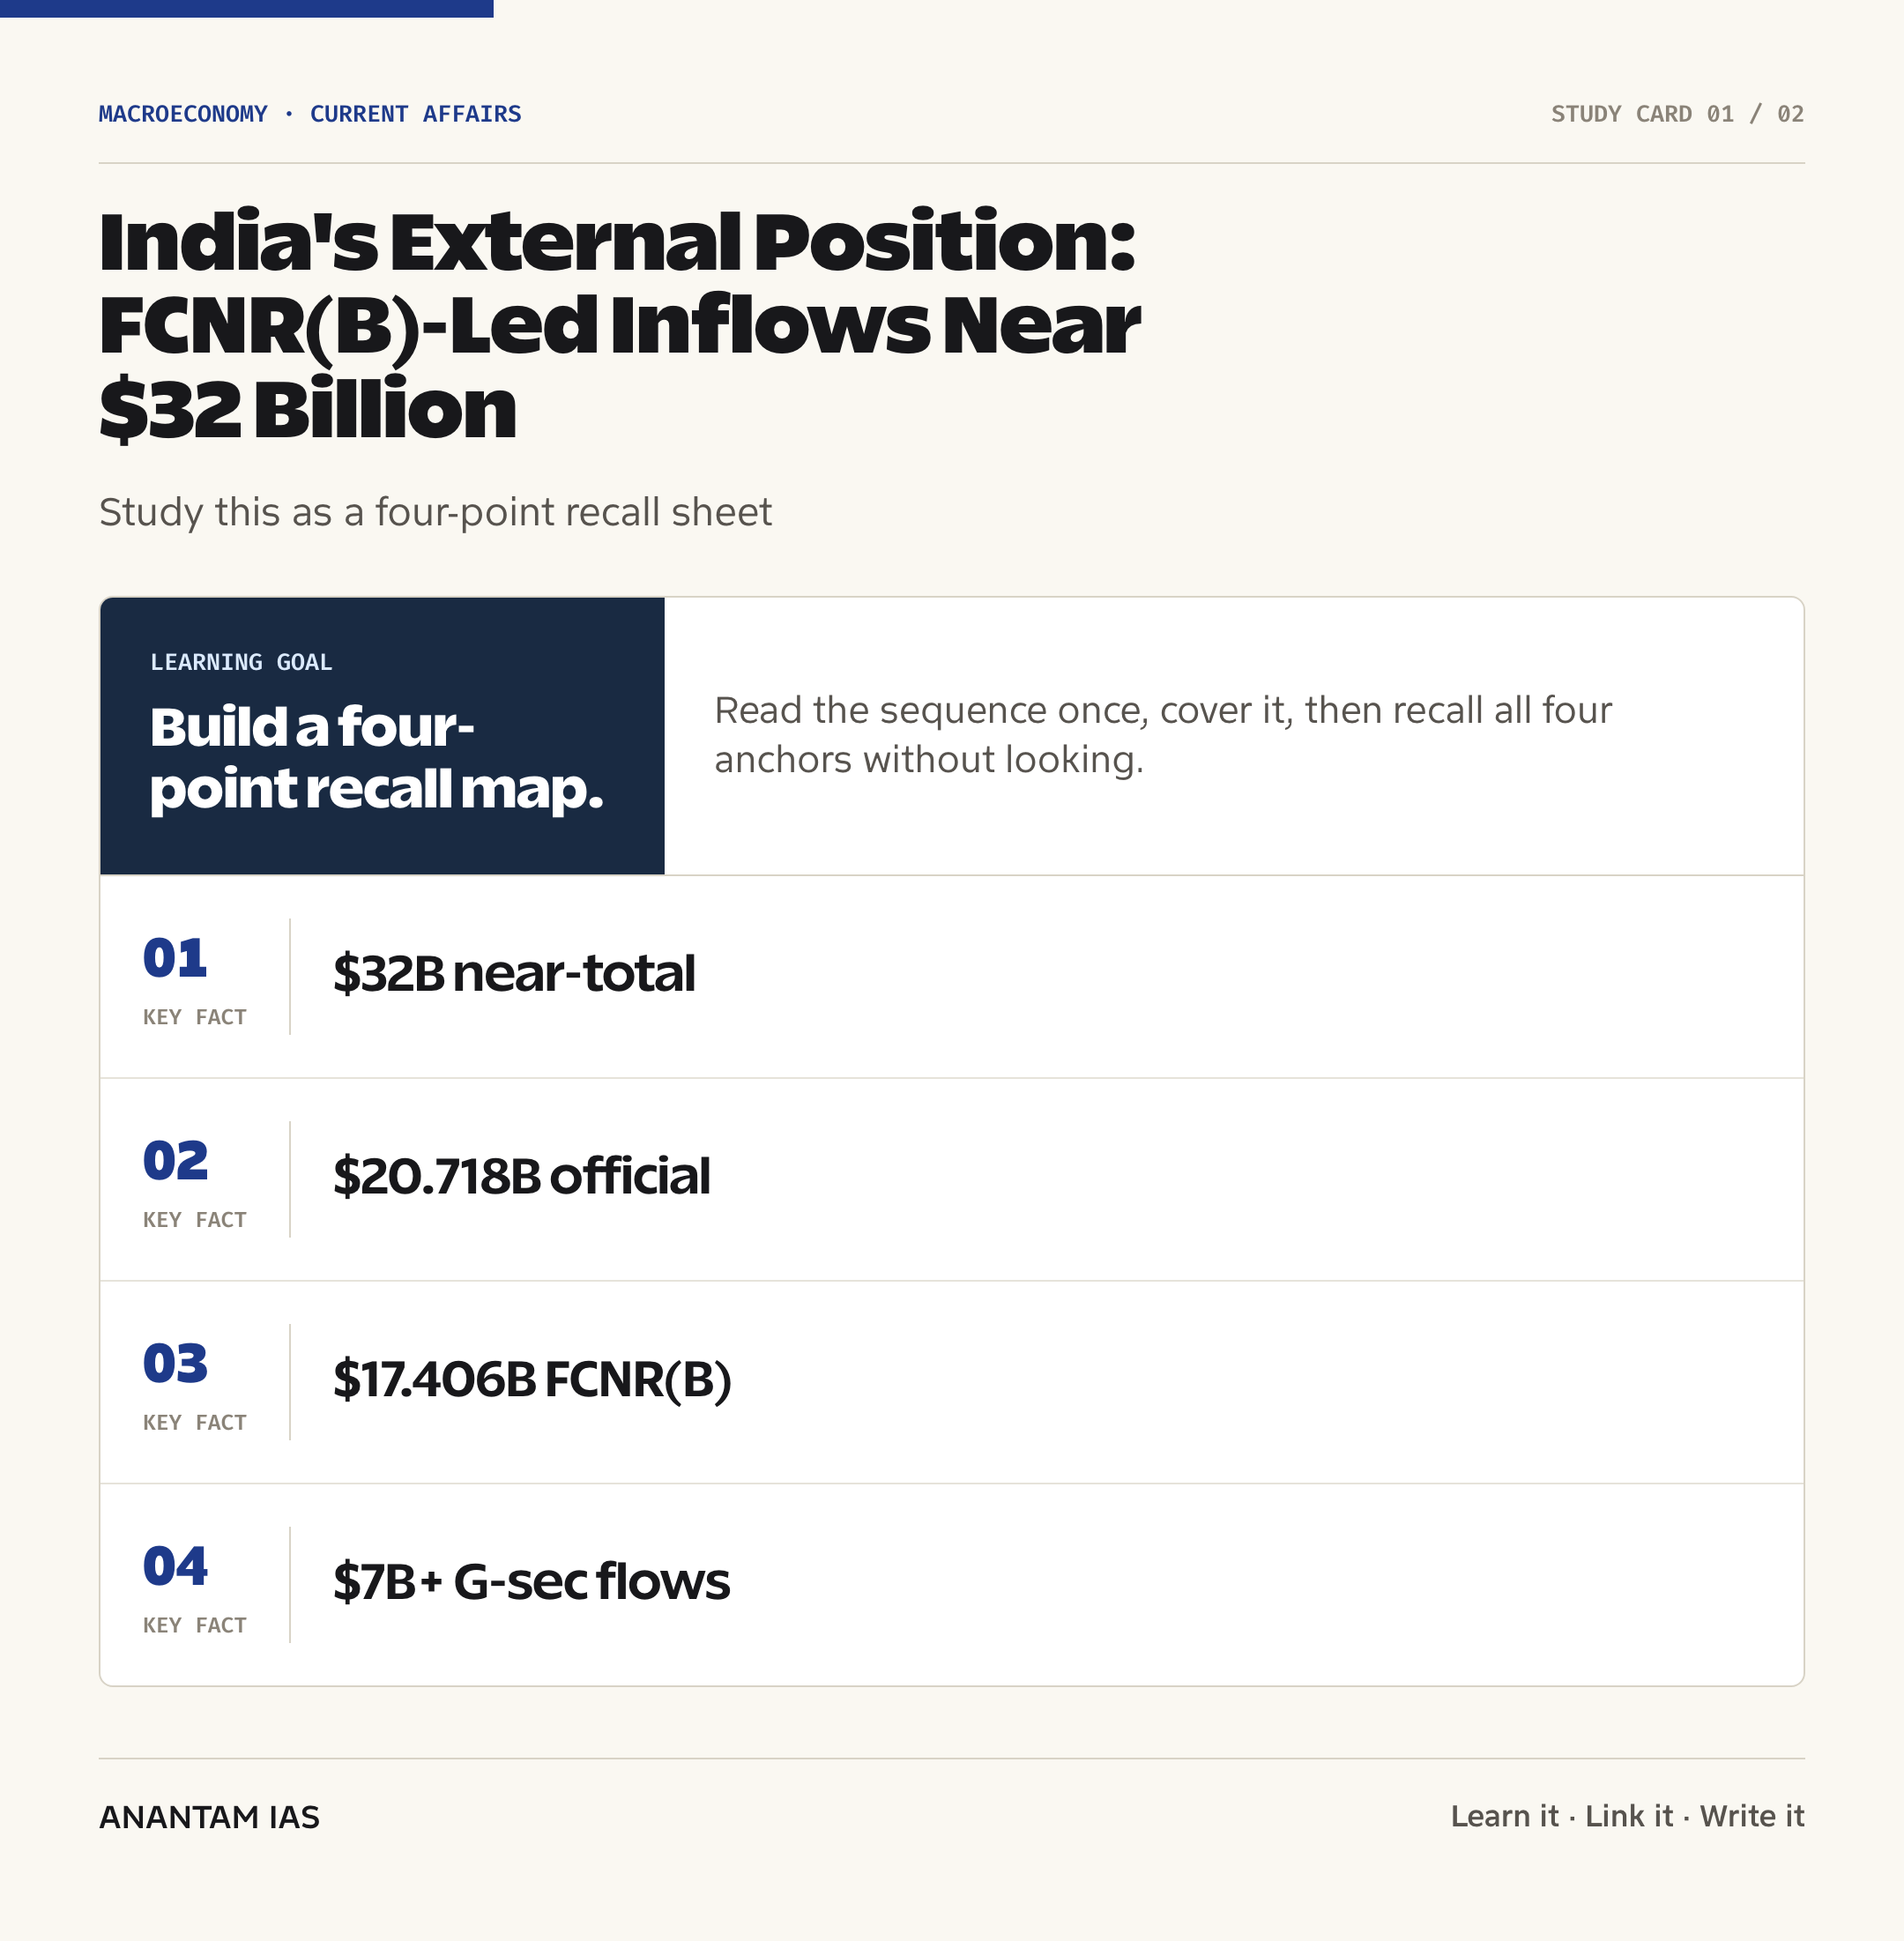
The Hindu reported on 27 July 2026 that banks had mobilised nearly $32 billion after the Reserve Bank of India’s June foreign-currency measures, with the inflow led by FCNR(B) deposits. RBI Governor Sanjay Malhotra also said foreign investment in government securities had exceeded $7 billion since those measures.
The latest interview figure extends the official interim picture. An RBI press release dated 20 July recorded $20.718 billion under its swap facilities up to 17 July: $17.406 billion in FCNR(B) deposits, $1.970 billion in overseas foreign-currency borrowings and $1.342 billion in external commercial borrowings. The different totals reflect different reporting cut-offs and scopes, so they shouldn’t be treated as contradictory like-for-like figures.
- FCNR(B) means Foreign Currency Non-Resident (Bank), a foreign-currency term deposit available to eligible non-resident Indians and persons of Indian origin.
- The RBI operationalised its special US dollar-rupee swap facilities on 8 June 2026 to attract longer-tenor foreign-currency inflows.
- The official 17 July break-up put FCNR(B) deposits at $17.406 billion, about 84% of the $20.718 billion reported under the three swap windows.
- The Governor said the broader mobilisation had reached nearly $32 billion, while government securities separately drew more than $7 billion after the June measures.
- The RBI described the rupee as possibly undervalued in nominal and real effective terms, but repeated that it targets excessive volatility rather than a fixed exchange-rate level.
The development matters in the context of:
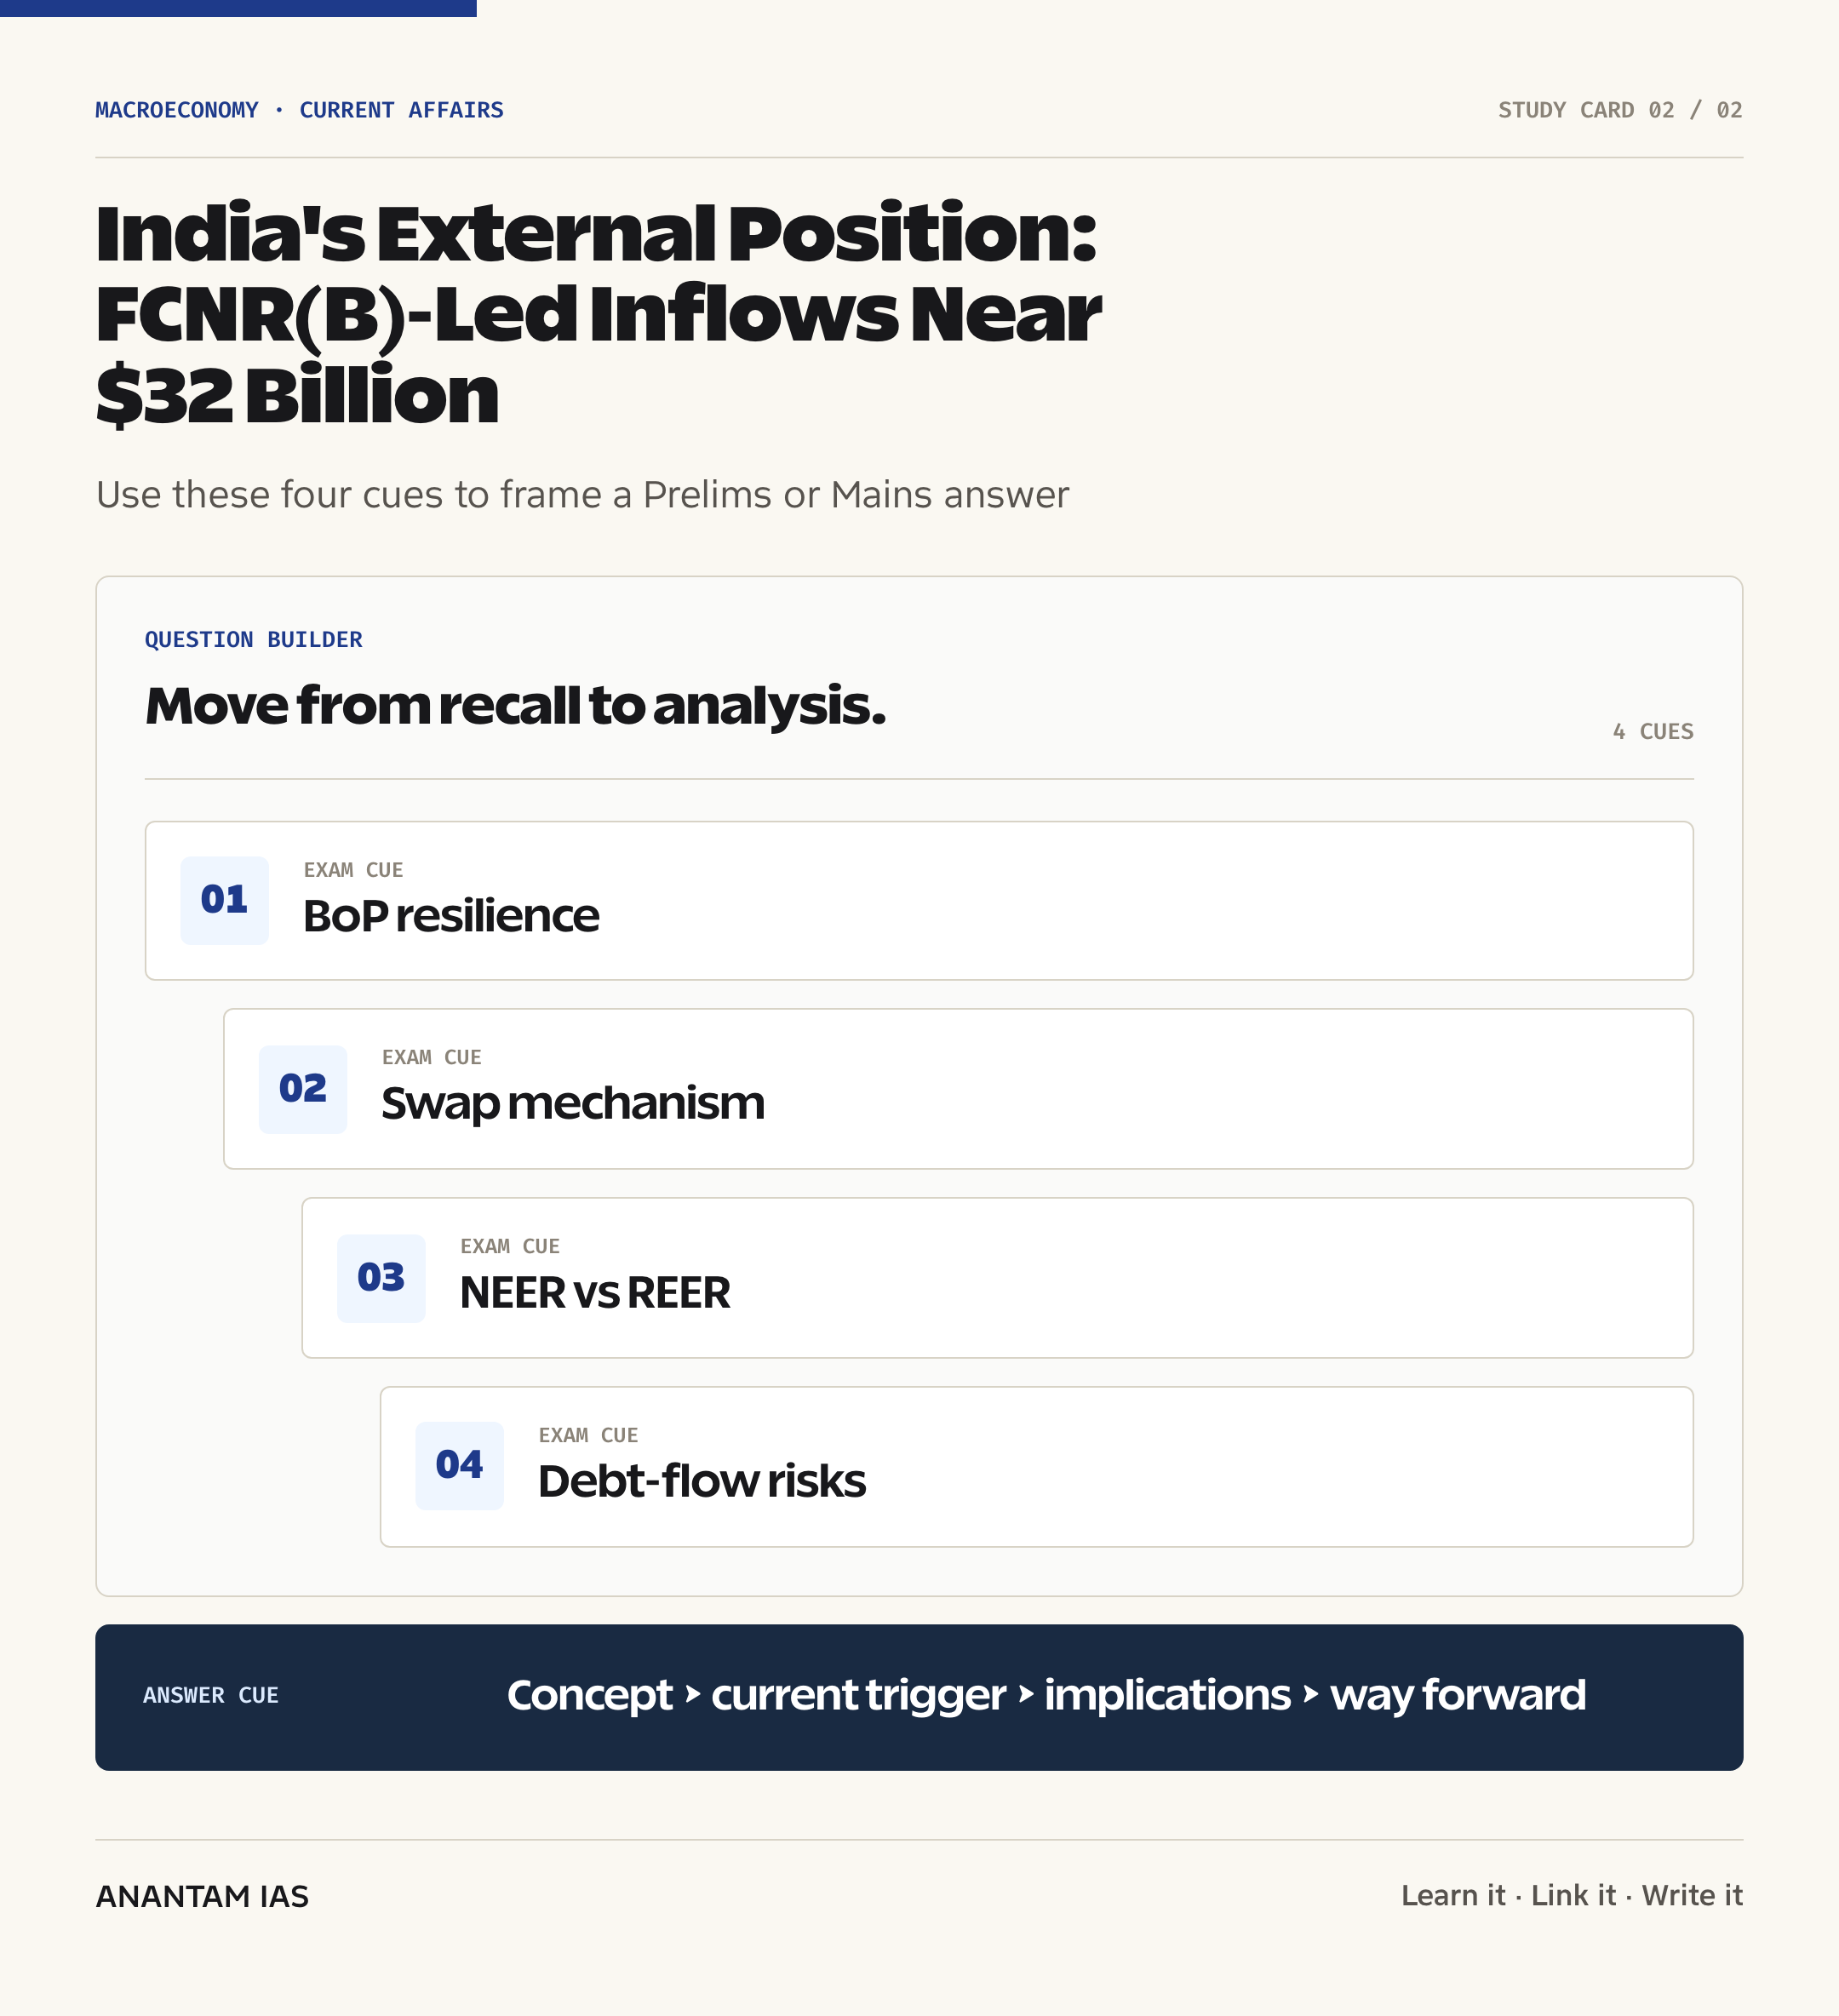
- The inflows matter in the context of balance-of-payments resilience amid geopolitical risk, dollar strength and volatile emerging-market capital flows.
- They test whether incentive-based capital-flow management can stabilise the rupee without relying only on sales of foreign-exchange reserves.
- They also expose the trade-off between an immediate forex buffer and future foreign-currency liabilities that must be repaid or rolled over.
UPSC Relevance
Prelims Relevance
- FCNR(B) accounts are maintained as term deposits in permitted foreign currencies; principal and interest are freely repatriable.
- Because the deposit is denominated in foreign currency, the depositor doesn’t bear rupee-conversion risk; the bank ordinarily manages the currency exposure.
- The 2026 facility covers fresh or eligible renewed FCNR(B) deposits with a three-to-five-year tenor; the RBI swap itself is conducted in US dollars.
- An Authorised Dealer Category-I bank can deal in all permissible current-account and capital-account foreign-exchange transactions under RBI authorisation.
- ECBs are commercial borrowings raised by eligible Indian entities from recognised non-resident lenders, while OFCBs are overseas foreign-currency borrowings raised by authorised banks.
- The balance of payments records transactions between residents and non-residents; NRI deposits, ECBs and portfolio investment create financial-account flows.
- NEER is a trade-weighted average of nominal bilateral exchange rates; REER adjusts the effective rate for relative inflation.
- Foreign-exchange reserves include foreign currency assets, gold, Special Drawing Rights and India’s reserve position in the IMF.
- RBI intervention under India’s market-determined exchange-rate system aims to curb disorderly or excessive volatility, not defend a declared parity.
Mains Relevance
GS Paper 3
- External-sector management through forex reserves, capital-flow measures and currency swaps.
- The quality of capital inflows: comparing deposits and debt with FDI, portfolio flows and current-account receipts.
- The link among the rupee, imported inflation, current account and monetary-policy choices.
GS Paper 2
- Institutional roles of the RBI, Union government and authorised dealer banks in managing cross-border finance.
- Rule-based regulation under the Foreign Exchange Management Act, 1999 and transparent disclosure of policy costs.
Essay
- Economic resilience depends not only on the size of a buffer, but also on the quality and maturity of the liabilities used to build it.
- A flexible currency can absorb shocks, but public policy must distinguish volatility management from price targeting.
Background and Context
Reading the Headline Numbers Correctly
The new headline is a later assessment, while the RBI release supplies an auditable interim benchmark.
- The RBI’s official data, collected from Authorised Dealer banks, showed $20.718 billion mobilised from 8 June through 17 July under the special swap facilities.
- Within that total, $17.406 billion came from FCNR(B) deposits, $1.970 billion from OFCBs and $1.342 billion from ECBs.
- The Hindu’s 27 July report cited the Governor’s later figure of nearly $32 billion mobilised by banks, largely through FCNR(B), but did not publish the same instrument-wise table or cut-off used in the 20 July release.
- The more than $7 billion in government securities is a separate portfolio-flow indicator. It shouldn’t be added mechanically to an unlike total without matching dates and coverage.
- For answer writing, use the official break-up as the verified baseline and describe the $32 billion figure as the Governor’s updated assessment.
What an FCNR(B) Deposit Does
FCNR(B) converts diaspora savings into a relatively stable foreign-currency liability for an Indian bank.
- Eligible non-residents place a fixed-term deposit in a permitted foreign currency rather than converting the money into rupees.
- Both principal and interest are repatriable, and the depositor is protected from a fall in the rupee because repayment remains in the designated currency.
- The bank must still manage the mismatch between its foreign-currency liability and the rupee or foreign-currency assets funded with those deposits.
- FCNR(B) differs from an NRE account, which is rupee-denominated and exposes the depositor to the rupee’s exchange value when money is converted back.
- The durable static concept is covered in Anantam IAS’s note on the FCNR(B) swap window and NRI deposit rates.
How the RBI Swap Facility Works
The swap lowers the cost of hedging eligible inflows and gives banks a reason to mobilise longer-tenor dollars.
- A participating bank delivers eligible foreign currency and receives rupees from the RBI, with a reverse exchange agreed for the end of the swap tenor.
- For FCNR(B), the underlying deposit must generally have a minimum tenor of three years and maximum tenor of five years; the swap tenor follows the deposit.
- The facility was operationalised on 8 June 2026. The FCNR(B) mobilisation window remains available up to 30 September, while the ECB and OFCB windows extend to 31 December.
- For eligible ECBs and OFCBs, the June Economic Review of the Department of Economic Affairs recorded a concessional swap rate of 1.5% a year, compounded half-yearly.
- The mechanism transfers or reduces a major hedging-cost constraint; it doesn’t erase the public-sector risk associated with future exchange-rate movements.
- A prior explainer on RBI hedging support for FCNR(B) deposits sets out the policy design and the 2013 precedent.
The 2013 Precedent and the 2026 Difference
India has used an FCNR(B) swap window before, but precedent should guide risk assessment rather than encourage mechanical comparison.
- During the 2013 taper tantrum, expectations of tighter US monetary policy triggered capital outflows, rupee depreciation and wider concern about India’s current-account financing.
- The RBI offered banks a concessional swap against fresh three-to-five-year FCNR(B) deposits and also supported overseas borrowings by banks.
- RBI’s published account says the two 2013 windows mobilised about $34 billion, adding dollar resources and helping restore market confidence.
- The 2026 package again uses longer-tenor diaspora deposits, but it also covers eligible ECBs and OFCBs and sits beside measures designed to attract government-security investment.
- The shock context differs: 2013 centred on US taper expectations and India’s then-large current-account deficit, while 2026 combines geopolitical risk, dollar strength and volatile capital flows.
- The lesson is conditional: a swap window can break a cycle of panic and thin forex liquidity, but successful mobilisation doesn’t prove that the underlying trade or energy imbalance has disappeared.
Why the Inflows Strengthen the External Position
Fresh foreign currency improves near-term financing capacity even though the underlying instruments remain liabilities.
- A larger supply of dollars can ease pressure in the foreign-exchange market and reduce the need for abrupt reserve sales during global risk-off episodes.
- Longer-tenor deposits and borrowings offer more stability than very short-term speculative flows, helping the RBI manage liquidity and maturity risk.
- Capital inflows help finance a current-account deficit when merchandise imports exceed receipts from exports, services, remittances and income.
- The accounting relationship is explained in Anantam IAS’s guide to the balance of payments, current account and capital flows.
- The Governor also pointed to a current-account surplus during April-May, strong services exports and remittances, rising merchandise exports and improving FDI as supporting indicators.
- But a deposit inflow doesn’t improve export competitiveness by itself. It provides financing time while structural measures address trade, energy and productivity constraints.
Rupee Valuation and the RBI's Mandate
A currency can weaken against the dollar even when broader effective-rate measures and domestic fundamentals tell a more qualified story.
- NEER aggregates bilateral nominal exchange rates using trade weights, so it is broader than the rupee-dollar rate alone.
- REER adjusts the effective nominal rate for inflation differences between India and its trading partners and is often used as an indicator of external competitiveness.
- The Governor said the rupee was not overvalued and could be undervalued in nominal and real effective terms, linking recent pressure to geopolitics, dollar strength and emerging-market volatility.
- An undervaluation claim is sensitive to the base year, currency basket, trade weights and price indices; it isn’t a permanent or exact fair-value verdict.
- India follows a market-determined exchange rate. RBI operations seek orderly conditions and curb excessive volatility rather than promise a fixed level or band.
- This distinction preserves some monetary-policy autonomy: trying to fix the exchange rate, keep capital fully mobile and run an independent monetary policy creates the impossible trinity constraint.
Government-Security Inflows and the Broader Package
Portfolio demand for government debt broadens the inflow mix, but it behaves differently from an NRI term deposit.
- The Governor reported more than $7 billion of foreign inflows into government securities following the June policy measures.
- The June package included a tax exemption on interest and capital gains from eligible foreign portfolio investment in government securities with effect from 1 April 2026.
- Foreign purchases can deepen the government-securities market, diversify the investor base and reduce pressure on domestic financing costs.
- Portfolio debt is marked to market and can reverse when global yields, risk appetite or the dollar change; FCNR(B) deposits have a contractual term but create a maturity repayment.
- A stronger external account needs a balanced mix of FDI, portfolio flows, external debt, remittances and export earnings, not dependence on a single window.
Benefits, Costs and Warning Signs
The policy is best judged as a bridge against volatility, not as a substitute for external-sector reform.
- The immediate benefit is a larger forex liquidity cushion, improved market confidence and less pressure to use reserves defensively.
- The three-to-five-year FCNR(B) tenor reduces instant reversal risk, but concentrated maturities can create a redemption hump when deposits fall due.
- Higher deposit rates and subsidised or concessional hedging can shift costs to bank margins or the RBI balance sheet, depending on the instrument’s terms.
- Sterilising large inflows may be necessary if the rupee liquidity created by swaps conflicts with inflation control or short-term liquidity conditions.
- Debt-creating inflows improve financing but also increase future payment obligations. FDI and export earnings usually provide a more durable foundation.
- The strongest success test is not a one-day rupee level; it is whether reserve adequacy, maturity structure and the current account remain manageable after the special windows close.
Interaction with Inflation and Monetary Policy
Forex support and domestic price stability are connected through the rupee-liquidity and imported-inflation channels.
- A weaker rupee raises the domestic-currency cost of imported crude oil, fertiliser, electronics and intermediate goods, creating imported inflation even when domestic demand is moderate.
- Attracting dollars can calm abrupt currency moves, but when the RBI buys foreign currency it releases rupee liquidity into the banking system.
- If that liquidity is excessive, the RBI can absorb it through variable-rate reverse repos, deposit facilities or securities operations. This process is called sterilisation.
- Sterilisation has a cost and may affect money-market rates, bond yields and bank liquidity. The external-sector operation must remain aligned with the Monetary Policy Committee’s inflation mandate.
- The Governor said price stability remains the foremost priority and described the policy stance as data-dependent, allowing decisions to respond to domestic growth and inflation rather than copy foreign central banks.
- For analysis, separate three choices: attracting capital to improve forex supply, intervening to smooth volatility and setting the policy repo rate to meet the inflation objective.
Way Forward
Publish Comparable Data
- RBI should continue releasing instrument-wise, cut-off-specific figures so markets can distinguish FCNR(B), ECB, OFCB and government-security flows.
- Disclosures should show tenor buckets and future maturity concentrations without compromising bank-level confidentiality.
Manage Liquidity and Risk
- Use calibrated sterilisation operations when swap-generated rupee liquidity threatens monetary-policy alignment.
- Stress-test banks and the central bank balance sheet for exchange-rate, rollover and interest-rate shocks before the deposits mature.
Improve the Quality of Inflows
- Pair temporary deposit incentives with stable rules for FDI, bond-market access and long-term institutional investment.
- Avoid repeated exceptional windows becoming an assumed public hedge for private foreign-currency liabilities.
Repair Structural External Gaps
- Lower oil-import vulnerability through energy efficiency, diversified supplies and domestic clean-energy capacity.
- Raise export competitiveness through logistics, standards, services depth and productive capacity, rather than relying on currency weakness.
Keep the Exchange Rate Flexible
- Intervene against disorderly moves while allowing the rupee to reflect inflation, productivity and external demand over time.
- Explain NEER and REER assessments with their methodology so an undervaluation observation isn’t misread as an exchange-rate target.
Conclusion
FCNR(B)-led mobilisation has given India a meaningful near-term external buffer. The official $20.718 billion interim break-up and the Governor’s later nearly $32 billion assessment together show strong demand for the June measures, while government-security inflows broaden the support.
But resilience can’t be measured by gross inflows alone. A sound assessment must track cost, maturity, reversibility and the current account. The swap window can buy stability; exports, productive FDI, energy security and credible macroeconomic policy must convert that time into durable strength.
UPSC Practice Questions
Prelims MCQ 1
With reference to Foreign Currency Non-Resident (Bank) deposits, consider the following statements:
- They are maintained as term deposits in permitted foreign currencies.
- The depositor bears the risk of rupee depreciation because repayment is made only in rupees.
- Principal and interest are repatriable subject to the applicable scheme.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 1 and 3 are correct. FCNR(B) deposits remain denominated and repayable in the designated foreign currency, so the depositor doesn’t carry rupee-conversion risk. The bank manages the currency exposure.
Prelims MCQ 2
Which one of the following best distinguishes REER from NEER?
(a) REER covers only the rupee-dollar rate, while NEER covers all currencies (b) REER adjusts an effective nominal exchange-rate index for relative price or inflation changes (c) REER is fixed by the government, while NEER is market determined (d) REER records capital flows, while NEER records current-account flows
Answer: (b) REER adjusts an effective nominal exchange-rate index for relative price or inflation changes
Explanation:
NEER is a weighted average of bilateral nominal exchange rates. REER adjusts that effective rate for price or inflation differentials with trading partners, making it a broader competitiveness indicator.
UPSC Mains Questions
- RBI’s FCNR(B) swap window can strengthen the balance of payments without resolving the economy’s structural current-account vulnerabilities. Explain the mechanism and critically assess the benefits, fiscal-monetary costs and future redemption risks of relying on such debt-creating inflows.
- A currency’s fall against the US dollar doesn’t by itself prove that it is overvalued or fundamentally weak. Discuss with reference to NEER, REER, capital flows, imported inflation and the Reserve Bank of India’s stated approach to exchange-rate intervention.
- Distinguish among FCNR(B) deposits, foreign portfolio investment in government securities and foreign direct investment as sources of external financing. Which mix offers India the strongest balance between immediate liquidity and long-term resilience?
Sources: Reserve Bank of India and The Hindu.
Frequently Asked Questions
What is an FCNR(B) deposit?
An FCNR(B) deposit is a fixed-term bank deposit held by an eligible non-resident in a permitted foreign currency. Principal and interest are repaid in that currency and are repatriable. Because the money isn’t converted into rupees for the deposit, the depositor is protected from rupee depreciation during the term.
How much had RBI officially recorded?
The RBI recorded $20.718 billion under the three special swap facilities from 8 June through 17 July 2026. FCNR(B) deposits contributed $17.406 billion, overseas foreign-currency borrowings $1.970 billion and external commercial borrowings $1.342 billion. This is the official instrument-wise interim benchmark.
Why does the latest report say $32 billion?
The nearly $32 billion figure came from the RBI Governor’s later assessment reported on 27 July and covered mobilisation led by FCNR(B) deposits. The RBI’s $20.718 billion table had an earlier 17 July cut-off and a defined swap-facility scope. The figures should be cited with their dates and coverage.
How does a forex swap help banks?
A swap lets a bank exchange incoming foreign currency for rupees and reverse the exchange later on agreed terms. It reduces uncertainty or cost around hedging the bank’s foreign-currency liability. That makes longer-tenor FCNR(B) deposits and eligible overseas borrowings more attractive to mobilise.
Does RBI target a fixed rupee value?
No. India has a market-determined exchange rate, and the RBI says its intervention is intended to curb excessive or disorderly volatility rather than defend a declared rate or band. It may buy or sell foreign currency and manage liquidity, but market conditions and fundamentals still influence the rupee.
Are large inflows always beneficial?
No. Inflows add forex liquidity and can support confidence, but deposits, portfolio debt and external borrowings may reverse or require repayment. Their interest and hedging costs also matter. Durable external strength needs manageable maturities, adequate reserves, productive FDI, competitive exports and a sustainable current account.