Why in News?
On June 17, 2026, the Reserve Bank of India (RBI) issued Amendment Directions temporarily withdrawing the interest-rate ceilings on fresh FCNR(B) and NRE deposits, letting banks pay sharply higher rates to Non-Resident Indians (NRIs) and Persons of Indian Origin (PIOs) to mobilise foreign exchange.
The relaxation, the central bank said, is meant to swell foreign exchange reserves, support a depreciating rupee and ease balance-of-payments pressures, and runs only till September 30, 2026.
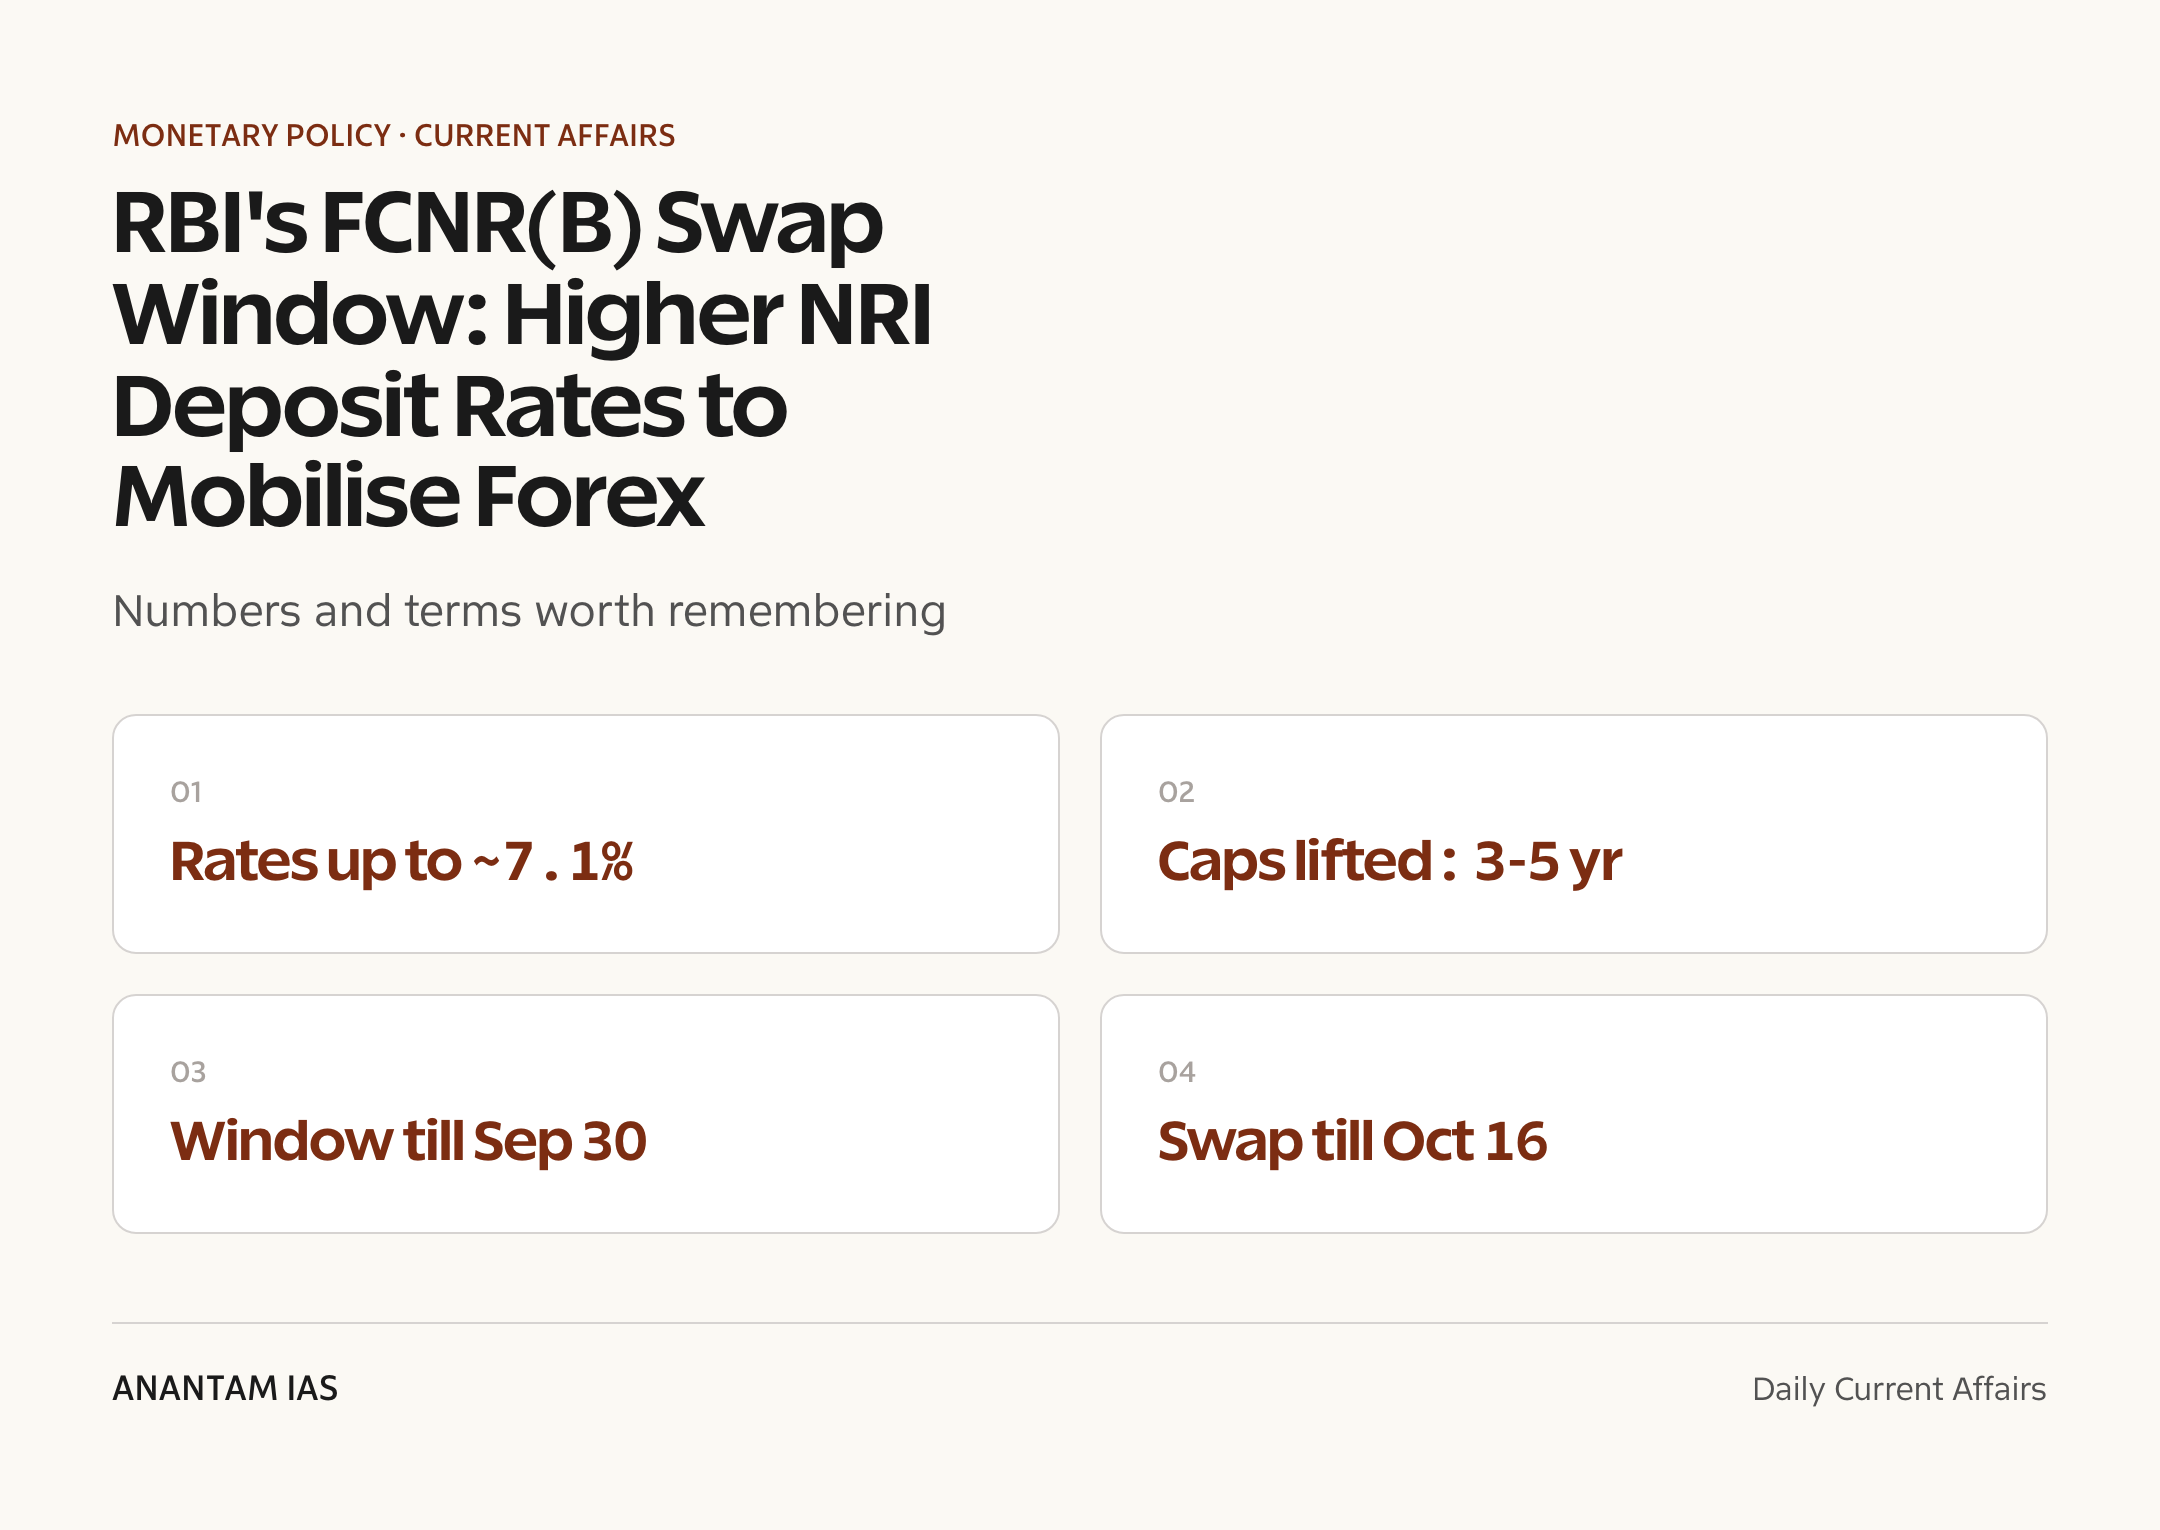
- Ceiling lifted on fresh FCNR(B) deposits of 3-5 year tenors and NRE deposits of 3 years and above, including renewals on maturity, effective June 17, 2026.
- Headline rates on NRI dollar deposits have climbed to about 7.1% (AU Small Finance Bank offered 7.10% on 3-4 year USD FCNR(B)).
- Ceilings are benchmarked to the Overnight Alternative Reference Rate (ARR) for the currency plus 250 bps (1 to under 3 years) and plus 350 bps (3 to 5 years) — and these caps now stand withdrawn for the eligible tenors.
- A linked RBI dollar-rupee swap window lets banks swap eligible dollar deposits with the RBI and buy them back at maturity, cutting their hedging cost; the swap facility is open till October 16, 2026.
- NRE/NRO rupee-deposit rates still cannot exceed comparable domestic rupee term-deposit rates; transfers from NRO to NRE accounts do not qualify for the relaxation.
- The relaxation covers both commercial banks and small finance banks.
The development matters in the context of:
- Sits within RBI’s toolkit for capital-flow management and exchange-rate defence under a managed-float regime.
- Echoes the 2013 ‘taper tantrum’ response, when a concessional FCNR(B) swap window mobilised about $34 billion to stabilise the rupee.
UPSC Relevance
Prelims Relevance
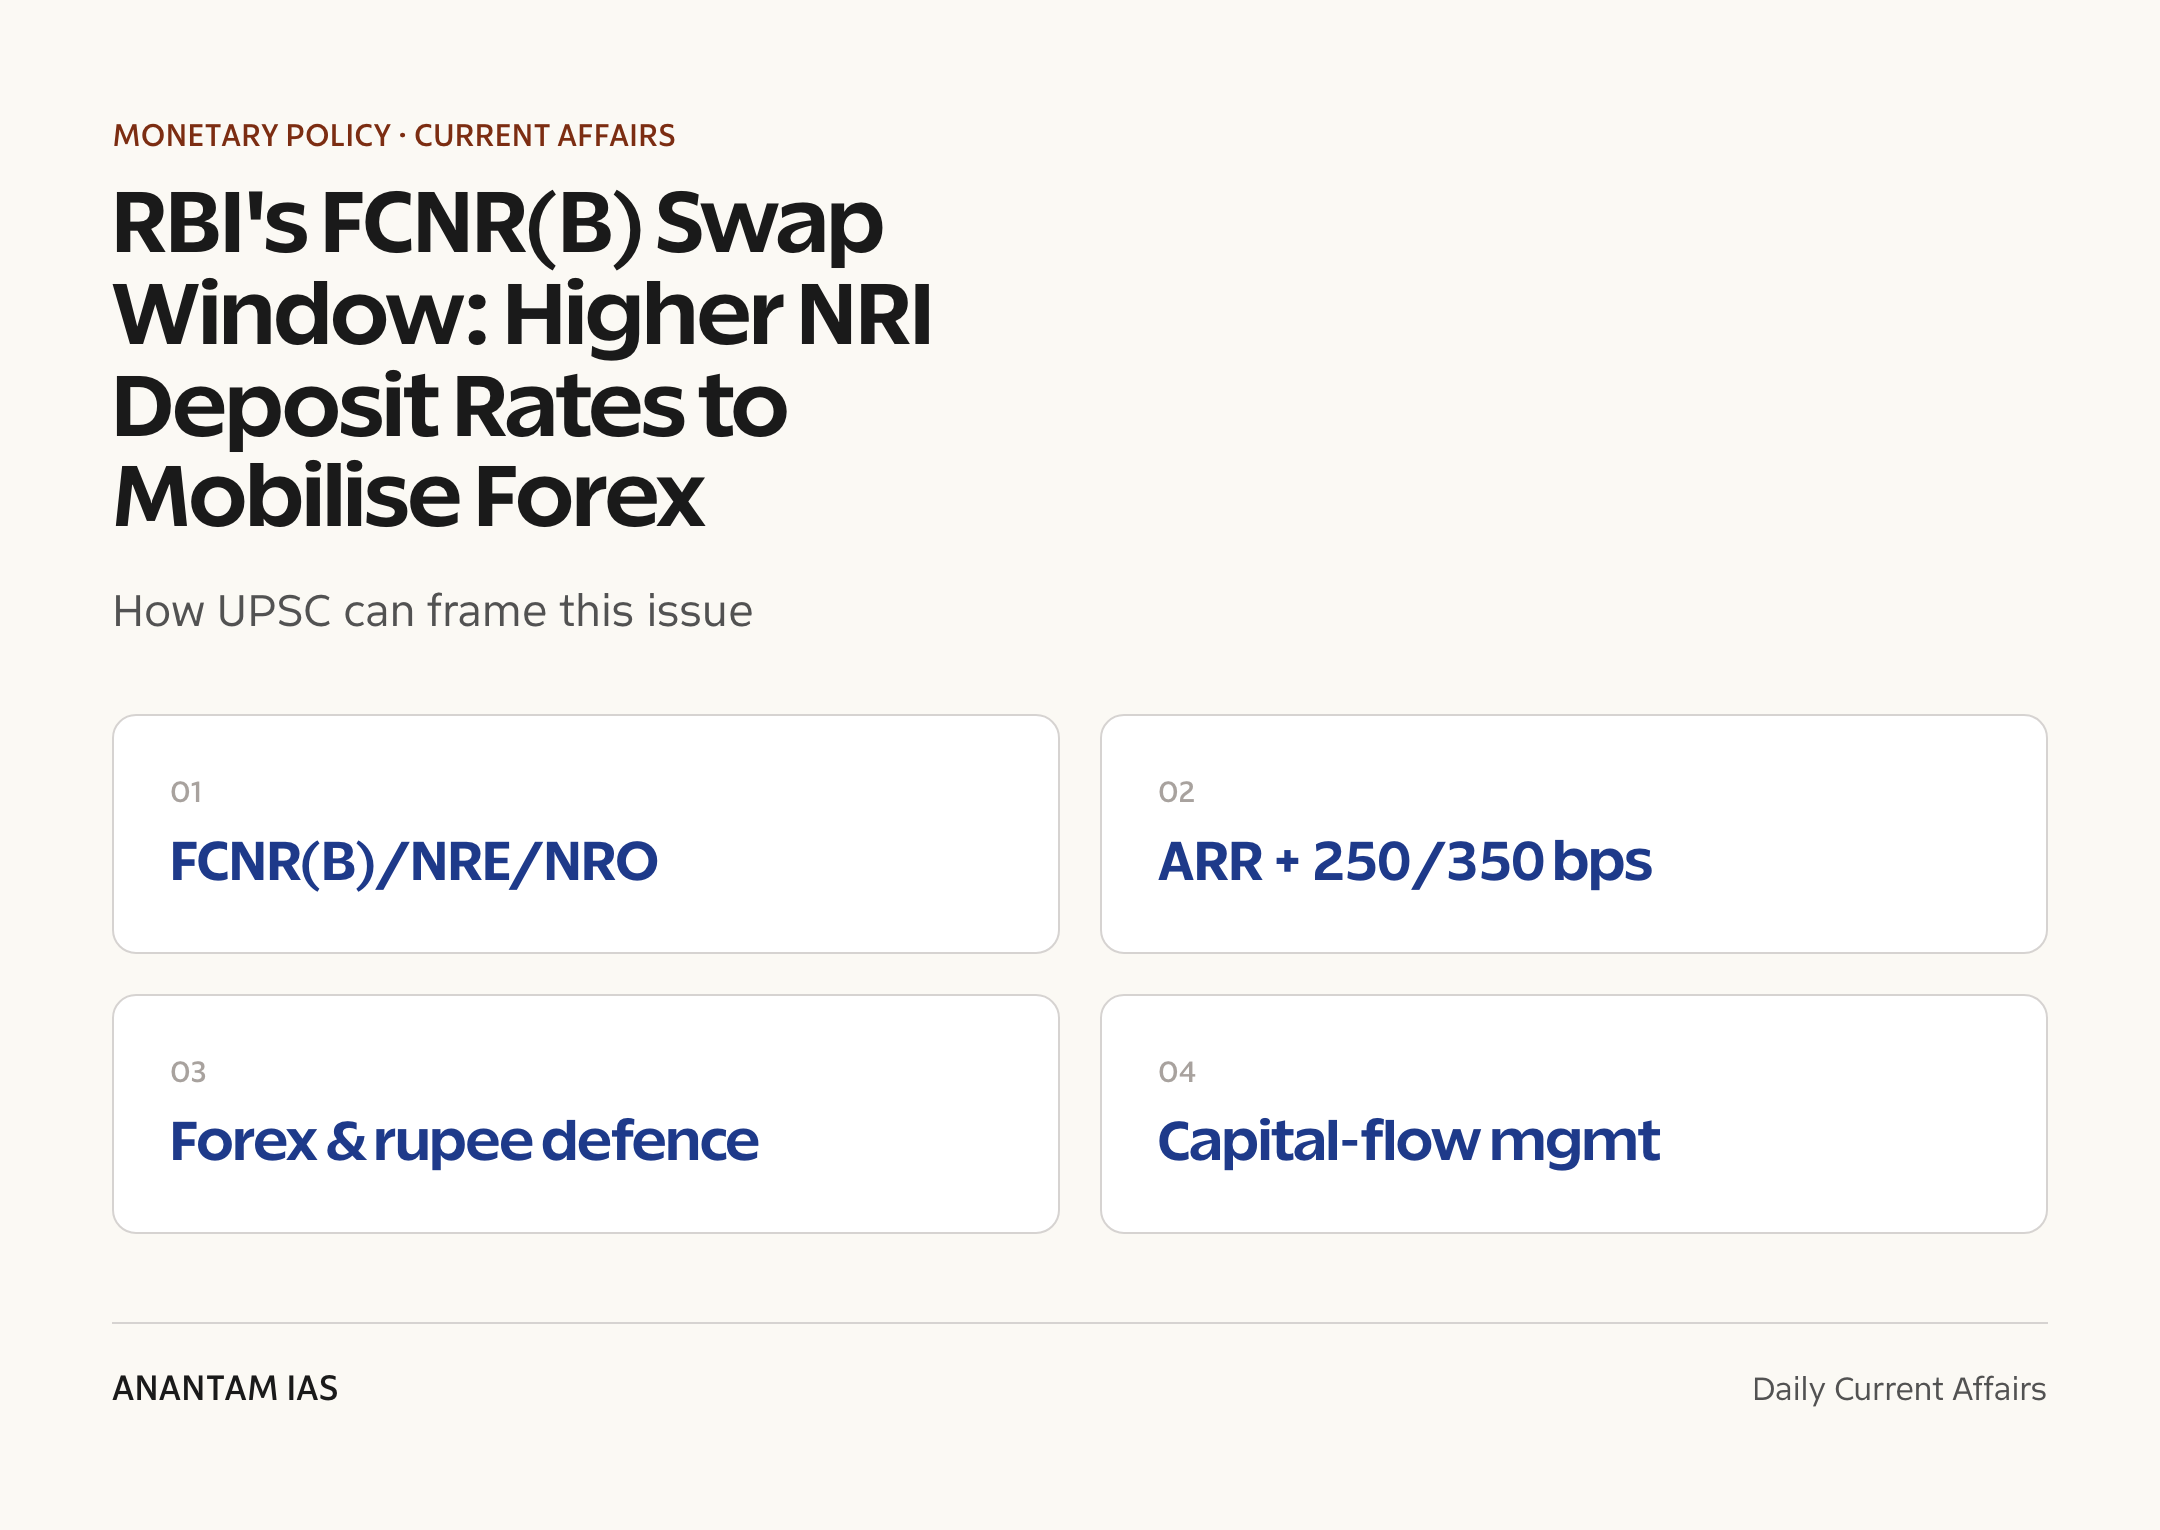
- FCNR(B) = Foreign Currency Non-Resident (Bank) — a foreign-currency-denominated NRI deposit, so the bank (not the depositor) bears the exchange-rate risk.
- NRE (Non-Resident External) account — rupee-denominated, freely repatriable principal and interest, interest tax-free in India.
- NRO (Non-Resident Ordinary) account — rupee account for income earned in India; interest taxable, repatriation capped (up to USD 1 million/financial year).
- Overnight Alternative Reference Rate (ARR) replaced LIBOR as the benchmark; e.g. SOFR for the US dollar.
- Basis point (bps) = 0.01 percentage point; 250 bps = 2.5%, 350 bps = 3.5%.
- A currency swap exchanges principal/interest in two currencies, with a reverse exchange at maturity at a pre-agreed rate.
- Forex reserves components: foreign currency assets, gold, SDRs, and the Reserve Tranche Position with the IMF.
- Balance of Payments (BoP) = current account + capital account; NRI deposits are a capital-account inflow.
- RBI ‘Amendment Directions’ are issued under the FEMA, 1999 framework governing NRI deposits.
- Rupee depreciation means more rupees per US dollar; reserves give RBI ammunition to sell dollars and steady it.
Mains Relevance
GS Paper 3
- Instruments for managing external-sector vulnerability — forex reserves, NRI deposits, and swap windows.
- Trade-offs of using high-cost capital-account inflows to defend the exchange rate versus letting the rupee adjust.
GS Paper 2
- RBI’s regulatory role and the use of directions under FEMA to channel diaspora savings.
Essay
- The diaspora dividend: can remittances and NRI savings be a stable cushion for a developing economy?
Background and Context
The three NRI deposit accounts, decoded
NRIs park money in India through three distinct accounts that differ on currency, tax and who carries exchange risk.
- FCNR(B) — held in foreign currency (USD, GBP, etc.); principal and interest are fully repatriable; the bank bears the currency risk, making it attractive to depositors wary of rupee swings.
- NRE — rupee account funded from abroad; fully repatriable; interest is tax-free in India; the depositor carries the rupee-conversion risk.
- NRO — rupee account for income arising in India (rent, dividends, pension); interest is taxable and repatriation is capped (up to USD 1 million per financial year).
- All three are governed under the Foreign Exchange Management Act (FEMA), 1999; only FCNR(B) and NRE qualify for the new ceiling relaxation.
What exactly changed on June 17
The RBI did not mandate higher rates — it removed the cap that had been holding them down.
- Pre-existing caps tied NRI deposit rates to the Overnight ARR plus a spread: 250 bps for 1 to under 3 years and 350 bps for 3 to 5 years.
- These ceilings are temporarily withdrawn for fresh FCNR(B) (3-5 yr) and NRE (3 yr+) deposits, including maturity renewals, only till September 30, 2026.
- Banks now have headroom to compete for diaspora dollars; The Hindu reported NRI dollar rates rising to around 7.1%.
- Guard-rails stay: NRE/NRO rupee rates must not exceed comparable domestic term-deposit rates, and NRO-to-NRE transfers are excluded to stop arbitrage.
The swap window — the real mechanism
A parallel dollar-rupee swap facility is what makes the higher rates viable for banks without exposing them to currency risk.
- A bank that raises a dollar FCNR(B) deposit can swap the dollars with the RBI for rupees at the prevailing reference rate, then buy the dollars back at the same rate when the deposit matures.
- Fixing the reverse-exchange rate removes the bank’s hedging cost, so it can pass part of the saving on as a higher deposit rate.
- The swap facility is open till October 16, 2026, slightly beyond the deposit window, so banks can hedge deposits taken up to the deadline.
- Net effect: the RBI absorbs the exchange-rate risk while the economy gains a front-loaded inflow of dollars into reserves.
Why now — rupee, reserves and the BoP
The trigger is external-sector stress, and NRI deposits are a quick, sizeable source of forex.
- A depreciating rupee raises import bills, fuels imported inflation and unsettles markets; reserves let the RBI sell dollars to slow the slide.
- Higher reserves improve import cover and the cushion for balance-of-payments obligations and external debt servicing.
- NRI deposits are a capital-account inflow that can be mobilised faster than equity or FDI, which respond slowly to incentives.
- India draws on a vast diaspora and is among the world’s largest remittance recipients, giving this lever real scale.
The 2013 playbook it echoes
This is a familiar crisis-management move with a strong precedent.
- During the 2013 ‘taper tantrum’, a sliding rupee prompted the RBI to open a concessional FCNR(B) swap window.
- That scheme mobilised roughly USD 34 billion and is widely credited with stabilising the rupee.
- The 2026 version is more measured — a temporary ceiling relaxation plus swap support, not a deeply subsidised scheme.
- It signals the RBI’s preference for incentive-based capital-flow management over blunt controls.
The trade-offs and risks
Mobilising hot money to defend the rupee carries well-known costs.
- These are short-tenor, rate-sensitive liabilities; inflows can reverse when global rates or sentiment shift, adding future redemption risk.
- Higher offshore rates raise banks’ cost of funds and, via the swap, place currency risk on the RBI’s balance sheet.
- Over-reliance on debt inflows can mask underlying weakness in the current account rather than fix it.
- It treats a symptom — the falling rupee — more than the cause, which lies in trade and competitiveness.
Way Forward
Use as a bridge, not a crutch
- Deploy the swap window as a temporary stabiliser while durable fixes — export competitiveness and import substitution — are pursued.
- Pre-plan the maturity profile so 2029-30 redemptions don’t cluster into a fresh outflow shock.
Strengthen the structural base
- Deepen FDI and stable, long-term flows that are less reversible than short-tenor deposits.
- Keep building forex reserves and diversify their composition (including gold) for resilience.
- Sustain the diaspora link through cheaper, faster remittance and deposit channels.
Conclusion
The FCNR(B) ceiling relaxation and swap window are a precise, time-bound tool: by shifting exchange-rate risk onto the RBI, they coax diaspora dollars into reserves and steady the rupee when sentiment turns.
The 2013 episode shows it works as crisis management. The lasting test, though, is whether India narrows its external imbalances so that the rupee needs less defending in the first place.
UPSC Practice Questions
Prelims MCQ 1
With reference to NRI deposit schemes in India, consider the following statements:
- In an FCNR(B) deposit, the exchange-rate risk is borne by the depositor, not the bank.
- Interest earned on NRE deposits is exempt from income tax in India.
- Repatriation of funds from an NRO account is subject to an annual limit.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statement 1 is wrong — in FCNR(B) the deposit is held in foreign currency, so the BANK bears the exchange-rate risk. Statements 2 (NRE interest is tax-free) and 3 (NRO repatriation is capped, up to USD 1 million per financial year) are correct.
Prelims MCQ 2
The RBI’s June 2026 ‘swap window’ linked to FCNR(B) deposits primarily helps banks by:
(a) Guaranteeing a minimum interest rate to depositors (b) Removing their currency-hedging cost so they can offer higher rates (c) Exempting such deposits from the cash reserve ratio permanently (d) Converting the deposits into equity capital
Answer: (b) Removing their currency-hedging cost so they can offer higher rates
Explanation:
Banks swap dollar deposits with the RBI and buy them back at the same rate at maturity, fixing the reverse-exchange rate. This removes their hedging cost, freeing room to offer NRIs higher rates while the RBI absorbs the currency risk.
UPSC Mains Questions
- Explain how the RBI uses NRI deposit schemes and a dollar-rupee swap window as instruments of capital-flow management. Discuss their effectiveness and risks in defending a depreciating rupee. (250 words)
- “Mobilising short-term diaspora deposits to shore up forex reserves treats the symptom, not the cause, of external-sector stress.” Critically examine in the context of India’s balance-of-payments management. (250 words)
Sources: Reserve Bank of India and The Hindu.
Frequently Asked Questions
What is an FCNR(B) deposit?
A Foreign Currency Non-Resident (Bank) deposit is an account in which NRIs and PIOs hold money in a foreign currency such as the US dollar, rather than in rupees. Because it stays in foreign currency, the bank bears the exchange-rate risk, and both principal and interest are fully repatriable abroad.
How is FCNR(B) different from NRE and NRO accounts?
FCNR(B) is in foreign currency; NRE and NRO are rupee accounts. NRE holds money remitted from abroad, is freely repatriable and earns tax-free interest. NRO holds income earned in India, attracts tax on interest, and has a repatriation cap of up to USD 1 million per financial year.
What did the RBI change in June 2026?
From June 17, 2026, the RBI temporarily withdrew the interest-rate ceilings on fresh FCNR(B) deposits of 3-5 years and NRE deposits of 3 years and above, including renewals. The relaxation runs till September 30, 2026, letting banks offer NRIs sharply higher rates, around 7.1%, to attract foreign exchange.
How does the dollar-rupee swap window work?
A bank that raises a dollar deposit swaps the dollars with the RBI for rupees at the current rate, and buys them back at the same rate when the deposit matures. Fixing this reverse rate removes the bank’s hedging cost, so it can pass on a higher interest rate while the RBI carries the currency risk.
Why is the RBI doing this now?
The aim is to attract foreign currency, swell forex reserves and steady a depreciating rupee. Higher reserves give the RBI more ammunition to sell dollars, improve import cover and ease balance-of-payments pressures. NRI deposits are a quick capital-account inflow compared with FDI or equity.
Has the RBI used such a window before?
Yes. During the 2013 ‘taper tantrum’, when the rupee fell sharply, the RBI opened a concessional FCNR(B) swap window that mobilised roughly USD 34 billion and helped stabilise the currency. The 2026 measure is a lighter, time-bound version of that crisis-management tool.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.