Why in News?
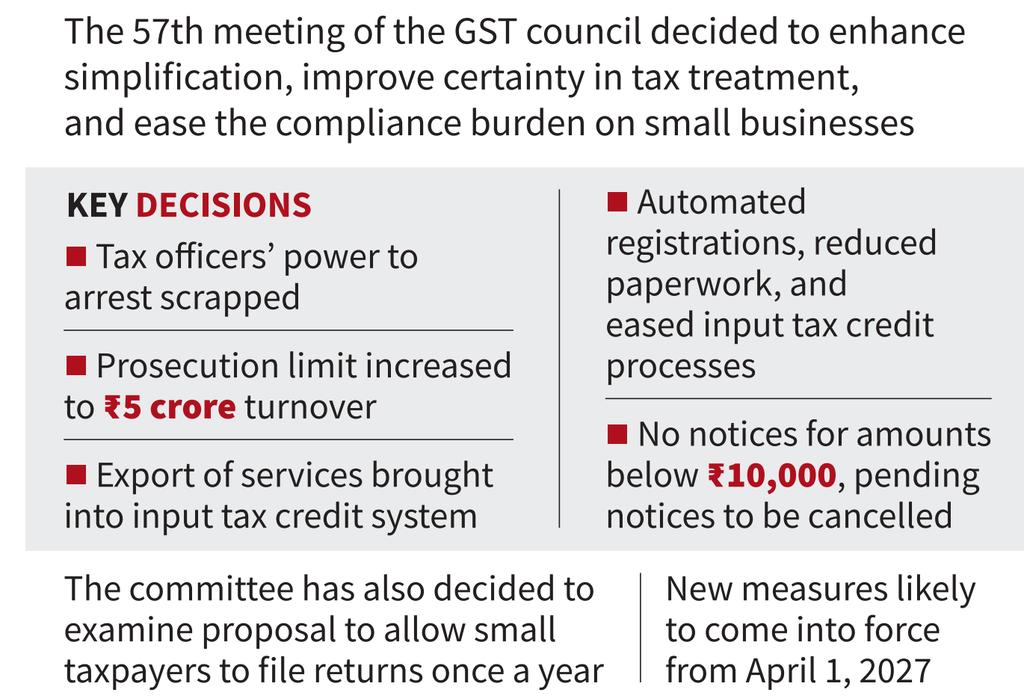
The 57th GST Council meeting chaired by the Union Finance Minister introduced landmark compliance and legal reforms. Aimed at enhancing the ease of doing business, the recommended reforms cover registration, refunds, input tax credit (ITC), enforcement and dispute resolution.
The changes are expected to come into effect from April 1, 2027, subject to the necessary legal and administrative changes.
| UPSC Relevance: GS-3 Economy: Tax reforms, Mobilisation of resources Prelims: GST, GST Council, input tax credit, inverted duty structure |
Major Recommendations:
(i) Arrest, Prosecution and Penalties:
- Withdrawal of arrest powers: Proposed removal of Section 69 of the CGST Act.
- Higher prosecution threshold: Proposed increase from ₹1 crore to ₹5 crore, as stated in the Council announcement.
- Reduced general penalty: Proposed reduction in the maximum general penalty, applicable where no specific penalty is prescribed, from ₹25,000 to ₹10,000.
- Sentencing discretion: Proposed removal of minimum punishment, allowing courts to determine fines, imprisonment or both within the amended statutory framework.
- Small-value disputes: No show-cause notices below ₹10,000; corresponding relief proposed for pending matters.
- Late-fee relief: For turnover up to ₹5 crore, proposed waiver where the delayed return is filed within its due month.
(ii) Refunds and Input Tax Credit:
- Faster acknowledgement: Proposed reduction from 15 to 10 days; applications would be deemed acknowledged if neither acknowledgement nor a deficiency memo is issued within that period.
- Provisional refunds: Proposed automatic, risk-based sanction of 90% of the amount claimed for zero-rated supplies and inverted duty cases. Avoid presenting this as a universal three-day payout guarantee.
- Electronic cash ledger: Proposed fully automated refunds of excess balances.
- Wider ITC eligibility: Proposed removal of restrictions covering employee health/life insurance, telecom towers, pipelines outside factories, free samples and specified expired stock.
- Input-service refunds: Proposed inclusion under inverted duty refunds for credit availed from 1 November 2026.
- Capital-goods refunds: Proposed inclusion for zero-rated and inverted duty cases, covering eligible credit availed from 1 April 2027, spread over 60 months.
(iii) Registration and Movement of Goods:
- Simplified e-commerce registration: Eligible sellers could use an operator’s warehouse as their business address in another State, with conditional automatic registration.
- Registration amendments and cancellation: Greater automation proposed, subject to applicable conditions.
- Vehicle checks: Intelligence-based interception with Joint Commissioner-level authorisation; ordinarily restricted to supplier/recipient States. Missing e-way bills or origin/destination documents permit action irrespective of jurisdiction.
Separately, the Union government proposed faceless Central GST assessment, with public consultation before Budget 2027 and implementation envisaged during 2027-28.
The reforms can improve GST’s effectiveness by making compliance easier and enforcement more proportionate. Their success will depend on timely refunds, coordinated implementation and credible safeguards against both harassment and fraud.
Practice Prelims MCQ:
Q. With reference to the Goods and Services Tax (GST) framework in India, consider the following statements:
- Under the dual GST model, Integrated GST (IGST) is levied and collected by the Union Government on all inter-state supplies of goods and services, and the revenue is retained entirely by the Centre to manage macro-fiscal imbalances.
2. “Exempt supplies” and “Zero-rated supplies” both result in a 0% tax incidence for the final consumer, but only zero-rated supplies allow the producer to claim a refund for the input taxes paid on raw materials.
3. Goods and Services Tax Appellate Tribunal (GSTAT) completely bypasses the requirement for taxpayers to approach the departmental Appellate Authorities.
Which of the statements given above is/are correct?
(a) 1 and 2 only
(b) 2 only
(c) 2 and 3 only
(d) 1, 2 and 3
Answer: (b)
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.