Why in news?
A former Agriculture Secretary calls for financing India’s entire agricultural value chain, not just farm production.
UPSC Relevance
Prelims: Kisan Credit Card, NABARD, Regional Rural Banks, priority sector lending, negotiable warehouse receipts and WDRA, Agriculture Infrastructure Fund, PM Kisan SAMPADA Yojana, PMFME.
Mains GS-III: Agricultural credit and marketing; food processing and related industries (scope, significance, upstream and downstream requirements, supply chain management); storage and transport of agricultural produce; inclusive growth; investment models.
Mains GS-II: Government policies and interventions for development; cooperatives and self-help groups.
What the author says
- First transformation achieved: India’s agricultural transformation is one of the greatest achievements of independent India. Over six decades, India has become one of the world’s largest producers of cereals, milk, fruits, vegetables and fisheries products. This was driven by public policy, scientific innovation, irrigation, institutional credit and the enterprise of millions of farmers.
- The next goal: The first transformation delivered food security. The next must deliver rural prosperity, by enabling rural India to capture a larger share of the value created after harvest.
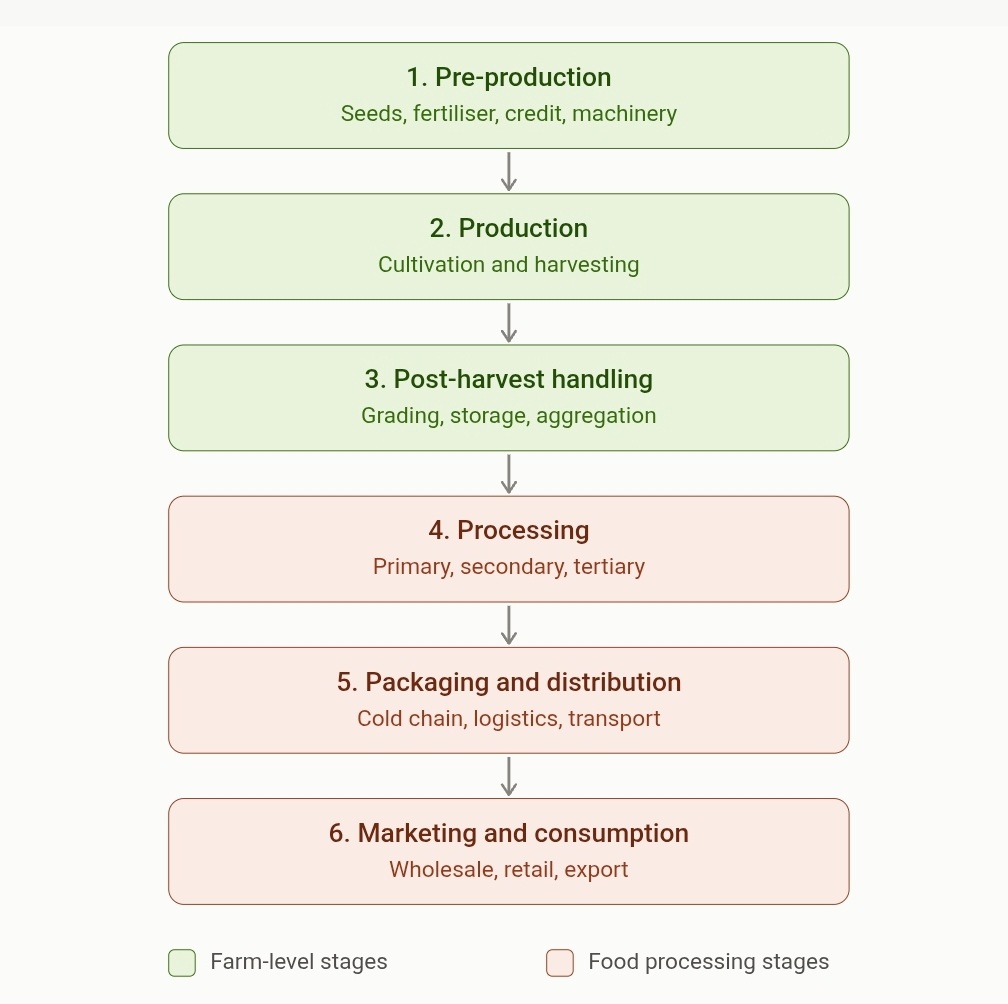
- Financing this change requires moving beyond production credit to financing the entire value chain. Every commodity passes through a chain, from production to aggregation, storage, logistics, processing, branding and markets. Enterprises, employment and prosperity grow along this chain.
- Examples :
- Perennial commodities : Dairy, poultry and fisheries have continuous procurement and marketing cycles, so they generate predictable cash flows, carry lower inventory risks and have regular working-capital turnover.
- Seasonal commodities :They are different, because processors must buy most of their annual raw material within a short harvest window and finance the inventory for the rest of the year. Sugar is also seasonal, yet its growth shows how inventory and warehouse-backed lending can overcome seasonal constraints. The difference in sector growth lies not in production potential but in the way the chain is financed.
- Past reforms: For over five decades, bank nationalisation, rural banks, cooperative institutions and the Kisan Credit Card expanded production credit, when national food security was the priority. India must now build mechanisms to finance every commercially viable activity between the farm and the final consumer.
The agro processing value chain
Production credit vs Value chain finance
| Basis | Production credit | Value chain finance |
| Focus | Financing the farmer to grow the crop (seeds, fertiliser, labour). | Financing every stage from farm to consumer: aggregation, storage, processing, logistics and marketing. |
| Borrowers | Mainly individual farmers. | Farmers, FPOs, input suppliers, aggregators, warehouses, processors, transporters, exporters and retailers. |
| Basis of lending | Land records and conventional collateral. | Cash flows of the chain, stored produce, receivables and buyer contracts. |
| Key tools | Kisan Credit Card, crop loans, interest subvention. | Warehouse receipt finance, receivables finance, product finance, credit guarantees, risk mitigation. |
| Objective | Food security and higher output. | Rural prosperity, value addition, jobs and a larger share of the consumer rupee for farmers. |
Instruments of value chain finance
| Instrument | How it works |
| Product finance | Credit linked to a specific commodity and its chain, such as input supplier credit or buyer advances to farmers under contract farming. |
| Receivables finance | A firm gets cash against the money buyers owe it. Factoring and the Trade Receivables Discounting System (TReDS), set up under RBI guidelines, are examples. |
| Warehouse receipt finance | A farmer or trader stores produce in a registered warehouse and pledges the receipt to a bank to get a loan, avoiding distress sale at harvest. |
| Risk mitigation solutions | Crop and commodity insurance, price hedging on commodity exchanges, and weather-based insurance reduce the risk for lenders. |
| Credit enhancement | Credit guarantees and first-loss cover by the government or development institutions make lenders willing to lend to small borrowers. |
Why value chain finance matters
- Higher farmer incomes: Farmers get only a small share of the consumer rupee in many perishable crops. Storage and processing finance lets them avoid distress sales at harvest and sell when prices are better.
- Reducing post-harvest losses: Large quantities of fruits, vegetables and grains are lost due to weak storage and cold chains. Financing infrastructure reduces this waste.
- Rural jobs: Processing, logistics and warehousing are labour-intensive and can absorb workers moving out of farming, where a large share of the workforce is still engaged with low productivity.
- Price stability: Better storage and processing smooth supply across the year, reducing price volatility in crops such as tomato, onion and potato.
- Exports and nutrition: Processed and branded products earn more in global markets and diversify diets at home.
- Successful models: The dairy cooperative model, built through Operation Flood (1970) under NDDB, linked farmers directly to processing and markets, making India the largest milk producer. The sugar sector shows how warehouse-backed lending supports a seasonal chain.
Schemes supporting the value chain
| Scheme | Key facts |
| Agriculture Infrastructure Fund (2020) | ₹1 lakh crore financing facility for post-harvest management and community farm assets; 3% interest subvention on loans up to ₹2 crore for up to 7 years, with credit guarantee cover. |
| Pradhan Mantri Kisan SAMPADA Yojana | Umbrella scheme of the Ministry of Food Processing Industries for mega food parks, cold chains, agro-processing clusters and food safety infrastructure. |
| PM Formalisation of Micro Food Processing Enterprises (PMFME, 2020) | Supports micro food processing units with credit-linked subsidy, using the One District One Product approach. |
| PLI Scheme for Food Processing (2021) | Production-linked incentives to build global food brands and increase processing capacity. |
| Formation and Promotion of 10,000 FPOs (2020) | Supports Farmer Producer Organisations with equity grants and credit guarantee to help farmers aggregate, store and sell together. |
| Priority Sector Lending | Banks must direct 18% of Adjusted Net Bank Credit to agriculture, with a sub-target for small and marginal farmers. |
Challenges
- Collateral-based lending: Banks still rely heavily on land and fixed assets, while small processors and FPOs lack such collateral.
- Weak warehouse network: Many warehouses are not registered with the WDRA, and the use of e-NWRs remains limited, especially among small farmers.
- Fragmented landholdings: Most farmers are small and marginal, which raises transaction costs for lenders.
- Informal credit: A significant share of farm households still borrow from moneylenders at high interest.
- Price and policy risks: Sudden export bans, stock limits and price controls raise the risk of holding inventory, which discourages lenders.
- Poor data: Lack of reliable data on cash flows, prices and quality makes it hard to assess credit risk along the chain.
- Isolated initiatives: As the author notes, current products of banks and NBFCs are scattered and not part of a single framework.
Way Ahead
- A national framework: Build a comprehensive agricultural value chain finance architecture, with commodity-specific financing models, coordinated by the Department of Agriculture, the RBI and NABARD.
- Cash-flow based lending: Encourage banks to lend on the basis of contracts, receivables and stored produce, using digital records rather than only land as collateral.
- Strengthen warehousing: Expand WDRA-registered warehouses and e-NWR use, and link them with e-NAM and commodity exchanges.
- Credit enhancement: Scale up credit guarantee schemes and first-loss funds for FPOs, small processors and warehouse operators.
- Use digital public infrastructure: The Digital Agriculture Mission, AgriStack and farmer IDs can provide data for credit appraisal.
- Policy stability: Predictable trade and stock policies will reduce the risk of holding inventory.
- Empower collectives: Make FPOs and cooperatives the anchor borrowers in value chains, as in the dairy model.
India’s first agricultural transformation was built on credit for production, and it made the country food secure. The second must be built on credit for the whole value chain, so that the value created after harvest stays in rural India. The author concludes that building such an architecture can be one of the most consequential reforms for achieving Viksit Bharat 2047.
Practice Questions
Q1. With reference to Electronic Negotiable Warehouse Receipts (e-NWRs) in India, consider the following statements:
1. They are issued by warehouses registered with the Warehousing Development and Regulatory Authority.
2. They can be used as collateral to obtain loans from banks.
3. The Warehousing Development and Regulatory Authority functions under the Ministry of Agriculture and Farmers Welfare.
How many of the statements given above are correct?
(a) Only one
(b) Only two
(c) All three
(d) None
Answer: (b). Statements 1 and 2 are correct. Statement 3 is incorrect, as the WDRA functions under the Department of Food and Public Distribution, Ministry of Consumer Affairs, Food and Public Distribution.
Q2. Under the Kisan Credit Card scheme, short-term credit support can be given to farmers for which of the following purposes?
1. Post-harvest expenses
2. Consumption requirements of the farm household
3. Working capital for animal husbandry and fisheries
4. Purchase of a car for the household
Select the correct answer using the code given below:
(a) 1 and 2 only
(b) 1, 2 and 3 only
(c) 2, 3 and 4 only
(d) 1, 2, 3 and 4
Answer: (b). The KCC covers post-harvest expenses, household consumption needs and, since 2018-19, working capital for animal husbandry and fisheries, but not the purchase of a car.
Mains Practice Question
“India’s first agricultural transformation was financed by production credit; the second will need finance for the entire value chain.” Discuss the constraints in financing post-harvest activities in India and suggest measures to build a robust agricultural value chain finance framework. (250 words, 15 marks)
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.