Why in News?
On 25 September 2026, the Ministry of MSME announced that CGTMSE credit guarantee cover had gone live on three TReDS platforms to support invoice discounting for eligible micro and small enterprises.
- Eligibility: both the buyer and seller must be micro or small enterprises; the special guarantee does not automatically cover every transaction eligible for the wider TReDS platform.
- Cover: CGTMSE guarantees 75% of the amount in default, rather than paying a subsidy against the original invoice value.
- Exposure ceilings: ₹10 crore for an eligible buyer and ₹2 crore for an eligible seller, both on a revolving basis.
- Financiers can check invoice eligibility and apply through the integrated platforms; fee calculation, debit and generation of the guarantee cover note are digitised.
- A completed sale can leave a business waiting for payment while wages and input bills are already due; invoice finance bridges this timing gap.
- The guarantee targets financier credit risk; it does not, by itself, ensure buyer acceptance, competitive bids or cheaper finance for every eligible business.
UPSC Relevance
Prelims Relevance
- TReDS: RBI-regulated electronic trade receivables financing.
- Factoring unit: invoice or bill details representing a receivable.
- CGTMSE: Credit Guarantee Fund Trust for Micro and Small Enterprises.
- Special guarantee eligibility: both counterparties must be micro or small enterprises.
- Default cover differs from an invoice subsidy and from a revolving exposure ceiling.
Mains Relevance
GS Paper 3
- Working-capital constraints and formal finance for small enterprises.
- Credit guarantees, competition and prudent sharing of default risk.
GS Paper 2
- Distinguishing a digital scheme launch from verified delivery outcomes.
Essay
- A healthy credit system depends on reliable payment relationships, not only additional lending.
Background and Context
Why a profitable small firm can still lack cash
Invoice finance addresses the gap between making a sale and collecting its payment, rather than proving that every business receiving finance is profitable.
- A trade receivable is money owed for goods or services already supplied. It records a claim against a buyer, but cannot immediately pay wages or purchase the next batch of raw materials.
- Working capital supports day-to-day operations. When buyers pay later than production costs arise, a small manufacturer may have confirmed sales yet insufficient available cash to continue accepting orders without arranging additional short-term finance.
- Under invoice discounting, the seller receives money before the invoice matures, less the financing charge. The practical trade-off is accepting a smaller immediate payment instead of waiting for the full amount later.
- TReDS brings sellers, buyers and competing financiers into an electronic marketplace. Its broader MSME remit must be separated from the narrower micro-and-small-enterprise eligibility conditions attached to this particular guarantee provision for invoice financing.
- The ministry announcement links the new cover to timely working capital. That is the policy objective; establishing actual benefits requires evidence about participation, financing charges and payment performance after implementation.
Follow the invoice and the money
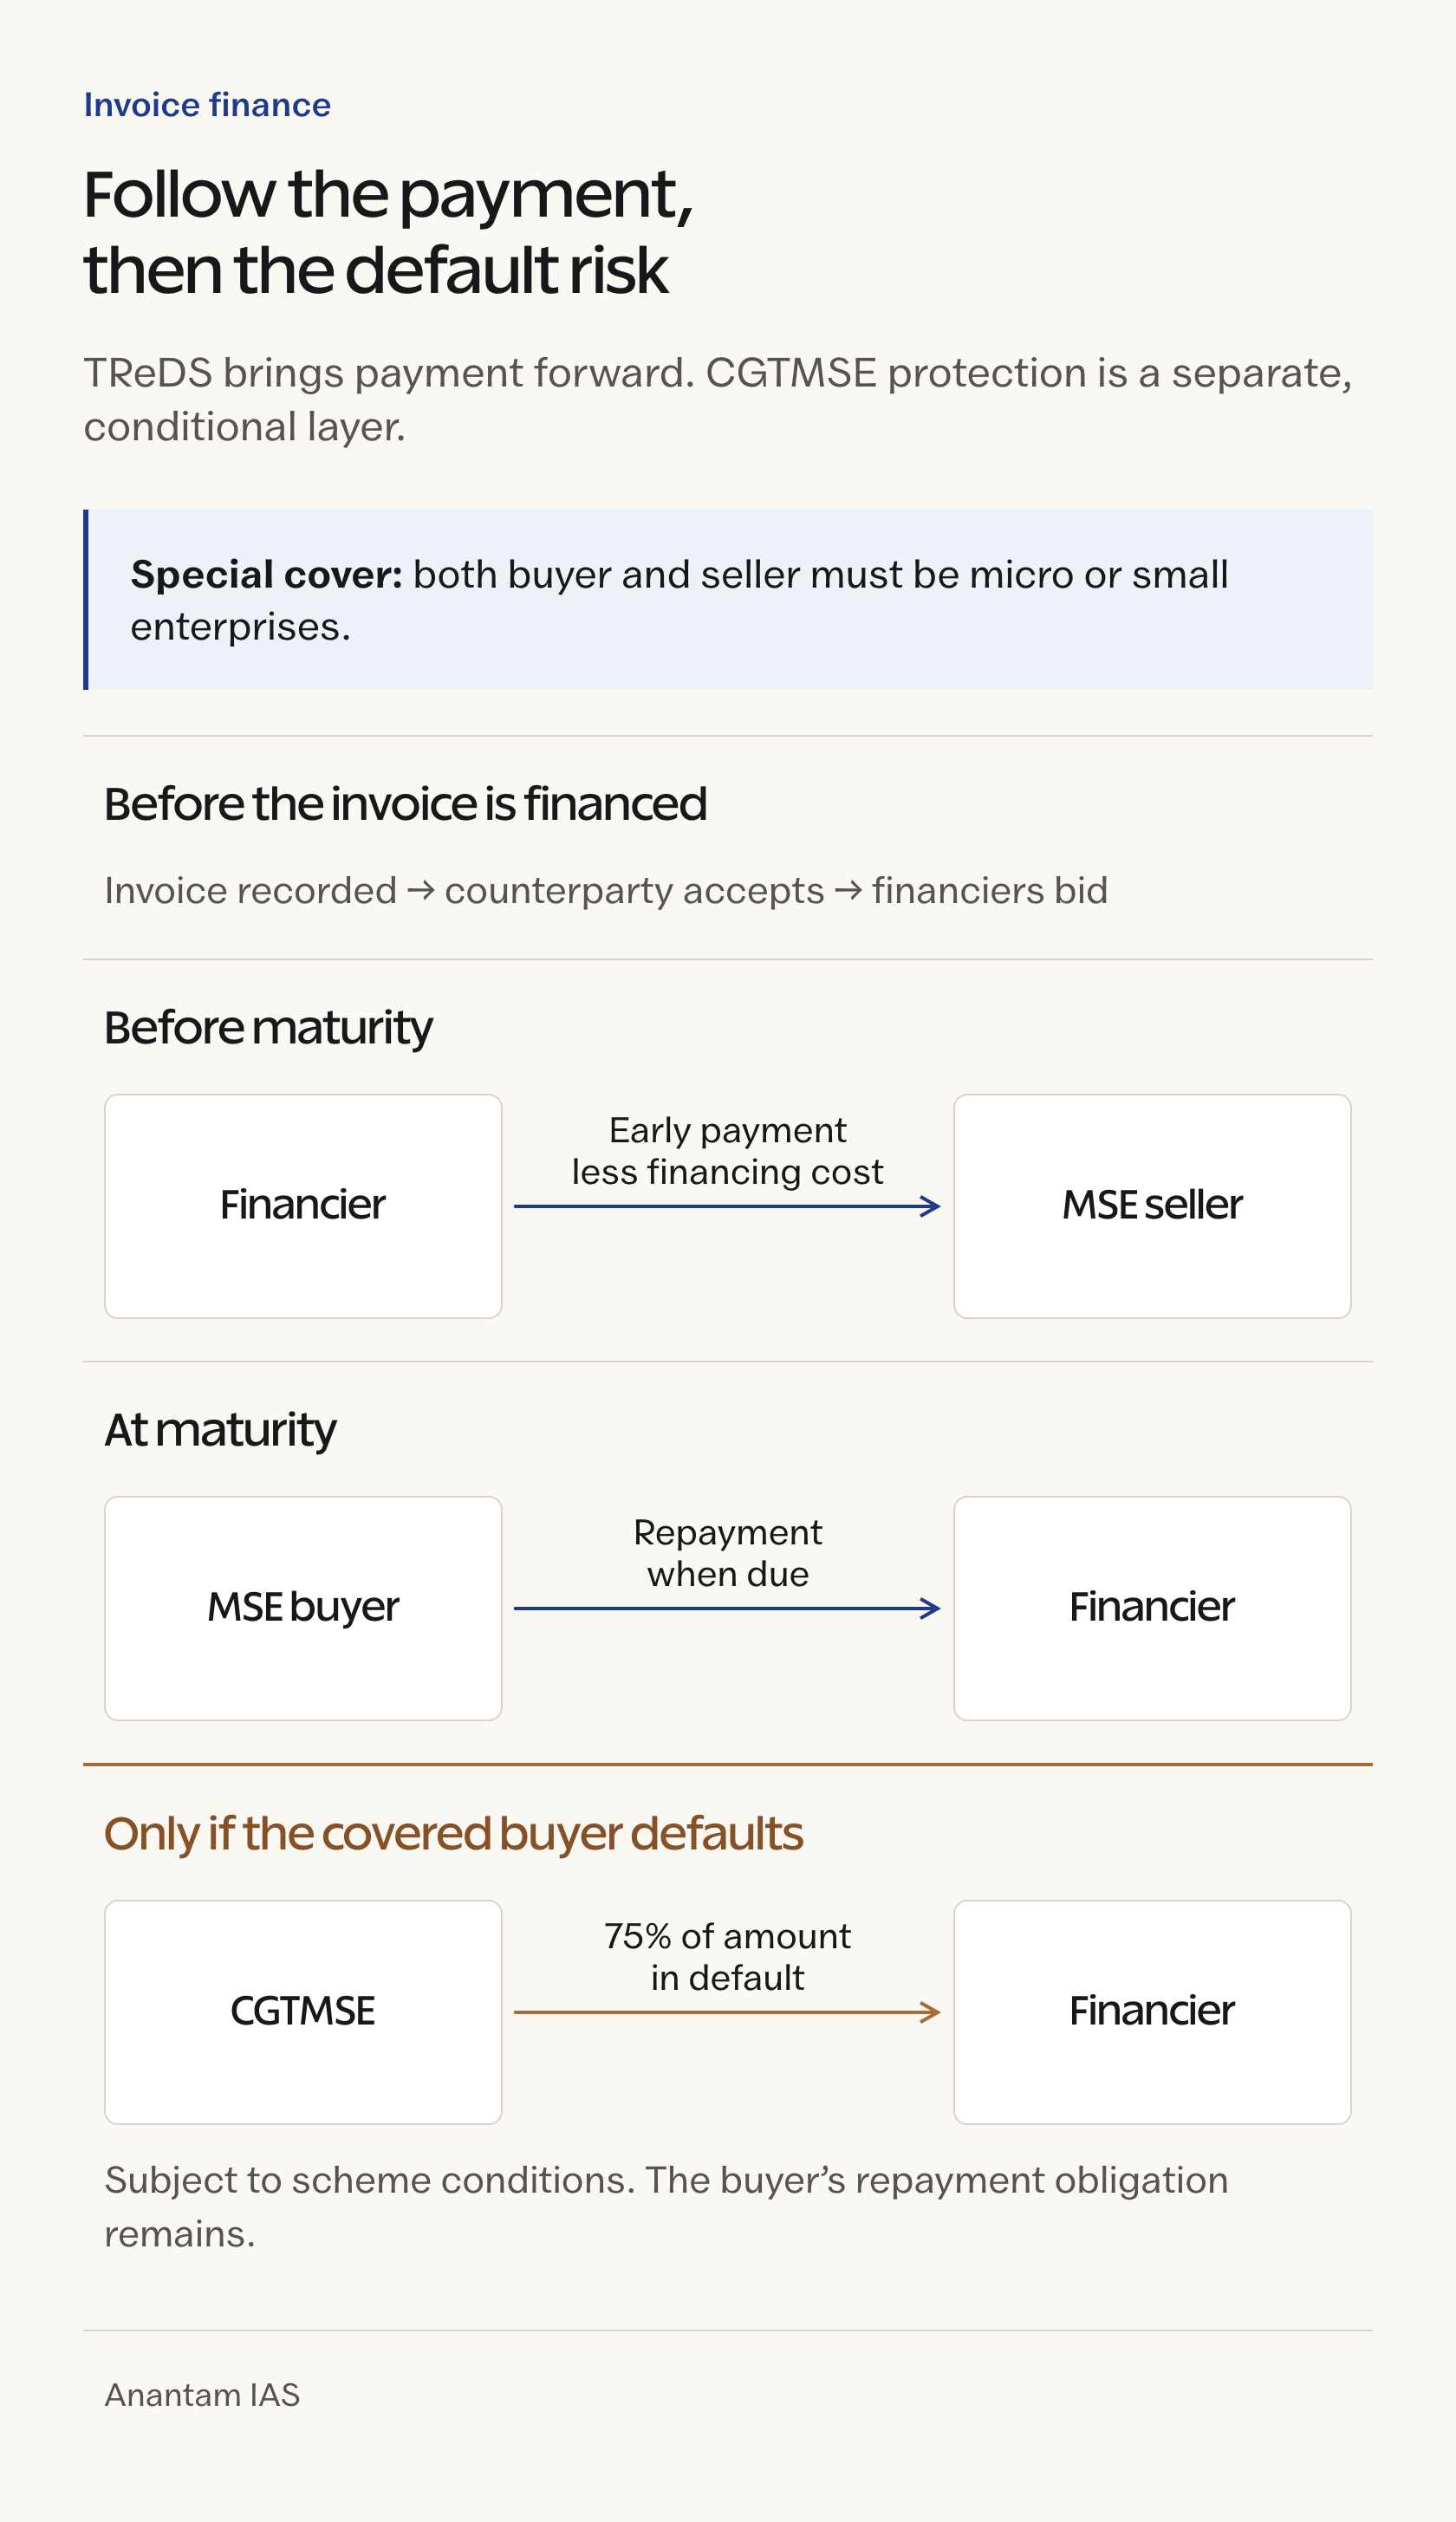
The essential sequence separates recognition of the buyer’s obligation, payment to the seller and eventual repayment to the financier, rather than treating them as one transaction.
- According to the RBI explanation, a factoring unit records invoice or bill details. The seller or buyer creates it, and the other party accepts it before financing proceeds through the platform.
- Acceptance connects the invoice to an acknowledged buyer obligation. Uploading a document alone is not the same as obtaining finance; the transaction must proceed through acceptance and the subsequent bidding and selection stages.
- Eligible financiers offer competing bids for the receivable, and a bid is selected. The financing charge reflects the transaction’s terms; the presence of an electronic auction does not mean that funding is free.
- The selected financier pays the seller early, allowing the seller to use the proceeds in its business. At maturity, the buyer pays the financier, completing the normal repayment path associated with that receivable.
- For an eligible covered transaction, CGTMSE shares default risk with the financier if the buyer fails to repay, subject to scheme conditions. This is a separate contingent protection, not another routine payment to the seller.
What a guarantee changes, and what it does not
The new protection changes the financier’s exposure to default; it does not turn a commercial receivable into a grant or remove the buyer’s payment obligation.
- Partial cover leaves some default exposure outside the guarantee. Financiers still have reasons to assess the transaction carefully; a guarantee should support credit decisions rather than replace checks on whether the underlying sale is genuine.
- The announced limits apply to revolving exposure, meaning capacity can become available again as covered obligations run off, within the applicable rules. They are not permanent cash entitlements that every participating enterprise receives upfront.
- Guarantee fees are calculated using invoice value, financier type and tenor, according to the ministry. Any assessment of affordability should consider applicable costs together, rather than looking only at the discount rate quoted initially.
- The buyer remains responsible for repayment. Guarantee protection addresses the financier’s risk after default; it should not be confused with debt forgiveness or permission for a buyer to disregard the agreed payment date.
- Go-live establishes operational availability, not universal access or measured savings. Useful evaluation asks whether otherwise underserved firms obtain bids, what they pay, and whether financing expands without weakening scrutiny or encouraging avoidable defaults.
Way Forward
Measure access without weakening payment discipline
- Track eligible invoices financed and unsuccessful applications to identify whether buyer acceptance, limited bidding or documentation remains the main obstacle.
- Compare total financing costs across comparable transactions, including applicable guarantee charges, before describing the scheme as cheaper credit.
- Maintain checks on genuine receivables and publish claim-processing performance so easier access does not conceal poor underwriting or delayed risk protection.
Conclusion
- TReDS converts a payment claim into earlier liquidity, while CGTMSE adds conditional protection against default. Keeping these two functions separate explains why invoice finance can support production without becoming a subsidy for every invoice.
- For a Mains answer, assess access, cost and repayment discipline together. The relevant question is whether risk sharing brings viable small enterprises into formal finance while preserving scrutiny of invoices and the buyer’s obligation to pay.
UPSC Practice Questions
Prelims MCQ 1
With reference to the special CGTMSE guarantee provision for TReDS, consider the following statements:
- Both the buyer and seller must be micro or small enterprises.
- The cover equals 75% of the amount in default.
- The guarantee extinguishes the buyer’s repayment obligation.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
The ministry specifies the first two conditions. A guarantee protects against default risk; it does not cancel the buyer’s payment obligation.
Prelims MCQ 2
Which sequence best describes normal financing and repayment on TReDS?
(a) Buyer pays seller early; seller repays CGTMSE at maturity. (b) CGTMSE grants the invoice value to the seller before acceptance. (c) Financier pays seller early; buyer pays financier at maturity. (d) Seller pays financier first; buyer receives the guarantee as cash.
Answer: (c) Financier pays seller early; buyer pays financier at maturity.
Explanation:
Invoice discounting brings forward the seller’s receipt through financing. The buyer subsequently settles the financed obligation with the financier.
UPSC Mains Questions
- Explain how invoice discounting and partial credit guarantees address different barriers to working-capital finance for small enterprises.
- What indicators would you use to evaluate whether the new TReDS guarantee provision improves access without weakening payment discipline?
Sources: PIB, Ministry of Micro, Small and Medium Enterprises and Reserve Bank of India: TReDS FAQs.
Frequently Asked Questions
What is TReDS?
TReDS is an RBI-regulated electronic system that facilitates financing of MSME trade receivables. It connects sellers, buyers and financiers so an accepted invoice can provide cash before its payment due date.
Who qualifies for the new CGTMSE guarantee?
The special provision requires both buyer and seller to be micro or small enterprises. This is narrower than the broader MSME financing scope of TReDS and does not automatically cover every platform transaction.
Is the guarantee an invoice subsidy?
No. The announced cover is 75% of the amount in default, subject to scheme conditions. It protects against part of the financier’s risk rather than giving the seller that share of its invoice as a subsidy.
Do the revolving limits provide free money?
No. They cap exposure associated with eligible buyers and sellers. Revolving capacity can become available again as obligations run off under applicable rules; the limits are not upfront grants or unconditional payments.
Does go-live mean every eligible enterprise gets cheaper credit?
No. The ministry states an objective of improved access at competitive rates. Actual availability and cost depend on transaction eligibility, acceptance, bids and applicable charges, and must be assessed using evidence after launch.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.