Why in News?
Make in India completed 12 years on September 25, 2026, marking more than a decade of policy efforts to strengthen India’s manufacturing base.
The period has seen significant production growth in electronics, automobiles, defence, steel, and other strategic sectors, alongside initiatives such as PLI, PM GatiShakti, and the National Single Window System.
However, the 12-year journey also raises a larger structural question: Has the expansion of selected manufacturing industries translated into a broad-based transformation of India’s manufacturing ecosystem?
| UPSC Relevance: GS-3 Economy: Industrial policy, economic growth, employment, investment and infrastructure Prelims: Make in India, PLI, FDI, GVA, IIP and gross fixed capital formation |
Key Features of Make in India Scheme:
- Launched on 25 September 2014, Make in India is an umbrella framework to transform India into a global design, manufacturing, and investment hub through targeted policy reforms, infrastructure development, and industrial incentives.
- Led by the Ministry of Commerce and Industry and implemented through the Department for Promotion of Industry and Internal Trade (DPIIT).
A. Four Foundational Pillars:
- New Processes: Streamlines regulatory compliance and approvals to improve the Ease of Doing Business (EoDB).
- New Infrastructure: Develops high-speed industrial corridors, logistics hubs, and modern facilities that foster innovation and cluster-based manufacturing.
- New Sectors: Opens and expands foreign investment limits across crucial defence, infrastructure, railway, and manufacturing segments.
- New Mindset: Shifts the government’s operational role from that of an industry regulator to an active enterprise partner and facilitator.
B. Expanded Sectoral Scope
- From 25 to 27 Sectors: Make in India originally identified 25 sectors. Under Make in India 2.0, it covers 27 sectors divided into 15 manufacturing sectors (coordinated by DPIIT) and 12 services sectors (coordinated by the Department of Commerce).
- Beyond Factory Floors: By integrating high-value service sectors (such as IT, legal, logistics, and medical tourism), the initiative supports the end-to-end industrial lifecycle from design and funding to digital integration and export.
C. Core Enabling Instruments:
- Investment Facilitation: Broad-based FDI liberalisation via automatic routes, streamlined clearances through the National Single Window System (NSWS), and mapped site acquisitions using the India Industrial Land Bank (IILB).
- Integrated Infrastructure: Multimodal connectivity powered by the PM GatiShakti National Master Plan alongside dedicated industrial corridor networks.
- Targeted Output Incentives: Dedicated Production Linked Incentive (PLI) schemes spanning 14 sectors to scale up domestic manufacturing, attract frontier technology, and boost export competitiveness.
- Enterprise & Innovation Ecosystem: Synergy with complementary national missions like Startup India, the National Logistics Policy, and sector-specific roadmaps for semiconductors, electronics, and capital goods.
Achievements during the 12 Years:
(i) Expansion of manufacturing output
The government’s anniversary assessment highlights several sectoral gains:
- Electronics: Production increased from approximately ₹1.9 lakh crore in 2014-15 to ₹13.11 lakh crore in 2025-26.
- Mobile phones: Production value increased from around ₹18,000 crore to ₹6.27 lakh crore over the same period.
- Defence: Indigenous production rose from ₹46,429 crore to ₹1.78 lakh crore over the same period.
- Steel: Crude steel production increased from 81.7 million tonnes to 170 million tonnes over this period.
- Automobiles: Vehicle production reached 31.03 million units in 2024-25, about 33% above 2014-15.
- Railways: Average annual coach production increased from fewer than 3300 during 2004-14 to 5481 during 2014-24.
(ii) Greater technological and industrial capability:
The report identifies progress beyond final-product assembly:
- Space electronics: Indigenous VIKRAM3201 and KALPANA3201 microprocessors demonstrate capabilities in specialised chip design and development.
- Strategic materials: The Nd-Fe-B rare-earth magnet pilot facility at ARCI, Hyderabad, supports indigenous process development.
- Capital goods: Production across the listed capital-goods and heavy-engineering segments nearly doubled between 2019-20 and 2024-25.
- Clean technology: Expansion in solar-cell and module manufacturing strengthens the domestic renewable-energy supply chain.
Such capabilities can reduce strategic vulnerabilities and generate domestic demand for components, engineering services and skilled labour.
(iii) Investment and production under PLI:
- By mid 2026, PLI schemes had attracted approximately ₹2.40 lakh crore in investment, generated over ₹22.66 lakh crore in production/sales, and supported more than 14 lakh jobs.
(iv) Improved access to industrial credit:
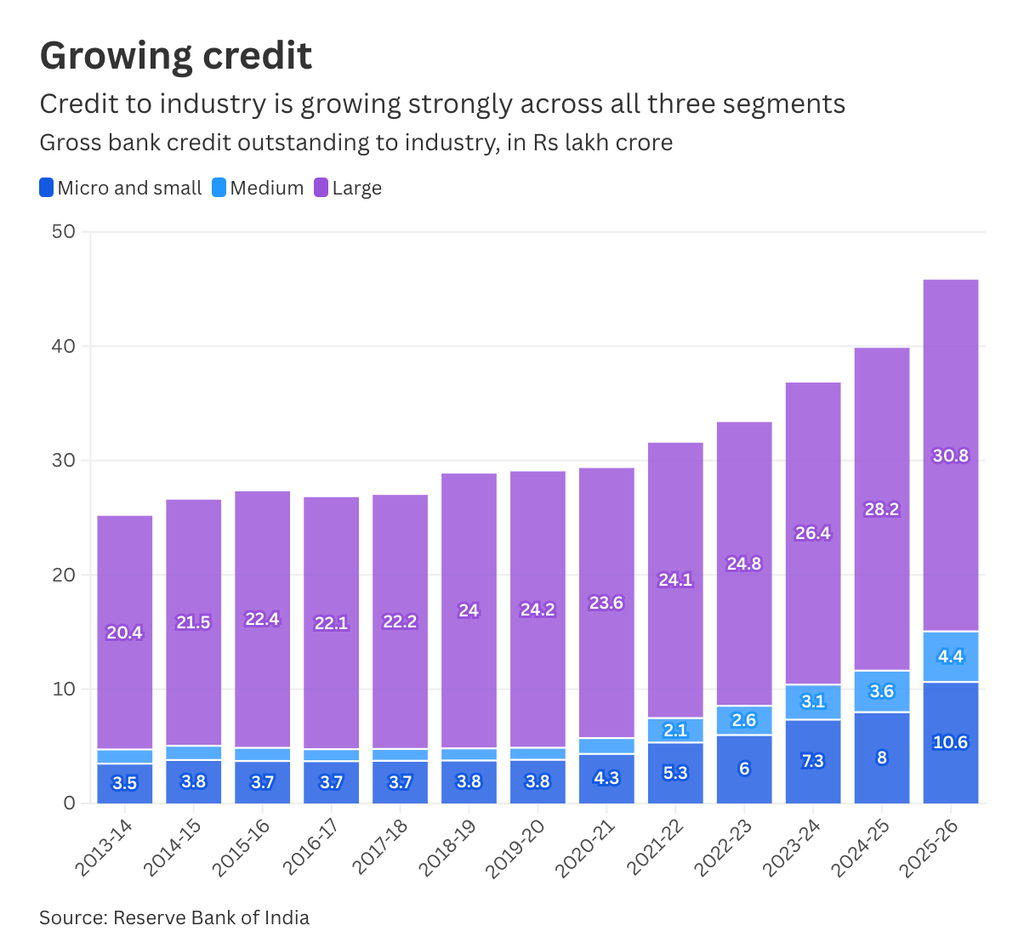
- The outstanding bank credit to micro and small industries increased from ₹3.5 lakh crore in 2013-14 to ₹10.6 lakh crore in 2025-26.
Existing Challenges to Make in India:
(i) Limited structural transformation:
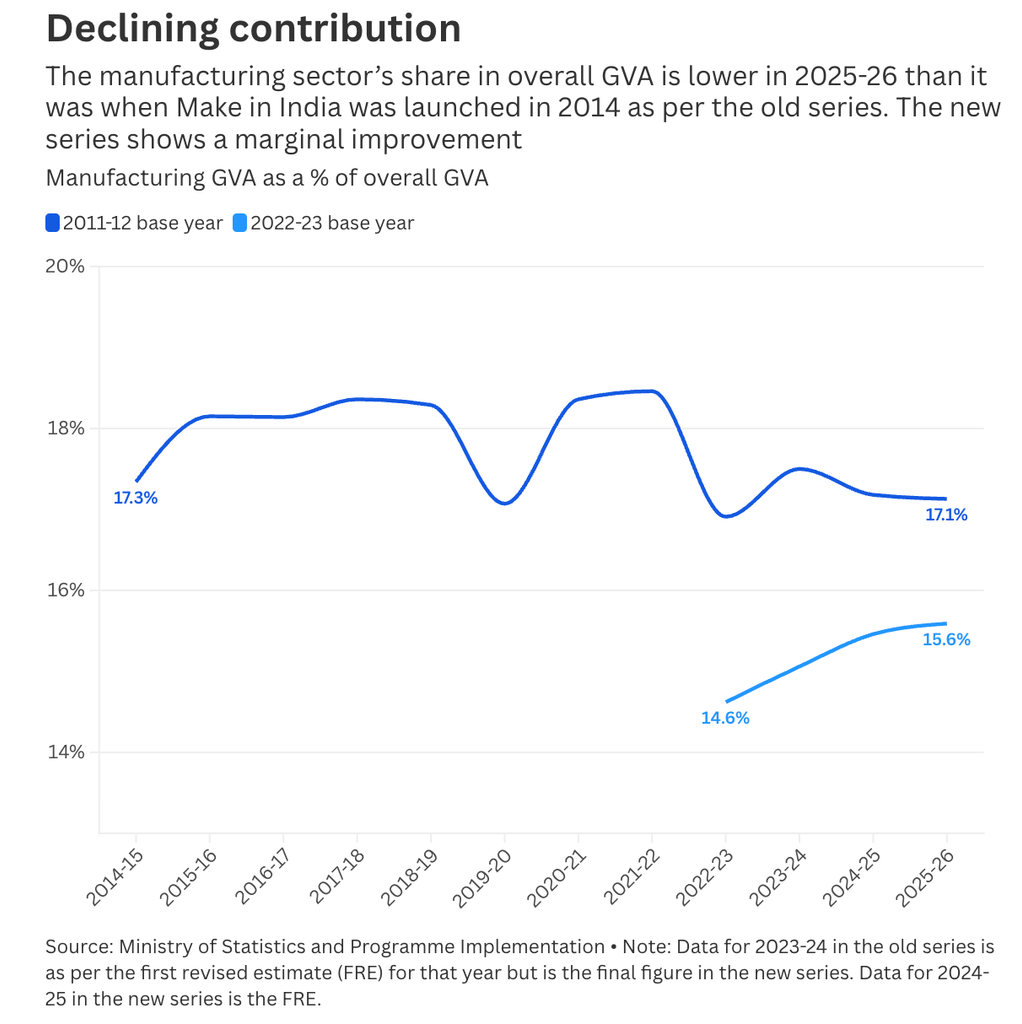
- The manufacturing’s share in total GVA:
- Declined marginally from 17.3% in 2014-15 to 17.1% in 2025-26 under the old series.
- Increased from 14.6% in 2022-23 to 15.6% in 2025-26 under the revised series.
- Thus, increased production in successful industries has not yet translated into a decisive economy-wide shift towards manufacturing.
(ii) Insufficient employment transformation:
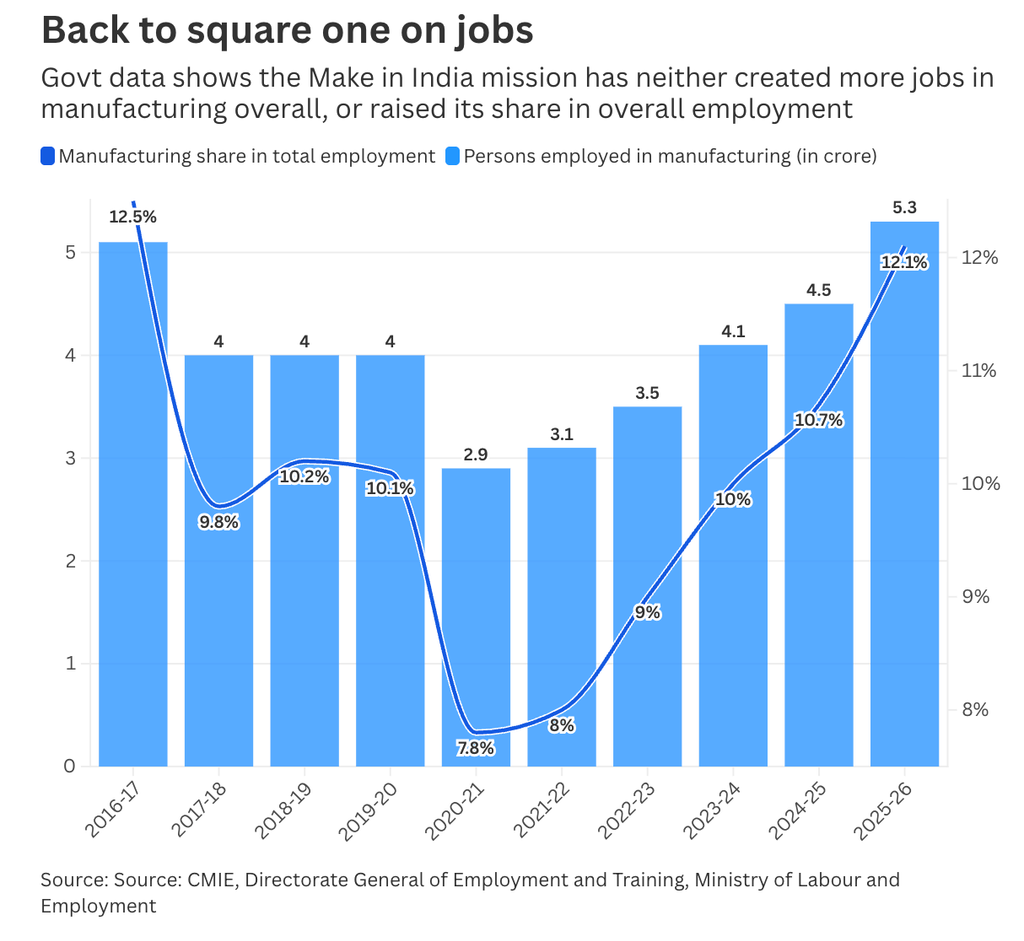
- Manufacturing employment increased only modestly, from 5.1 crore in 2016-17 to 5.3 crore in 2025-26, while its employment share remained below the initial level. This suggests limited large-scale absorption of workers into manufacturing.
(iii) Rising exports without a larger global presence:
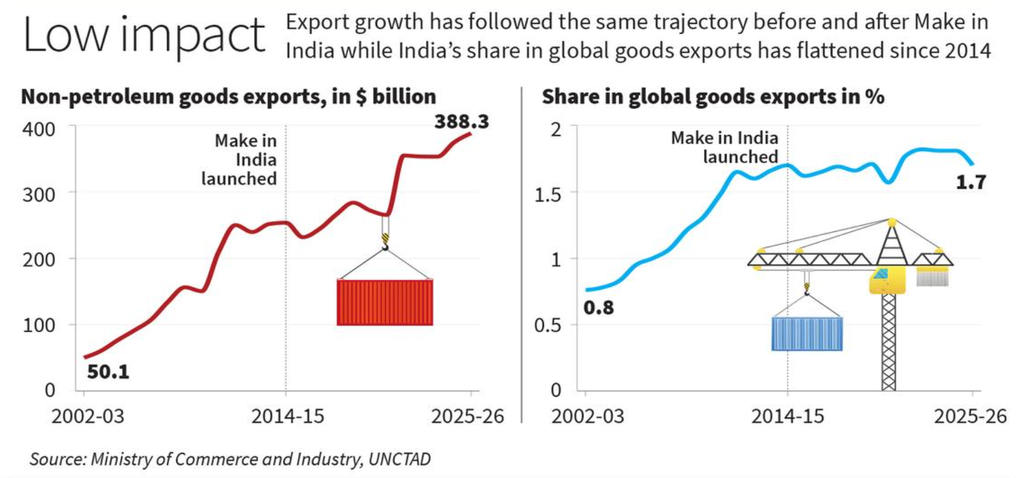
- Non-petroleum goods exports rose from $253.5 billion in 2014-15 to $388.3 billion in 2025-26, while India’s global merchandise-export share remained around 1.7%. Export expansion has not produced a sustained increase in global market share.
(iv) Uneven private-investment response:
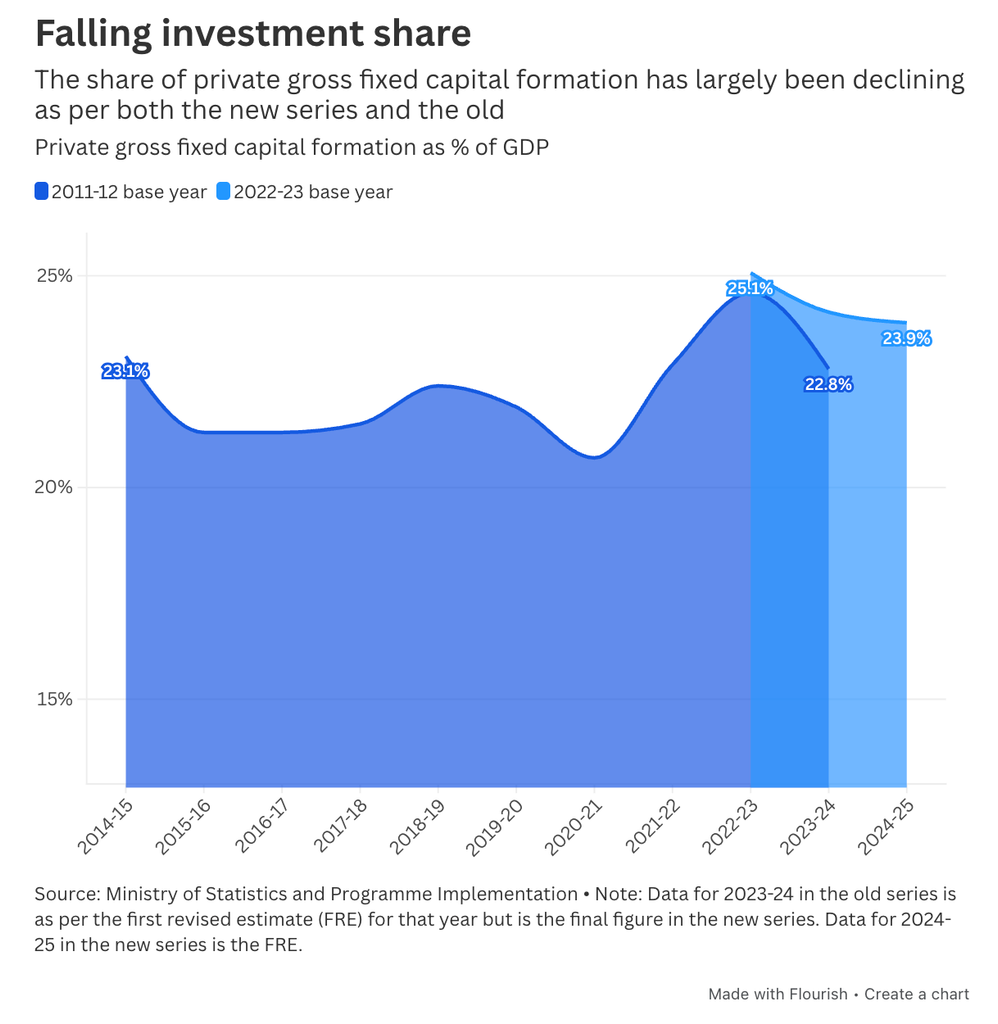
- The revised-series chart shows private GFCF falling from 25.1% of GDP in 2022-23 to 23.9% in 2024-25. This suggests that infrastructure spending and incentives have not yet generated a sustained rise in private investment relative to GDP.
(v) Concentration of PLI gains:
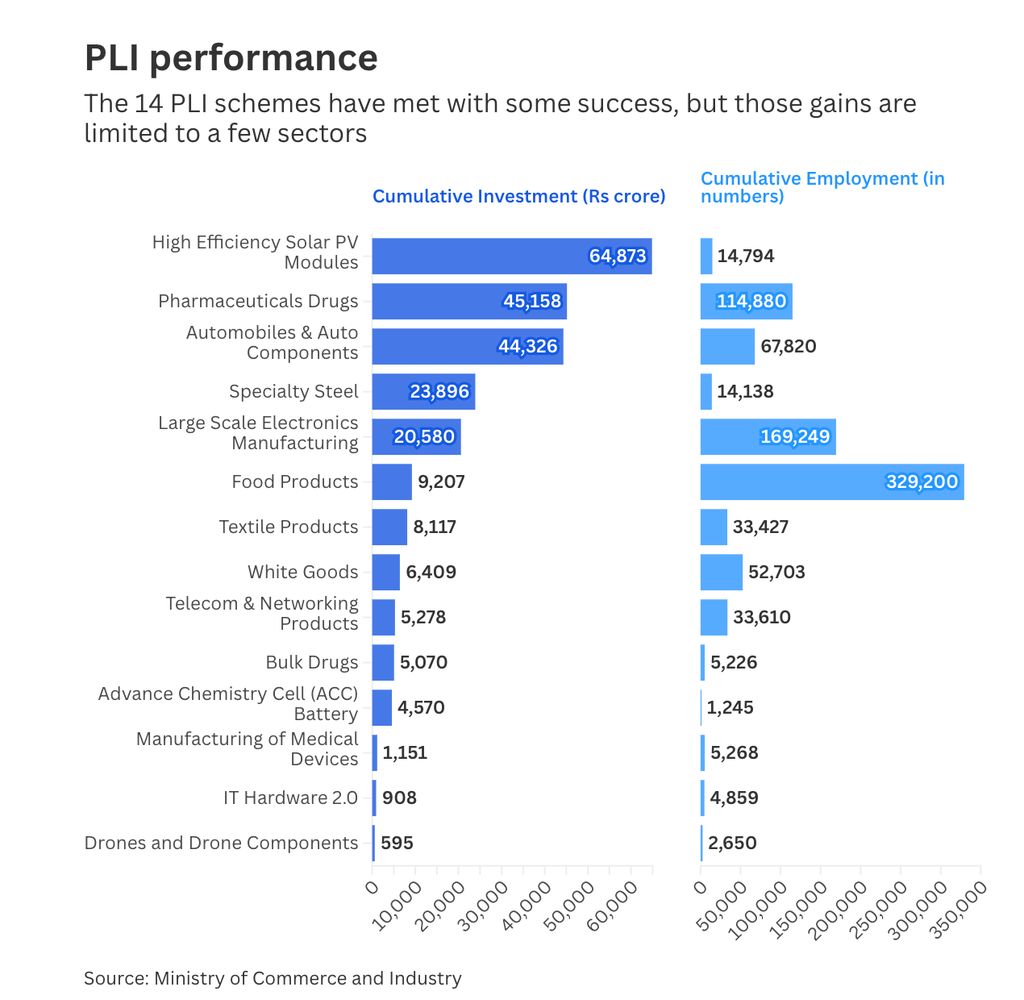
- Five sectors- solar modules, pharmaceuticals, automobiles and components, speciality steel, and large-scale electronics accounted for nearly 83% of PLI investment. Sectoral success therefore needs to spread more widely, particularly to industries capable of generating substantial employment.
(vi) Gaps in domestic value addition
- High final-product output can coexist with dependence on imported components, machinery and technology. E.g., the supplied report’s much larger solar-module capacity than solar-cell capacity indicates uneven development across the production chain.
(vii) Constraints on firm competitiveness
- MSME limitations: Restricted finance, delayed payments and weak technology adoption constrain expansion.
- Infrastructure gaps: Unreliable utilities and weak last-mile connectivity raise production costs.
- Regulatory uncertainty: Complex approvals and unpredictable policy changes discourage long-term investment.
- Skills and innovation gaps: Firms need stronger links with training institutions, research laboratories and domestic suppliers.
Way Forward:
- Shift focus from assembly to value-chain depth: Prioritise the domestic production of components, materials, machinery, industrial electronics and critical intermediate goods, rather than measuring success primarily through final-product output.
- Build an MSME-to-global-firm manufacturing architecture: Large manufacturers should be linked systematically with domestic MSME suppliers through supplier-development programmes, common testing and certification facilities, technology-sharing arrangements and easier access to working capital. This would allow PLI-led investment to create wider industrial ecosystems rather than isolated large-scale production units.
- Focus on labour-intensive manufacturing: Electronics and capital-intensive sectors cannot absorb India’s large workforce. A dedicated manufacturing strategy for textiles, garments, footwear, furniture, toys, food processing and other labour-intensive sectors should combine plug-and-play industrial clusters, export infrastructure, skilling and predictable trade policy.
- Move from subsidy-led competitiveness to productivity-led competitiveness: PLI-type incentives should increasingly reward incremental domestic value addition, productivity, exports, R&D, supplier development and durable employment, with sunset and review mechanisms.
- Make States the next frontier of Make in India: States should be evaluated on measurable industrial outcomes such as time taken to operationalise projects, reliability of utilities, logistics costs, land availability and employment generation, rather than merely the number of MoUs signed.
- Use global integration strategically: India should combine selective strategic self-reliance in areas such as semiconductors, critical minerals and defence with competitive access to imported inputs and participation in global value chains. FTAs, customs procedures and standards policy should be aligned to make India a competitive production base.
- Make technology absorption a core manufacturing objective: Domestic manufacturing capability should extend to product design, process engineering, patents, industrial R&D and advanced machinery. Greater collaboration between firms, IITs, research institutions and technology centres.
- Create a single manufacturing performance dashboard: The success of Make in India should be assessed through a consistent set of indicators: manufacturing GVA, labour productivity, domestic value addition, manufacturing employment, private investment, export market share, MSME participation and R&D intensity.
The next challenge is more demanding: turning islands of manufacturing success into dense industrial ecosystems.
The focus must therefore shift to create more value in India, employ more workers productively, develop Indian technologies and embed Indian firms deeper in global supply chains. This would make manufacturing a broader engine of growth, employment and economic resilience.
Practice Prelims MCQ:
Q. Consider the following statements:
- Make in India 2.0 covers both manufacturing and services sectors.
- An increase in manufacturing output necessarily increases manufacturing’s share in total GVA.
- Higher exports of assembled products necessarily indicate proportionately higher domestic value addition.
Which of the statements given above is/are correct?
(a) 1 only
(b) 1 and 2 only
(c) 2 and 3 only
(d) 1, 2 and 3
Answer: (a) Manufacturing’s GVA share depends on its growth relative to other sectors. Export value may include substantial imported inputs.
Mains Practice Question:
Q. “Make in India has delivered significant sectoral achievements, but its contribution to broad-based industrial transformation remains uneven.” Critically examine and suggest measures to strengthen domestic value addition and employment generation.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.