Why in News?
On July 26, 2026, Reserve Bank of India Governor Sanjay Malhotra reiterated that it was reasonable to regard the Indian rupee as undervalued in both nominal and real effective exchange-rate terms. The Hindu reported the remarks on July 29 as an unusual public assessment of whether a currency’s market price matches its underlying economic fundamentals.
The Governor paired that assessment with an important qualification: the RBI does not target a fixed rupee-dollar rate or an exchange-rate band. Its foreign-exchange operations are intended to contain excessive volatility and preserve orderly market conditions, not guarantee a permanently strong or weak rupee.
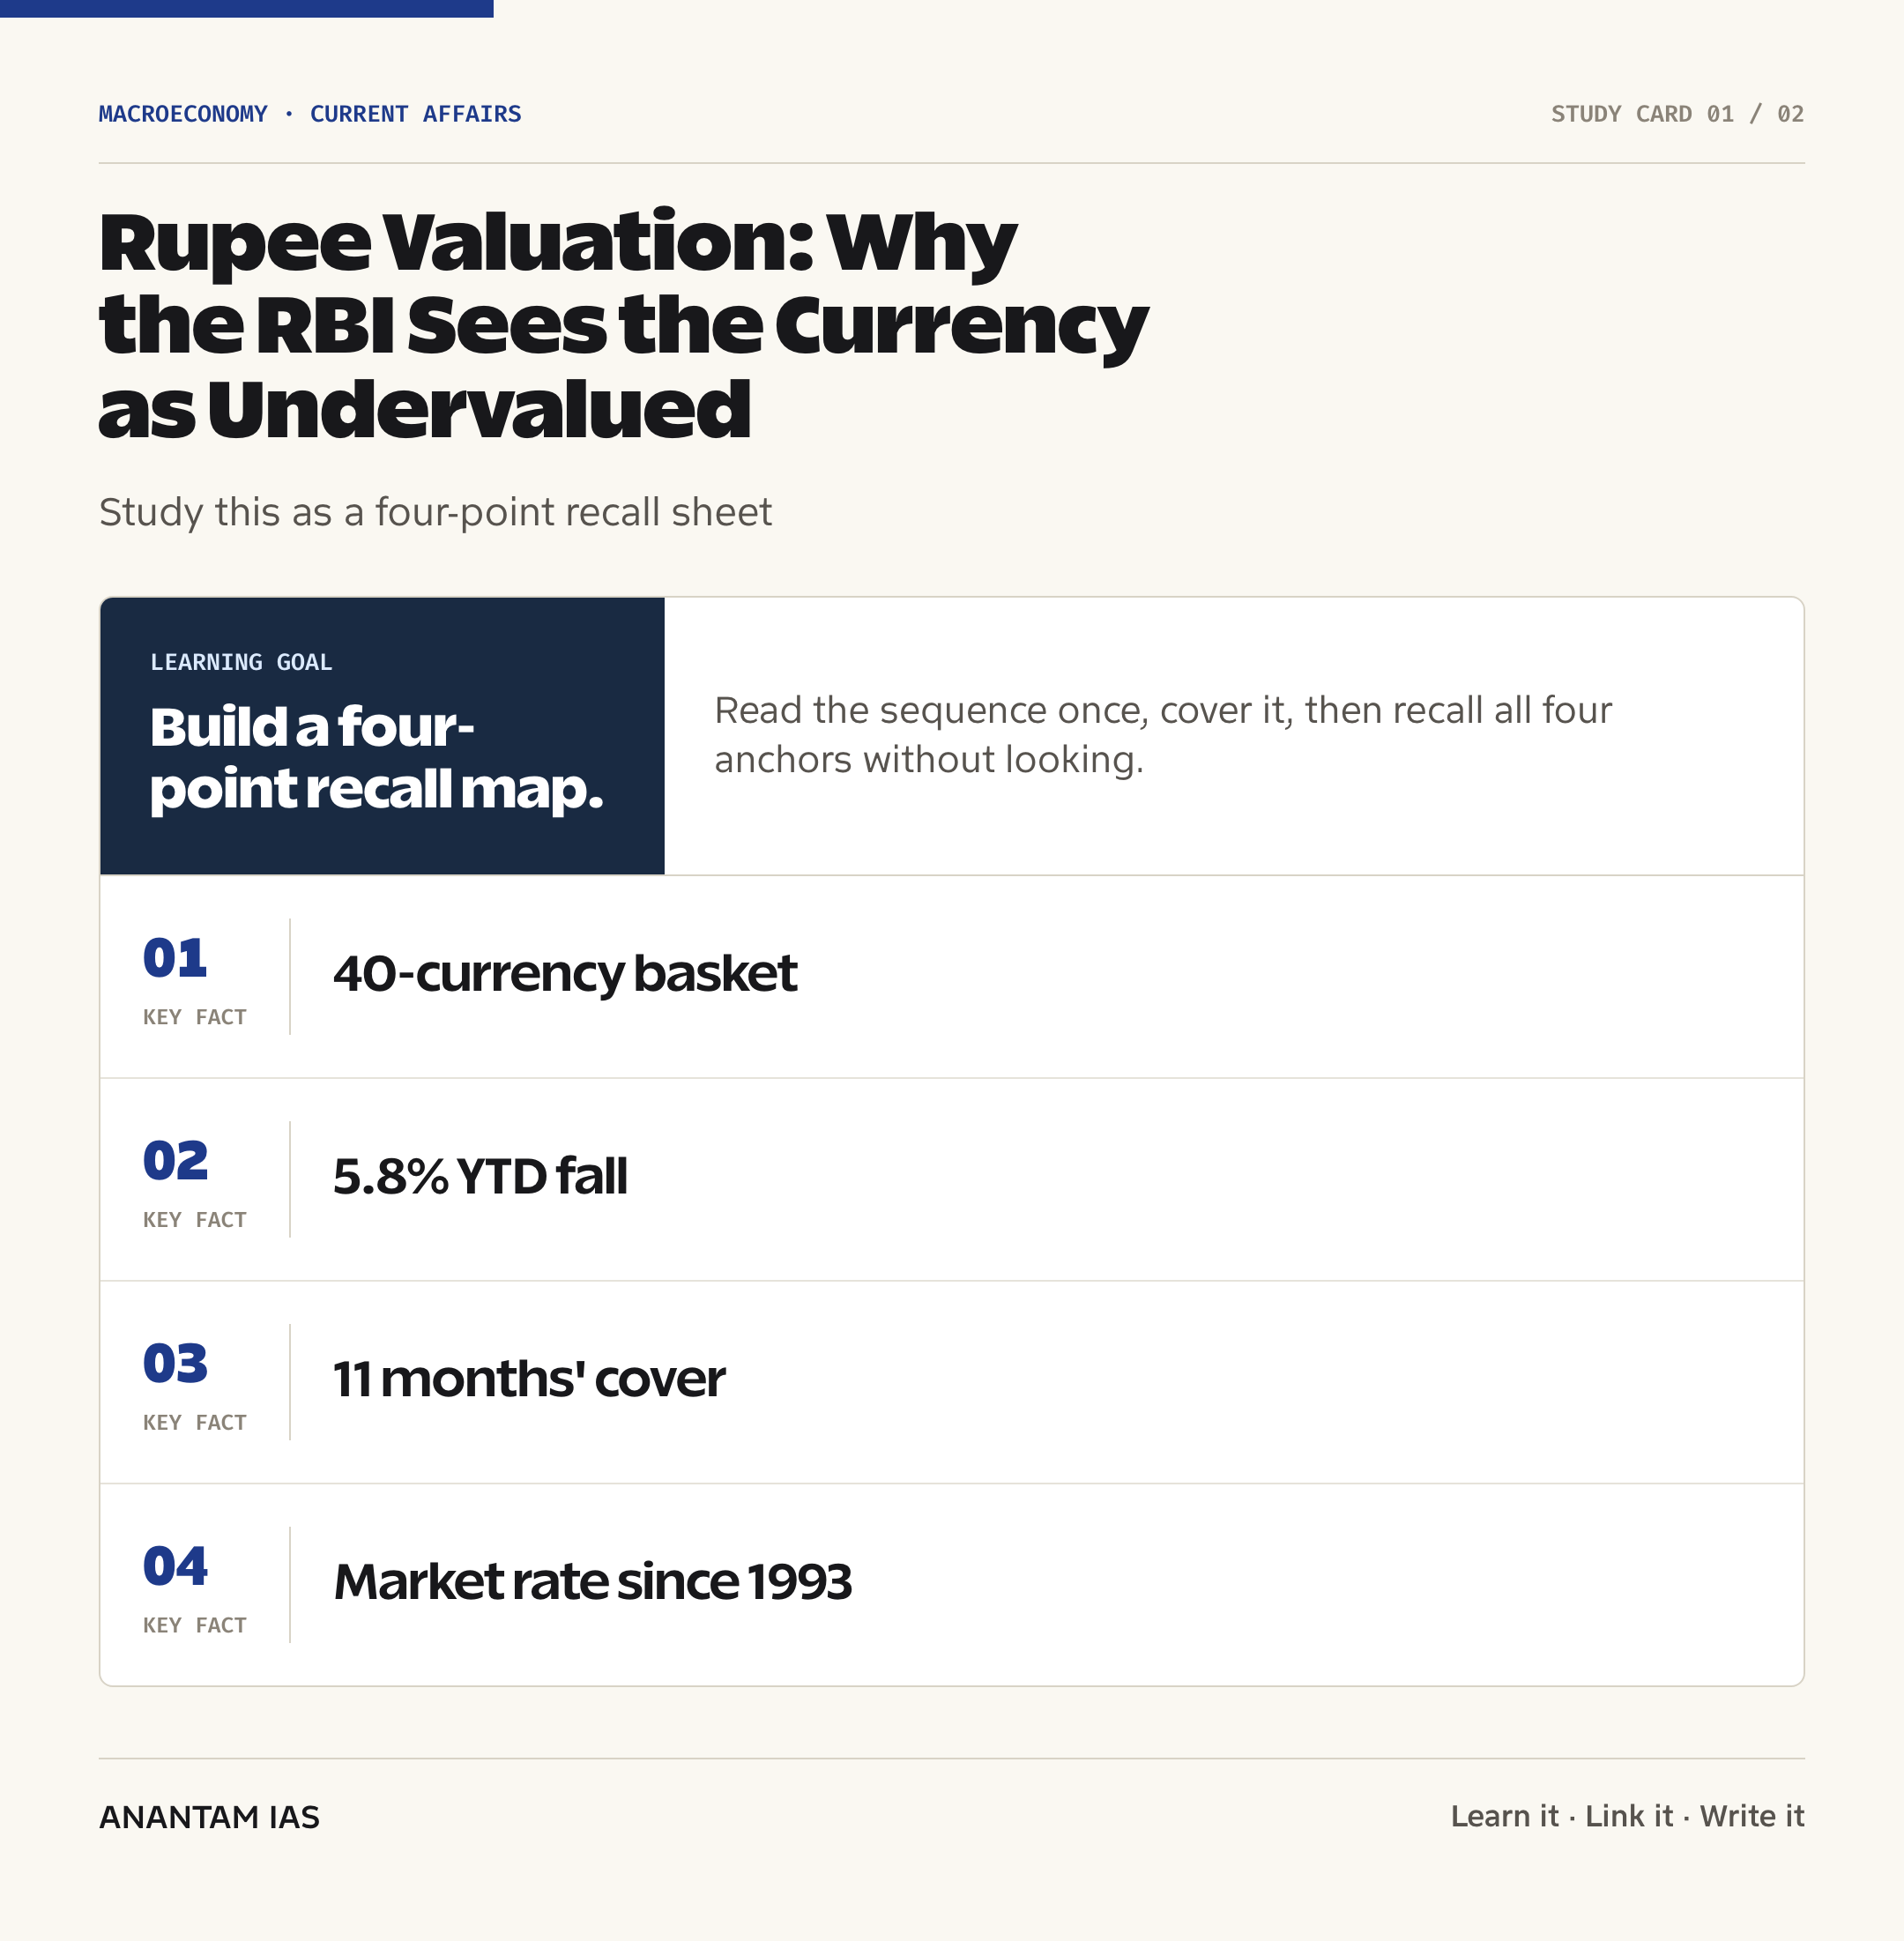
- The rupee had depreciated about 5.8% during 2026 by the time of the reported remarks, amid elevated crude prices, geopolitical tension, a stronger dollar and intermittent foreign portfolio outflows.
- The Governor referred to both the nominal exchange rate and the Real Effective Exchange Rate, or REER, rather than relying only on the bilateral rupee-dollar quotation.
- The assessment rests on a possible gap between the rupee’s market value and India’s growth, inflation, reserves and external-sector fundamentals.
- The Hindu noted that India’s foreign-exchange reserves still offered roughly 11 months of import cover, providing a buffer against external shocks.
- An undervaluation judgment is an economic assessment, not a promise that the currency will appreciate immediately or that the RBI will defend a particular level.
The development matters in the context of:
- Currency valuation matters in the context of export competitiveness, because a cheaper rupee can reduce the foreign-currency price of Indian goods if firms pass the change through.
- It also matters for imported inflation: India pays for crude oil, fertilisers, electronics and several industrial inputs in foreign currency.
- Sharp currency moves affect the Balance of Payments, foreign portfolio flows, external debt servicing and the RBI’s use of reserves.
- The issue tests the policy trade-off between allowing a market-determined adjustment and preventing a disorderly loss of confidence.
UPSC Relevance
Prelims Relevance
- NEER is a trade-weighted geometric average of bilateral nominal exchange rates; it does not adjust for inflation differences.
- REER adjusts NEER for relative prices or costs between India and its trading partners, giving a broader measure of external price competitiveness.
- In the RBI’s published indices, an increase in NEER or REER indicates appreciation of the rupee, while a decrease indicates depreciation.
- The RBI publishes a 40-currency trade-weighted basket with 2015-16 as its stated base, alongside a narrower six-currency series.
- An index base of 100 is a comparison point, not an immutable fair value; the basket, weights, price index and base period shape the reading.
- India moved to a market-determined unified exchange rate in March 1993 after the transitional Liberalised Exchange Rate Management System.
- Under Section 40 of the RBI Act, 1934, the RBI may buy or sell foreign currency to authorised persons.
- When the RBI buys foreign exchange, it normally injects rupee liquidity; when it sells foreign exchange, it absorbs rupee liquidity, unless the liquidity effect is offset.
- Foreign-exchange reserves include foreign currency assets, gold, Special Drawing Rights and India’s reserve-tranche position with the IMF.
- Read REER with the current account, capital flows, reserves and productivity; it cannot by itself predict the next movement of the rupee.
Mains Relevance
GS Paper 3
- Exchange-rate valuation, external-sector stability, inflation, trade competitiveness and the management of foreign-exchange reserves.
- Transmission of crude-oil prices, dollar strength and foreign portfolio outflows to the rupee, the current account and domestic prices.
- Limits of central-bank intervention under a market-determined but actively managed exchange-rate framework.
GS Paper 2
- Institutional credibility and transparent communication by an independent central bank during episodes of global financial stress.
Essay
- A nation’s currency is an economic price, not a badge of national strength.
- Resilience lies in absorbing shocks without allowing temporary volatility to become lasting instability.
Background and Context
What Currency Undervaluation Means
Undervaluation describes a market exchange rate that is weaker than an estimated equilibrium value supported by economic fundamentals.
- The relevant benchmark is not simply yesterday’s rate or a politically preferred number; it is an estimated equilibrium exchange rate consistent with sustainable growth, inflation, productivity and external balances.
- A rupee can weaken in the market because demand for dollars rises during an oil shock or because investors reduce emerging-market exposure, even when India’s domestic fundamentals have not worsened to the same degree.
- The gap between market price and equilibrium is model-dependent. Different assumptions about productivity, capital flows, fiscal policy and the sustainable current-account balance can yield different estimates.
- Undervaluation is also distinct from depreciation: depreciation describes a fall in market value, while undervaluation judges whether the resulting level is weaker than fundamentals warrant.
- A currency judged undervalued can stay weak for months if global risk aversion, dollar demand or geopolitical uncertainty persists; valuation is not a short-term forecast.
- The Governor’s language should be read as a macro-financial diagnosis, not as a guaranteed trading signal or a formal exchange-rate target.
Nominal Rate, NEER and REER
The three measures answer different questions about the rupee’s external value.
- The bilateral USD/INR rate answers how many rupees buy one US dollar; it is highly visible but says nothing directly about movements against the euro, yen, pound or renminbi.
- NEER combines bilateral rates against a currency basket using trade weights, reducing the risk of mistaking a dollar-specific move for a broad-based rupee move.
- REER then adjusts NEER for the inflation differential between India and its trading partners. If Indian prices rise faster, part of a nominal depreciation may be offset in real competitiveness terms.
- The Bank for International Settlements describes REER as NEER adjusted for relative consumer prices and notes that a rising real index represents appreciation and weaker international price competitiveness.
- The RBI states that REER is better suited to tracking currency movement over time than declaring a precise fair-value level at one point because the base year, weights, basket and price measure involve judgment.
- This caution prevents a common error: a reading below the base value of 100 shows depreciation relative to that base under the chosen construction, but does not mechanically prove a specific percentage of fundamental undervaluation.
Why the RBI's Assessment Is Plausible
The RBI appears to see temporary external pressures as larger than the deterioration, if any, in India’s underlying economic capacity.
- India remained among the faster-growing major economies, with growth above 6%, while inflation had moderated from recent highs; these conditions do not by themselves point to a deep loss of currency value.
- Foreign-exchange reserves offering about 11 months of import cover gave the country capacity to meet external payments and smooth disorderly market moves.
- The rupee nevertheless faced pressure from elevated crude-oil prices, geopolitical risks, broad dollar strength and intermittent FPI outflows, all of which raise spot demand for foreign currency.
- Portfolio flows can reverse much faster than domestic output or productivity. A risk-off episode may cause a temporary overshoot, where the exchange rate moves farther than medium-term fundamentals justify.
- India’s services exports and remittances support the current account even when the merchandise trade account is in deficit; see the broader Balance of Payments framework for how these flows interact.
- The RBI’s view is still contestable because the equilibrium rate also depends on oil dependence, trade deficits, global interest-rate differentials and the durability of FDI and FPI inflows.
Trade Competitiveness and Its Limits
A weaker real exchange rate can aid exporters, but the benefit is neither automatic nor costless.
- Exporters receiving dollars may earn more rupees per unit of foreign revenue, while a lower REER can improve price competitiveness against firms in partner economies.
- The gain depends on price elasticity of demand: foreign buyers must respond to lower relative prices by purchasing enough additional Indian output.
- Many exporters import energy, machinery, electronics or intermediate goods. A weaker rupee raises these input costs and can reduce the apparent export advantage.
- Firms may keep the currency gain as margin instead of lowering foreign-currency prices, and supply constraints, logistics costs and product quality can matter more than exchange rates.
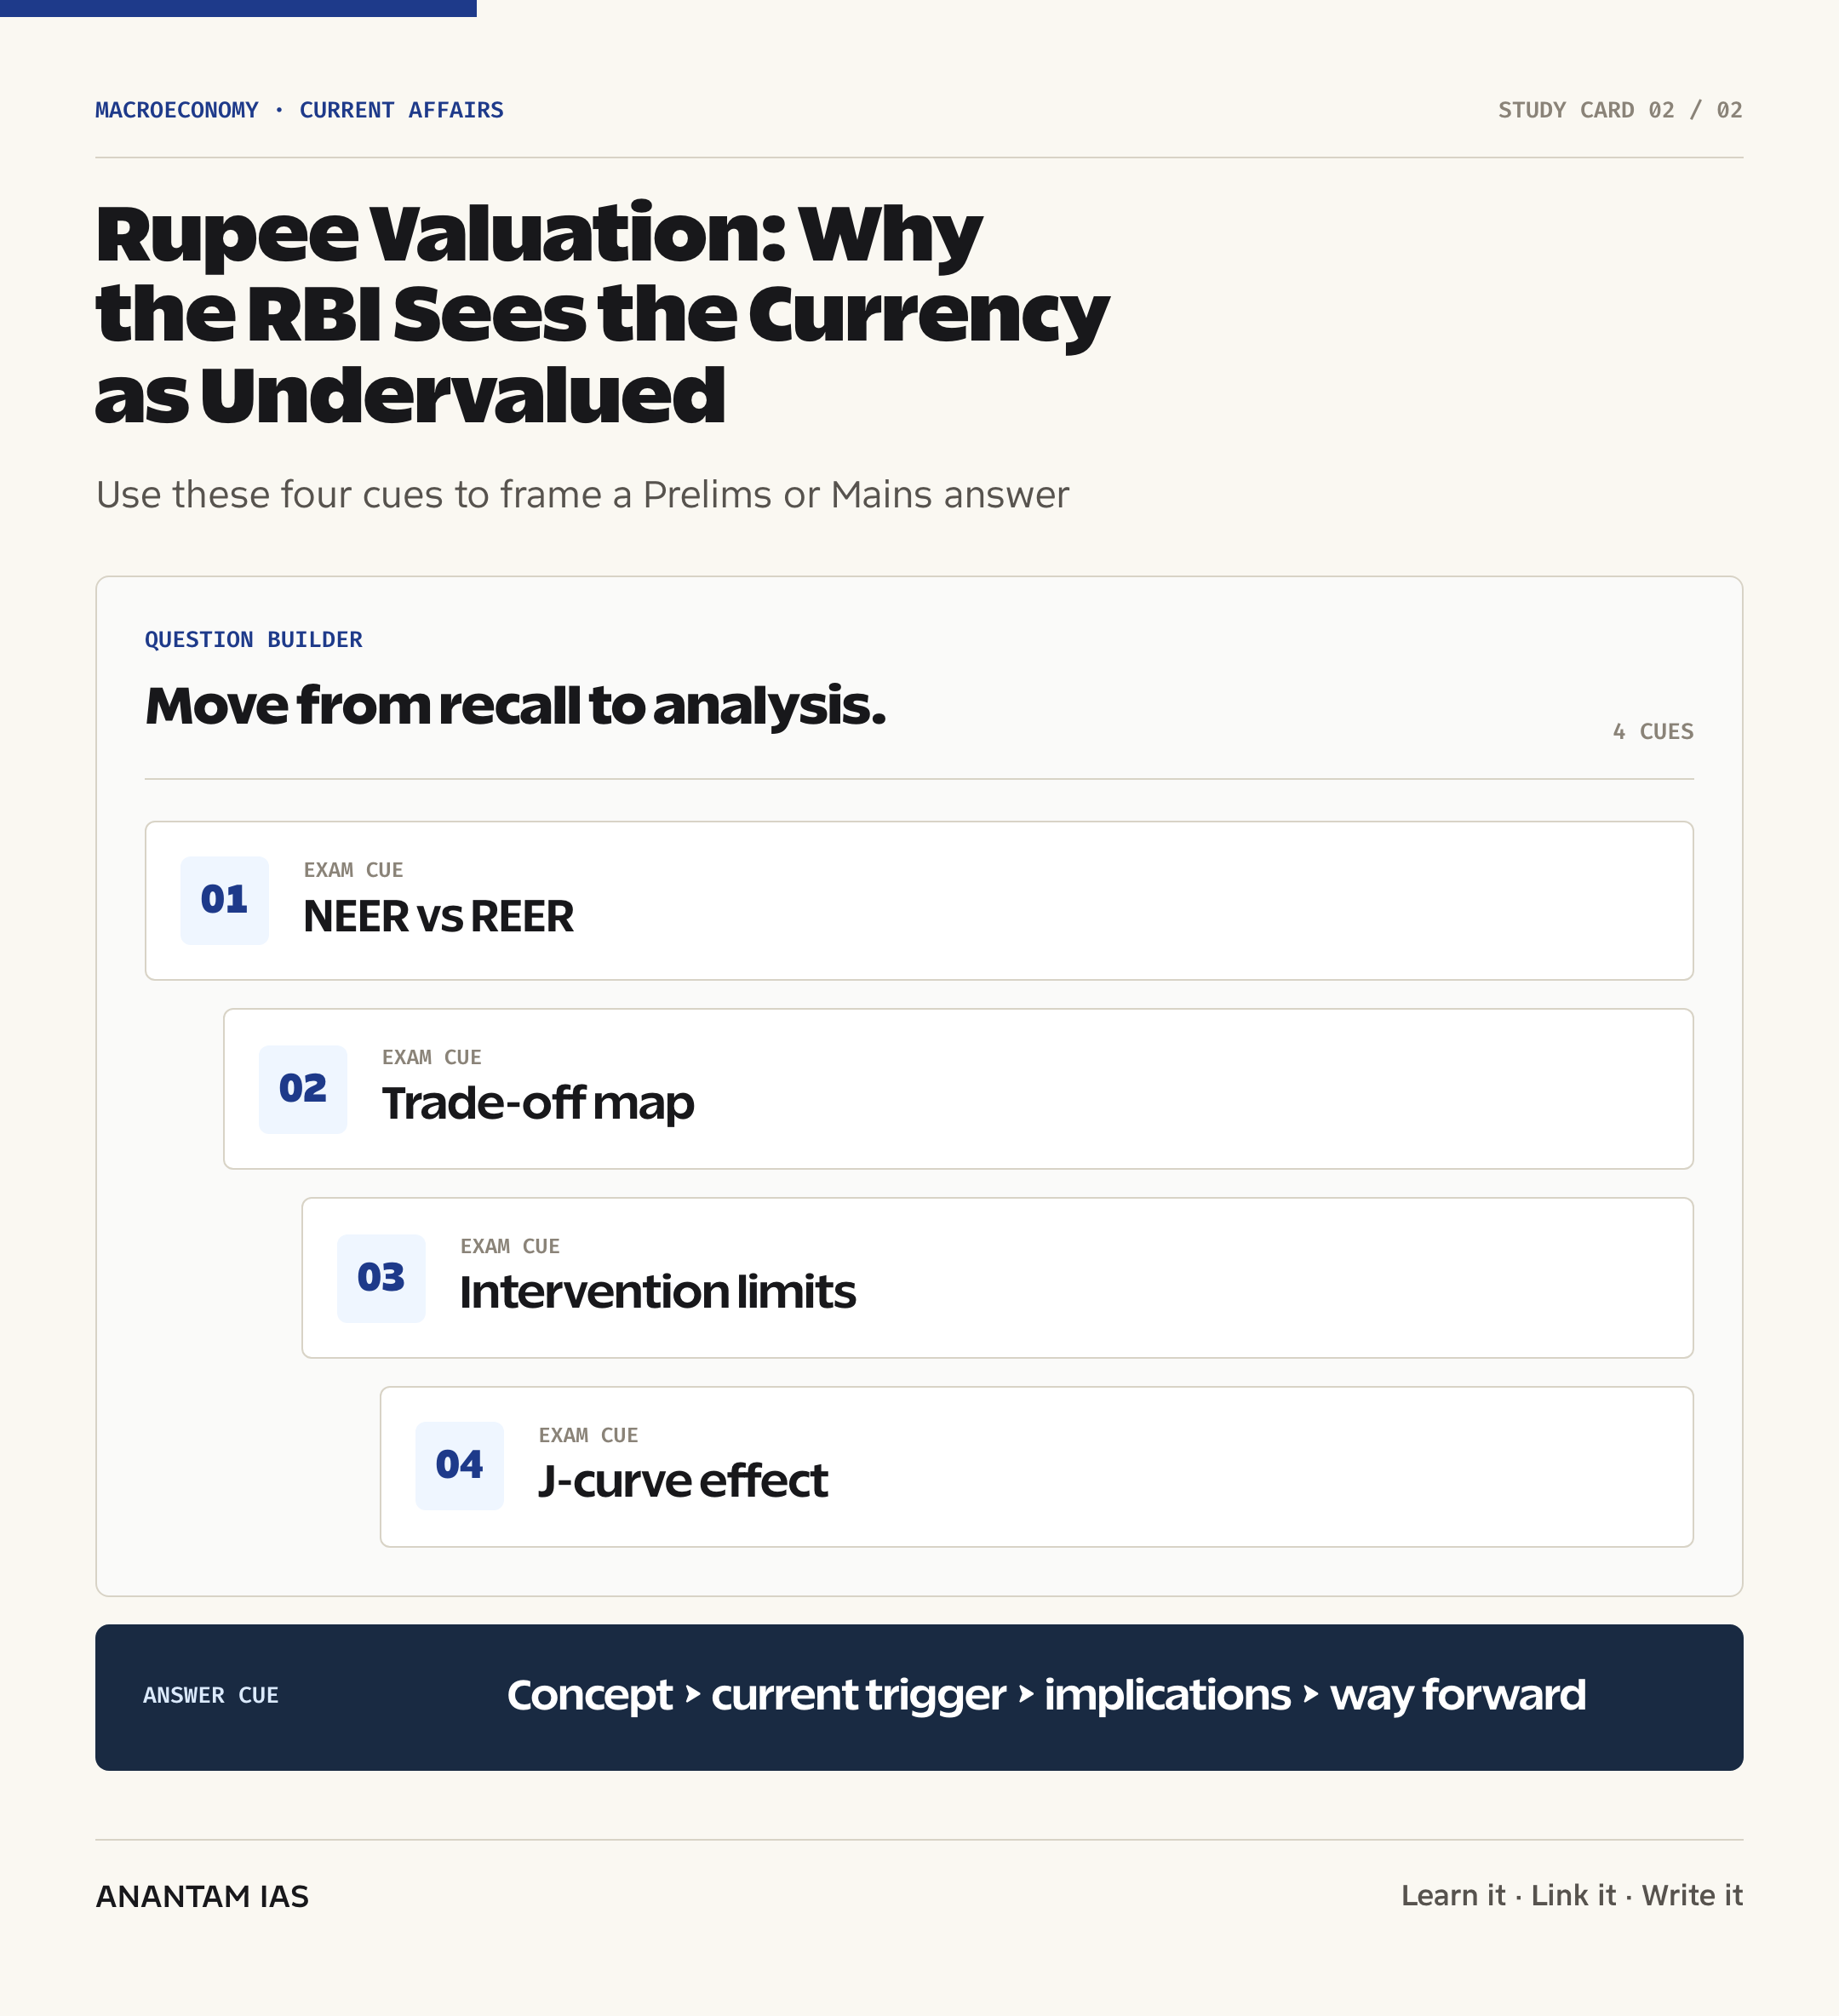
- The J-curve effect explains why the trade balance may initially worsen after depreciation: import contracts and quantities adjust slowly while the rupee cost of imports rises immediately.
- Sustained export performance needs productivity, reliable infrastructure, trade facilitation and market access; an undervalued currency cannot replace structural competitiveness.
Imported Inflation and Balance-Sheet Risks
The same depreciation that may support exports can transmit external costs into households, firms and government finances.
- Crude oil and other dollar-priced imports become more expensive in rupees, creating imported inflation through fuel, freight, fertiliser and production costs.
- Higher import values can widen the merchandise trade deficit and add pressure to the current account, especially when export volumes respond slowly.
- Companies or governments with unhedged foreign-currency debt face a larger rupee repayment burden, a channel known as the balance-sheet effect.
- Inflation can erode the real depreciation that initially improved competitiveness: if domestic prices rise, REER may appreciate even without a stronger nominal rupee.
- Currency weakness can influence inflation expectations and constrain monetary easing, connecting the foreign-exchange market with the Monetary Policy Committee.
- For the inflation channel in a recent Indian setting, compare the note on wholesale and imported inflation.
How and Why the RBI Intervenes
India’s exchange rate is market-determined, but the RBI can act when market functioning becomes disorderly.
- The RBI can sell dollars in the spot market to meet temporary excess demand, or operate through forwards and swaps to influence liquidity and future dollar availability.
- A dollar sale reduces foreign assets and absorbs rupee liquidity; a dollar purchase adds reserves and injects rupees unless the RBI conducts sterilisation through separate liquidity operations.
- Intervention can slow panic, reduce one-way speculation and buy time for price discovery, but persistent defence of an arbitrary level can deplete foreign-exchange reserves.
- The RBI’s official position is to maintain orderly conditions and curb excessive volatility rather than fix a rate. This preserves the exchange rate’s role as a shock absorber.
- Raising interest rates solely to support the currency can attract capital at the cost of domestic credit and growth; using reserves too aggressively can weaken the external buffer.
- India’s reserve position and import cover are examined in the RBI external-sector buffer note, while remittances are covered in this current-affairs explainer.
Capital Flows and Exchange-Rate Overshooting
Financial flows can move the rupee more rapidly than trade quantities or domestic productive capacity can adjust.
- Foreign portfolio investment responds quickly to global interest rates, dollar funding costs, risk appetite and relative asset returns; withdrawals create immediate demand for foreign currency.
- Foreign direct investment is usually more stable because it is tied to factories, businesses and long-term ownership, but net FDI can weaken when outward investment and repatriation rise.
- A narrower interest-rate differential with advanced economies may reduce the reward for holding rupee assets, while a broad safe-haven dollar move can pressure many emerging-market currencies together.
- Exchange rates are asset prices and incorporate expectations. When investors anticipate continuing outflows, they may demand dollars early, causing overshooting beyond the adjustment required by current trade flows.
- Remittances and services-export receipts provide recurring dollar supply, but their stabilising effect can be temporarily outweighed by large portfolio sales or an abrupt increase in the oil import bill.
- A sound assessment separates a temporary liquidity shock from a structural loss of competitiveness. The policy response to the first is market smoothing; the response to the second requires productivity and external-balance reform.
Way Forward
Keep the Exchange Rate Flexible
- Allow the rupee to reflect changing trade and capital-flow conditions while intervening against abrupt, illiquid or speculative moves.
- Avoid communicating a precise defence line that invites markets to test the RBI’s commitment and reserves.
- Publish clear data on intervention, forward positions and reserve adequacy with appropriate lags to strengthen policy credibility.
Reduce External Vulnerabilities
- Diversify energy sources, raise domestic renewable capacity and improve efficiency to reduce the exchange-rate sensitivity of the oil import bill.
- Deepen export capabilities in manufacturing and services through logistics reform, quality standards and participation in global value chains.
- Prefer stable, long-horizon FDI and deepen domestic financial markets so temporary FPI exits cause less disruption.
- Encourage prudent hedging of foreign-currency liabilities by banks and companies to contain the balance-sheet channel.
Use a Dashboard, Not One Indicator
- Assess valuation through NEER, REER, the current account, capital flows, reserves, inflation and productivity rather than a bilateral exchange rate alone.
- Compare alternative baskets and equilibrium models because a base-year index cannot independently reveal a currency’s exact fair value.
- Coordinate monetary, fiscal, trade and energy policy so the response addresses the source of pressure without sacrificing price stability or growth.
Conclusion
The RBI’s description of the rupee as undervalued is best understood as a judgment that recent nominal and real depreciation has overshot India’s medium-term fundamentals. It does not turn a weak rupee into an unqualified advantage, nor does it commit the central bank to a particular reversal.
For policy, the objective is an orderly and credible adjustment. A flexible exchange rate can absorb global shocks, while reserves, sound inflation management, stable capital inflows and stronger trade capacity keep that flexibility from becoming instability.
UPSC Practice Questions
Prelims MCQ 1
With reference to effective exchange rates, consider the following statements:
- NEER adjusts a trade-weighted basket of nominal exchange rates for inflation differentials.
- REER incorporates relative prices or costs between the home economy and its trading partners.
- In the RBI’s published indices, an increase in REER indicates real appreciation of the rupee.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 2 and 3 are correct. NEER is the nominal trade-weighted measure; REER, not NEER, makes the relative-price adjustment. A rise in the RBI’s REER index indicates real appreciation.
Prelims MCQ 2
Which one of the following best describes the RBI’s stated objective in the foreign-exchange market?
(a) Maintaining a permanently undervalued rupee to subsidise exports (b) Fixing the rupee-dollar rate at a pre-announced level (c) Containing excessive volatility and preserving orderly market conditions (d) Keeping the REER index exactly at its base value
Answer: (c) Containing excessive volatility and preserving orderly market conditions
Explanation:
India has a market-determined exchange rate. The RBI may intervene in spot, forward or swap markets to smooth disorderly movements, but it says it does not defend a fixed rate or band.
UPSC Mains Questions
- The Real Effective Exchange Rate is useful for reading currency competitiveness, but it cannot by itself establish a currency’s fair value. Explain the construction and limitations of REER and show how it should be combined with other external-sector indicators. (250 words)
- A weaker rupee can improve export competitiveness while worsening imported inflation and corporate balance-sheet risks. Analyse these competing channels in the Indian context and identify the conditions under which depreciation may improve the trade balance. (250 words)
- The RBI seeks orderly foreign-exchange markets rather than a fixed exchange rate. Discuss the instruments, liquidity effects and policy trade-offs involved in intervention under India’s market-determined exchange-rate framework. (250 words)
Sources: Reserve Bank of India and The Hindu.
Frequently Asked Questions
What does an undervalued rupee mean?
It means the rupee’s market exchange rate is judged weaker than an estimated equilibrium level supported by growth, inflation, productivity and external balances. The judgment is model-dependent. It does not mean the currency must appreciate immediately, because oil prices, dollar strength, capital outflows and risk aversion can keep it weak.
How is REER different from USD/INR?
USD/INR is one bilateral nominal rate. REER combines the rupee’s movement against a trade-weighted basket of partner currencies and adjusts it for relative inflation. It gives a broader view of price competitiveness, but its reading depends on the basket, weights, base period and price index selected.
Does REER below 100 prove undervaluation?
No. A value below 100 shows real depreciation relative to the chosen base period under that index’s methodology. The BIS and RBI both caution that the base value is not an automatic fair-value threshold. A valuation judgment needs equilibrium models and evidence from the current account, capital flows, productivity and reserves.
Why can a weaker rupee raise inflation?
India pays for crude oil, fertilisers, electronics and many industrial inputs in foreign currency. Depreciation raises their rupee cost, which can pass through to fuel, freight, farm inputs and manufactured goods. This imported inflation can also erode the initial competitiveness gain from the weaker nominal exchange rate.
Does the RBI target a rupee level?
The RBI says it does not target a specific exchange rate or band. It intervenes to contain excessive volatility, correct temporary demand-supply mismatches and maintain orderly markets. Defending an arbitrary level for long periods could consume reserves, distort price discovery and complicate domestic liquidity and monetary policy.
Can undervaluation automatically boost exports?
No. Export gains depend on foreign demand, domestic supply capacity, imported-input content and whether firms pass currency gains into prices. Contracts adjust with a lag, so the trade balance may first worsen through the J-curve effect. Productivity, logistics, quality and market access remain more durable sources of competitiveness.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.