Context:
Union Home and Cooperation Minister Amit Shah launched two new digital initiatives — Sahakar Digi Pay and Sahakar Digi Loan — during the Co-Op Kumbh 2025 conference organized by the National Federation of Urban Cooperative Banks and Credit Societies (NAFCUB). The move aims to digitally empower urban cooperative banks (UCBs) and expand financial inclusion.
UPSC Relevance:
Economy Prelims
UPSC PYQ:
Q. With reference to ‘Urban Cooperative Banks’ in India, consider the following statements:
- They are supervised and regulated by local boards set up by the State Governments.
- They can issue equity shares and preference shares.
- They were brought under the purview of the Banking Regulation Act, 1949 through an Amendment in 1966.
Which of the statements given above is/are correct?
(a) 1 only
(b) 2 and 3 only
(c) 1 and 3 only
(d) 1, 2 and 3
Key Announcements:
1. Target – One Urban Cooperative Bank per City
- The government aims to establish one urban cooperative bank (UCB) in every Indian city with a population above 2 lakh within five years.
- The goal is to increase cooperative credit access and strengthen grassroots-level financial institutions.
2. Two New Digital Apps
- Sahakar Digi Pay: Enables even small UCBs to offer digital payment services.
- Sahakar Digi Loan: Facilitates digital lending and promotes paperless, transparent loan processing.
- These apps help cooperatives compete with commercial banks and fintech platforms by embracing digitization.
About Cooperative banks:
Cooperative Banks are the financial institutions that are owned and run by their customers and operate on the principle of one person one vote.
- The bank is governed by both banking and cooperative legislation, as they are registered under the Cooperative Society Act, 1965 and regulated by NABARD & RBI.
- They operate in both rural as well as urban areas and provide credit to borrowers and businesses.
- Cooperative Banks offer a range of services like accepting deposits and granting loans to the members and even non-members. The members are the owners and customers of the bank at the same time.
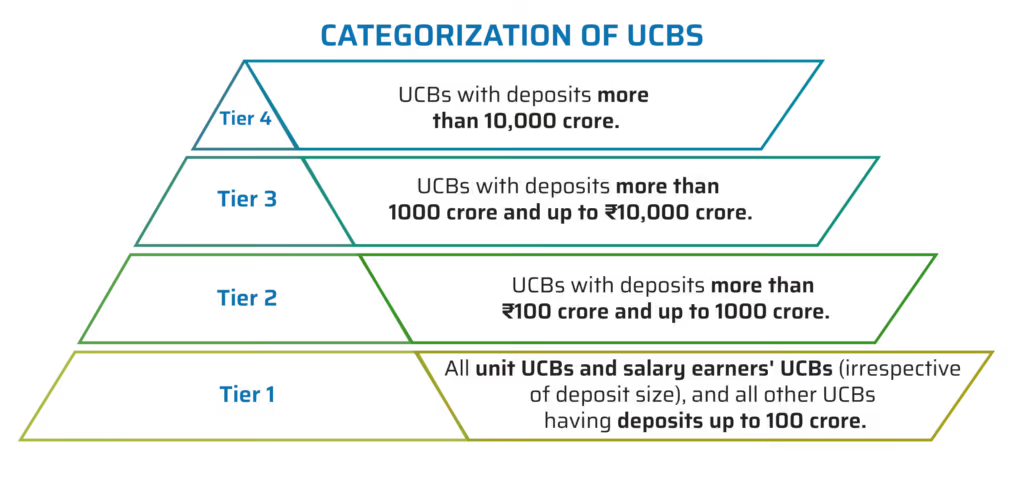
Urban Co-operative Banks:
- Urban Cooperative Banks (UCBs) are a subset of cooperative banks in India that operate primarily in urban and semi-urban areas.
- The first urban cooperative credit society was established in 1889 in Baroda (Anyonya Sahakari Mandali).
- Currently, they are registered as cooperative societies under the respective State Cooperative Societies Acts (for single-state operations) or the Multi-State Cooperative Societies Act, 2002 (for operations across multiple states
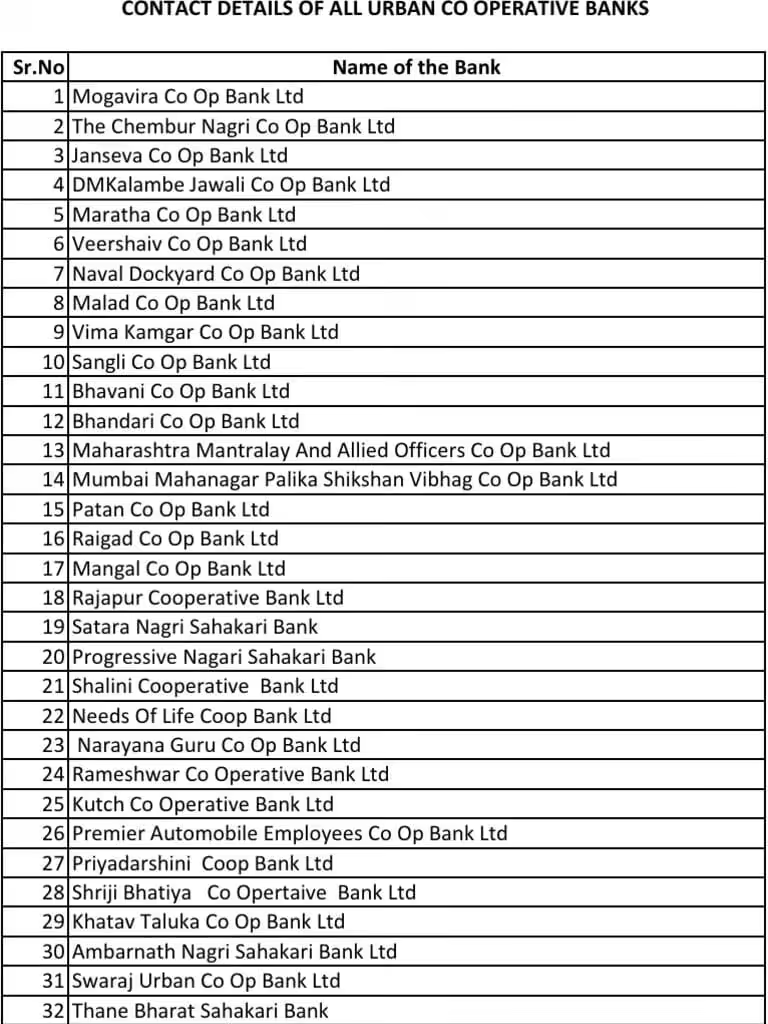
List of Urban-Co-operative banks:
Significance:
- Financial Inclusion:
- Urban Cooperative Banks play a vital role in extending banking services to small borrowers, micro-enterprises, and lower-income households in urban and semi-urban areas, thereby deepening financial inclusion.
- Community-Based Focus:
- Operating within defined localities, UCBs possess an intimate understanding of community needs, enabling them to design and deliver customized financial solutions suited to local economic conditions.
- Priority Sector Lending (PSL):
- To strengthen their developmental role, UCBs are mandated to allocate 65% of their total lending to the Priority Sector in FY 2024-25, with the target rising to 75% by March 2026, aligning them more closely with national inclusion objectives.
- Support for Non-Agricultural Development:
- UCBs cater primarily to the non-agricultural sector, meeting the credit needs of small traders, artisans, and service-sector enterprises in urban and semi-urban regions.
- Evolving Lending Scope:
- Until 1996, UCBs were restricted to lending for non-agricultural purposes; however, this distinction has since been removed, allowing them to extend credit across diverse sectors to support holistic urban economic growth.
Challenges:
| Challenge | Explanation / Data | Impact / Consequence |
|---|---|---|
| 1. Weak Governance and Fraud Risks | Many UCBs face political interference, nepotism, and financial mismanagement, leading to fraud and inefficiency. ➤ 24 UCB licenses were cancelled during 2023–24. | Loss of depositor confidence; deterioration in institutional credibility and operational discipline. |
| 2. Competition from Commercial Banks & Fintechs | UCBs’ share in total banking assets declined from 3.8% (2017) to 2.5% (March 2024) due to competition from technologically advanced banks and fintechs. | Shrinking market share and declining relevance in the urban credit ecosystem. |
| 3. High Non-Performing Assets (NPAs) | Gross NPAs of UCBs stood at 8.8% (March 2024), reflecting poor credit appraisal and recovery systems. | Erosion of profitability and weakening of financial health. |
| 4. Capital Adequacy Shortfalls | UCBs have limited access to capital markets, restricting their ability to meet RBI’s regulatory capital norms and expand operations. | Inability to absorb financial shocks or undertake business growth. |
| 5. Regulatory Non-Compliance | Subject to dual regulation by the RBI and State Cooperative Authorities, creating overlapping jurisdictions and compliance confusion. | Regulatory delays, weak supervision, and operational inefficiencies. |
| 6. Technological Obsolescence | Many UCBs lag in adopting digital banking and core banking systems (CBS) due to financial and technical constraints. | Reduced efficiency, poor customer experience, and inability to compete with fintech innovations. |
Recent Changes:
| Reform / Initiative | Key Features / Description | Objective / Impact |
|---|---|---|
| 1. Banking Regulation (Amendment) Act, 2020 | Empowers RBI to supersede bank boards, restructure managements, and formulate resolution plans for stressed UCBs. | Enhances RBI’s regulatory oversight and ensures timely intervention in cases of mismanagement or insolvency. |
| 2. Revised Prompt Corrective Action (PCA) Framework, 2024 | RBI extended PCA norms to UCBs; sets thresholds for capital adequacy, asset quality, and profitability. PCA enables RBI to intervene early when a bank shows financial stress. | Strengthens prudential regulation and enables early correction to prevent bank failures. |
| 3. Liquidity Support via Umbrella Organization (UO) | Establishment of National Urban Co-operative Finance and Development Corporation (NUCFDC) as an umbrella organization for UCBs. | Provides liquidity backstop, capital support, and technological assistance to smaller cooperative banks. |
| 4. Tiered Regulatory Framework | RBI introduced a four-tier classification of UCBs based on their deposit size, with differentiated regulatory norms. | Allows a risk-based and proportionate regulatory approach, ensuring both flexibility and stability. |
| 5. Liberalized Branch Expansion Policy | UCBs can now open up to 10% (maximum 5) of their existing branches annually without prior RBI approval. | Promotes geographical expansion and greater access to cooperative banking services. |
| 6. Doorstep Banking Services | RBI permitted UCBs to provide doorstep services (cash pick-up, delivery, etc.) to their customers. | Enhances customer convenience, especially for senior citizens and small businesses. |
| 7. One-Time Settlement (OTS) Scheme | UCBs allowed to settle outstanding loans through OTS on lines similar to commercial banks. | Improves loan recovery, reduces NPAs, and strengthens financial health. |
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.