Why in News?
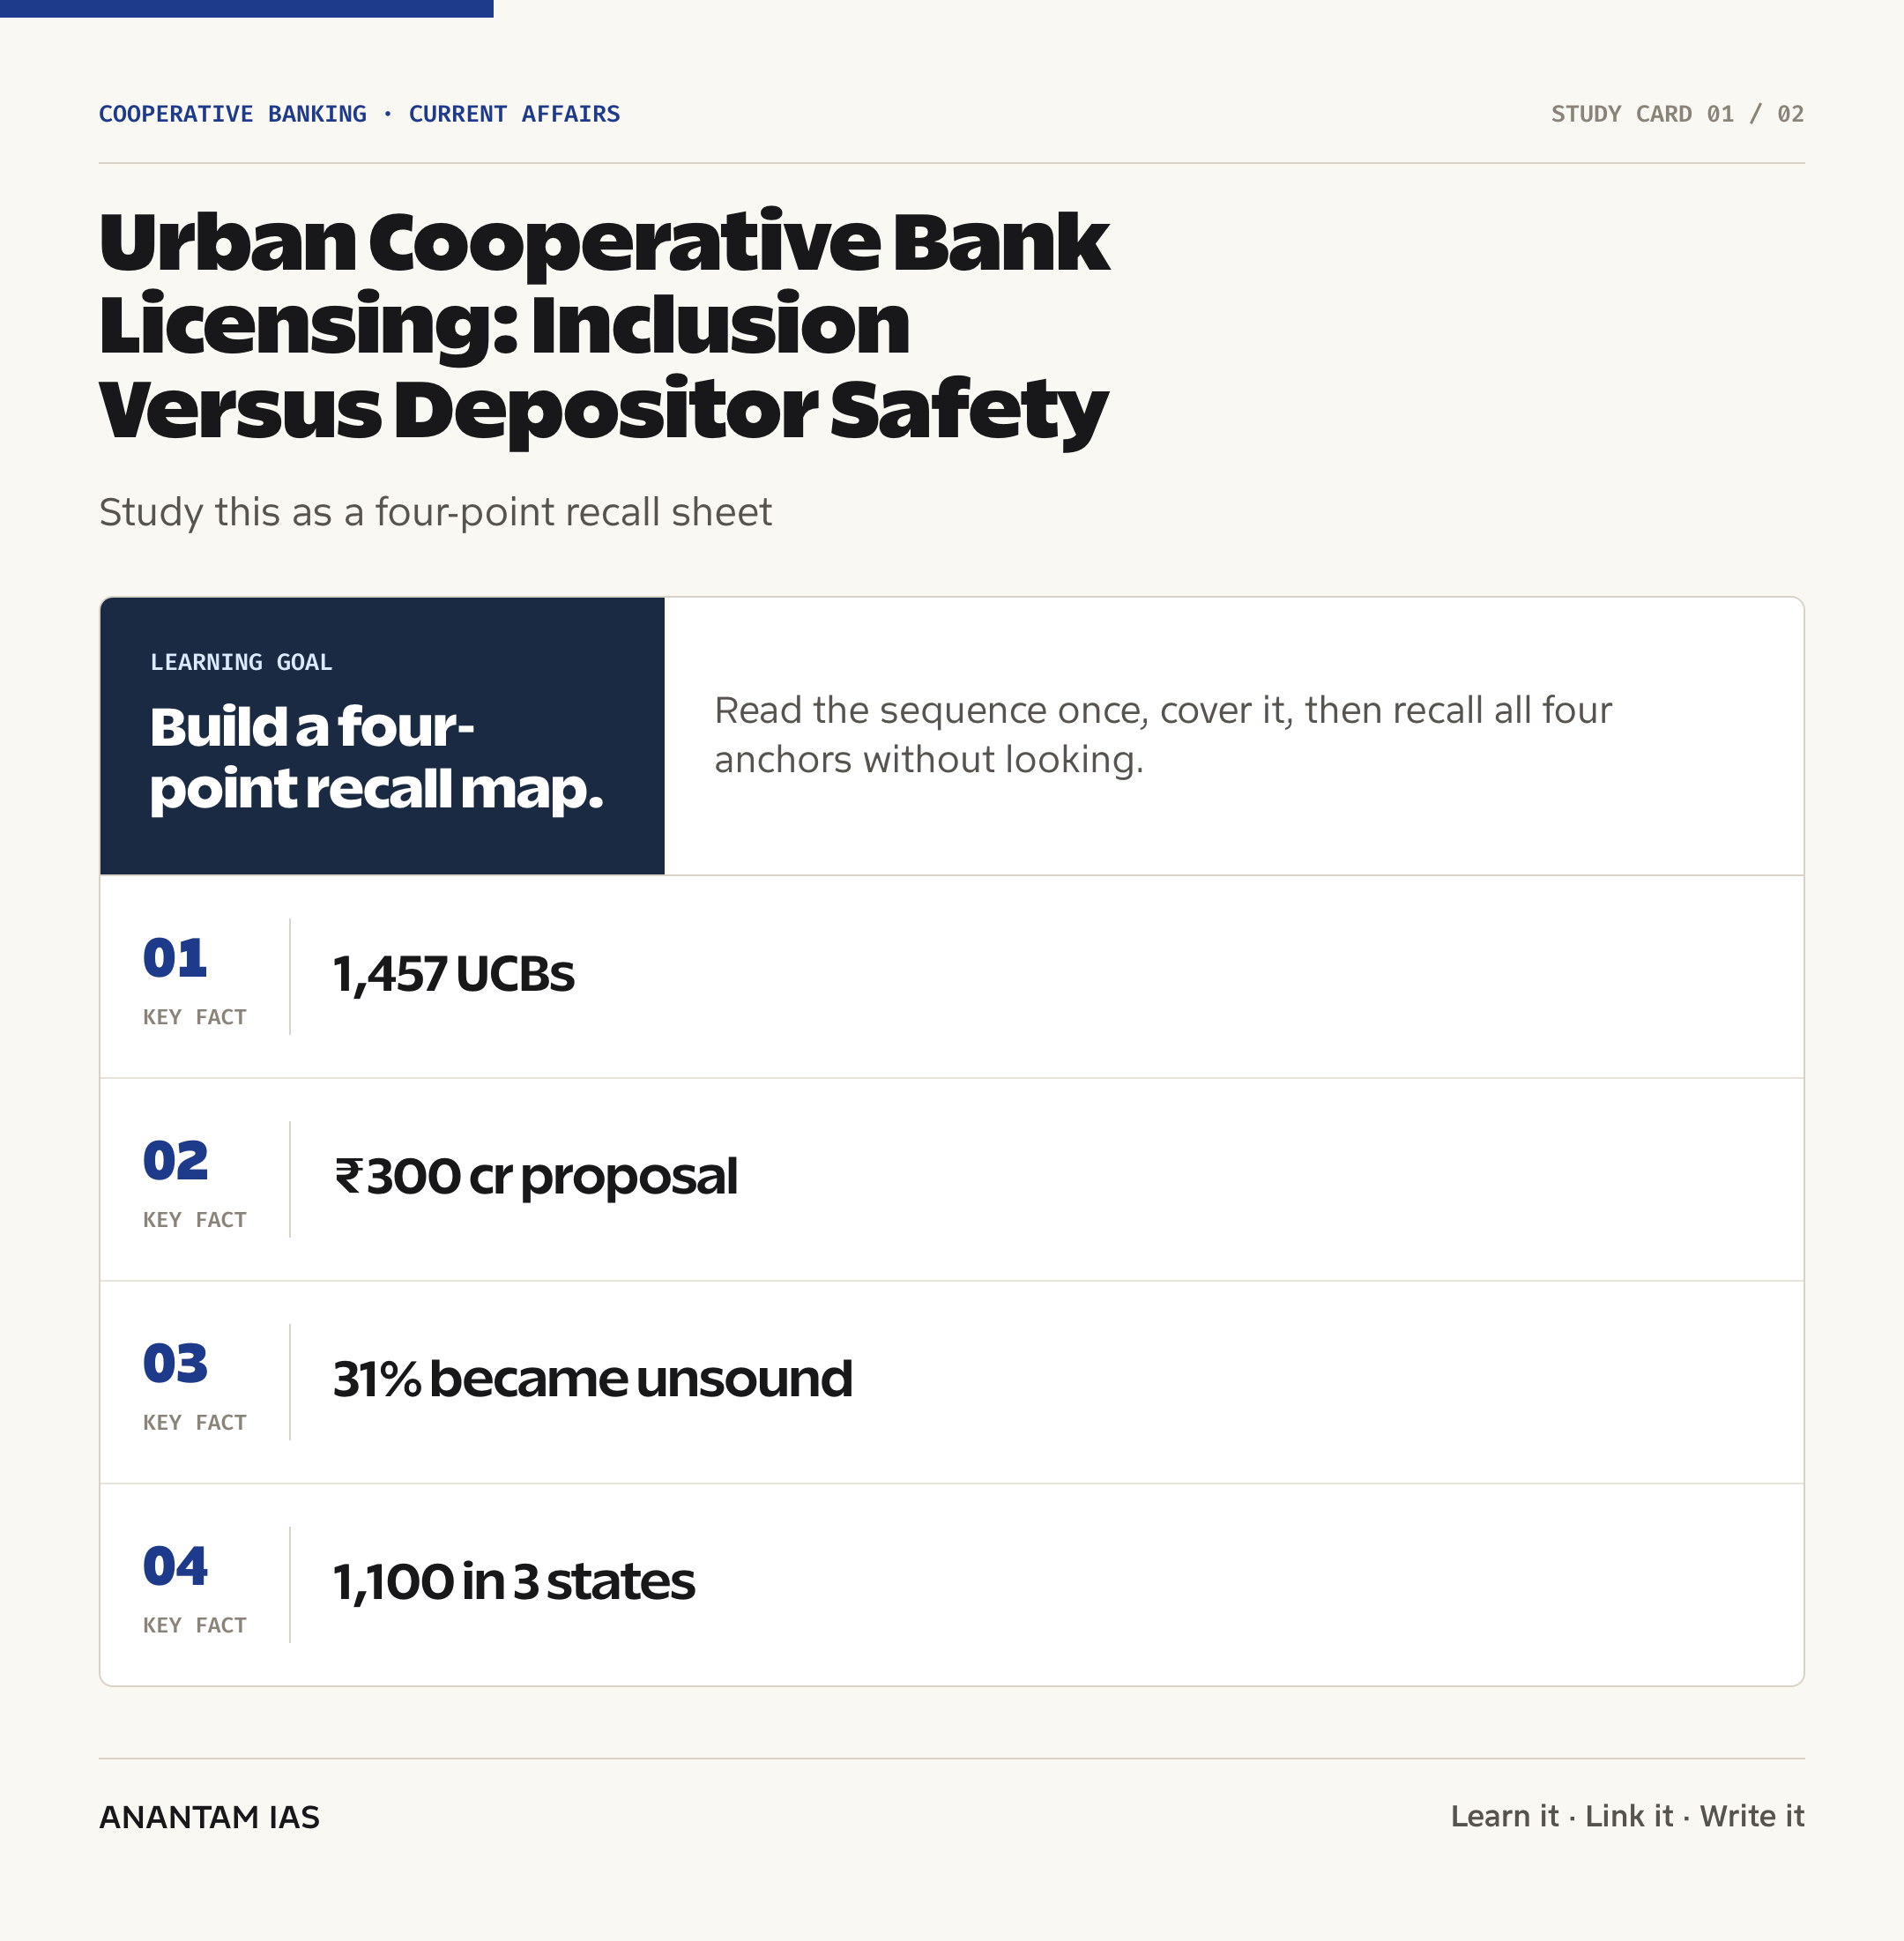
The Ministry of Cooperation has urged the Reserve Bank of India to frame a policy for licensing new urban cooperative banks. The Indian Express reported on 28 July 2026 that Secretary Ashish Kumar Bhutani described wider UCB coverage as a ministry focus, citing the need for cooperative banks in more towns.
This is a policy push, not an RBI decision to grant new licences. RBI issued a discussion paper on 13 January 2026, invited feedback until 13 February and said it would consider detailed draft guidelines after reviewing comments. The licensing window that has remained paused since 2004 has not automatically reopened.
- A speaker at the July event estimated about 1,450 UCBs, with nearly 1,100 located in Maharashtra, Gujarat and Karnataka.
- RBI’s verified statistical baseline counted 1,457 UCBs as of 31 March 2025: 838 in Tier 1, 535 in Tier 2, 78 in Tier 3 and six in Tier 4.
- RBI’s discussion paper tentatively suggested considering large cooperative credit societies with at least ₹300 crore capital, subject to governance, track-record and prudential tests.
- RBI, not the Cooperation Ministry, grants a banking licence under Section 22 read with Section 56 of the Banking Regulation Act, 1949.
- The central tradeoff is between financial inclusion through local member-owned institutions and depositor safety in a sector with a history of small-bank governance failures.
The development matters in the context of:
- This matters in the context of India’s federal division between cooperative-society law and Union control over banking.
- It also tests whether stronger RBI powers after the Banking Regulation (Amendment) Act, 2020 are enough to support cautious new entry.
- The debate isn’t simply more banks versus fewer banks; it is about choosing between new licences, expansion of sound existing UCBs and other financial-inclusion channels.
UPSC Relevance
Prelims Relevance
- An urban cooperative bank is a cooperative society licensed by RBI as a primary cooperative bank to conduct banking business.
- A UCB may be registered under a State Cooperative Societies Act or the Multi-State Cooperative Societies Act, 2002.
- The RBI regulates and supervises UCB banking functions under the Banking Regulation Act, 1949 as applicable to cooperative societies.
- The relevant Registrar of Cooperative Societies or Central Registrar deals with the cooperative entity under State or multi-state law.
- Banking laws were extended to cooperative societies in 1966 through Section 56 of the Banking Regulation Act.
- The Banking Regulation (Amendment) Act, 2020 strengthened RBI powers over governance, audit, capital and resolution of cooperative banks.
- RBI’s four-tier framework classifies UCBs mainly by deposit size: below ₹100 crore; ₹100-1,000 crore; ₹1,000-10,000 crore; and ₹10,000 crore or above.
- Urban cooperative banks are supervised by RBI; State Cooperative Banks and District Central Cooperative Banks are regulated by RBI but supervised by NABARD.
- The DICGC deposit-insurance scheme is mandatory for RBI-licensed commercial and cooperative banks, with cover up to ₹5 lakh per depositor per bank.
Mains Relevance
GS Paper 3
- Role of UCBs in local credit, MSME finance, financial inclusion and competition with small finance banks and NBFCs.
- Bank regulation, capital adequacy, non-performing assets, cyber resilience and depositor protection.
- Balancing proportional regulation for small member-owned banks with common standards for any institution accepting public deposits.
GS Paper 2
- Federal division of powers: State List Entry 32 for cooperative societies and Union List Entry 45 for banking.
- Institutional coordination between RBI, State Registrars, the Central Registrar and the Ministry of Cooperation.
- Cooperative governance, democratic member control and professional banking management.
Essay
- Local ownership can deepen inclusion only when institutions protect public trust.
- In banking, growth without governance transfers private weakness to depositors.
- Cooperation and regulation are complements, not opposites.
Background and Context
What an Urban Cooperative Bank Is
A UCB combines a cooperative legal identity with the privileges and obligations of a licensed bank.
- The institution begins as a cooperative society registered under a State law or the Multi-State Cooperative Societies Act, 2002.
- It becomes a bank only after RBI grants a licence under Section 22 read with Section 56 of the Banking Regulation Act, 1949.
- A cooperative credit society ordinarily mobilises and lends funds within its membership. It cannot present itself as a bank or accept public deposits as banking business without the required RBI licence.
- The cooperative principle of one member, one vote differs from the shareholding-based control common in companies and commercial banks.
- UCBs traditionally serve urban and semi-urban members, local traders, salaried groups, small enterprises and communities that value proximity and relationship-based banking.
- They sit within the wider structure explained in Anantam IAS’s guide to the banking system in India, but they aren’t the same as rural cooperative banks or Primary Agricultural Credit Societies.
Dual Regulation: The Federal Design
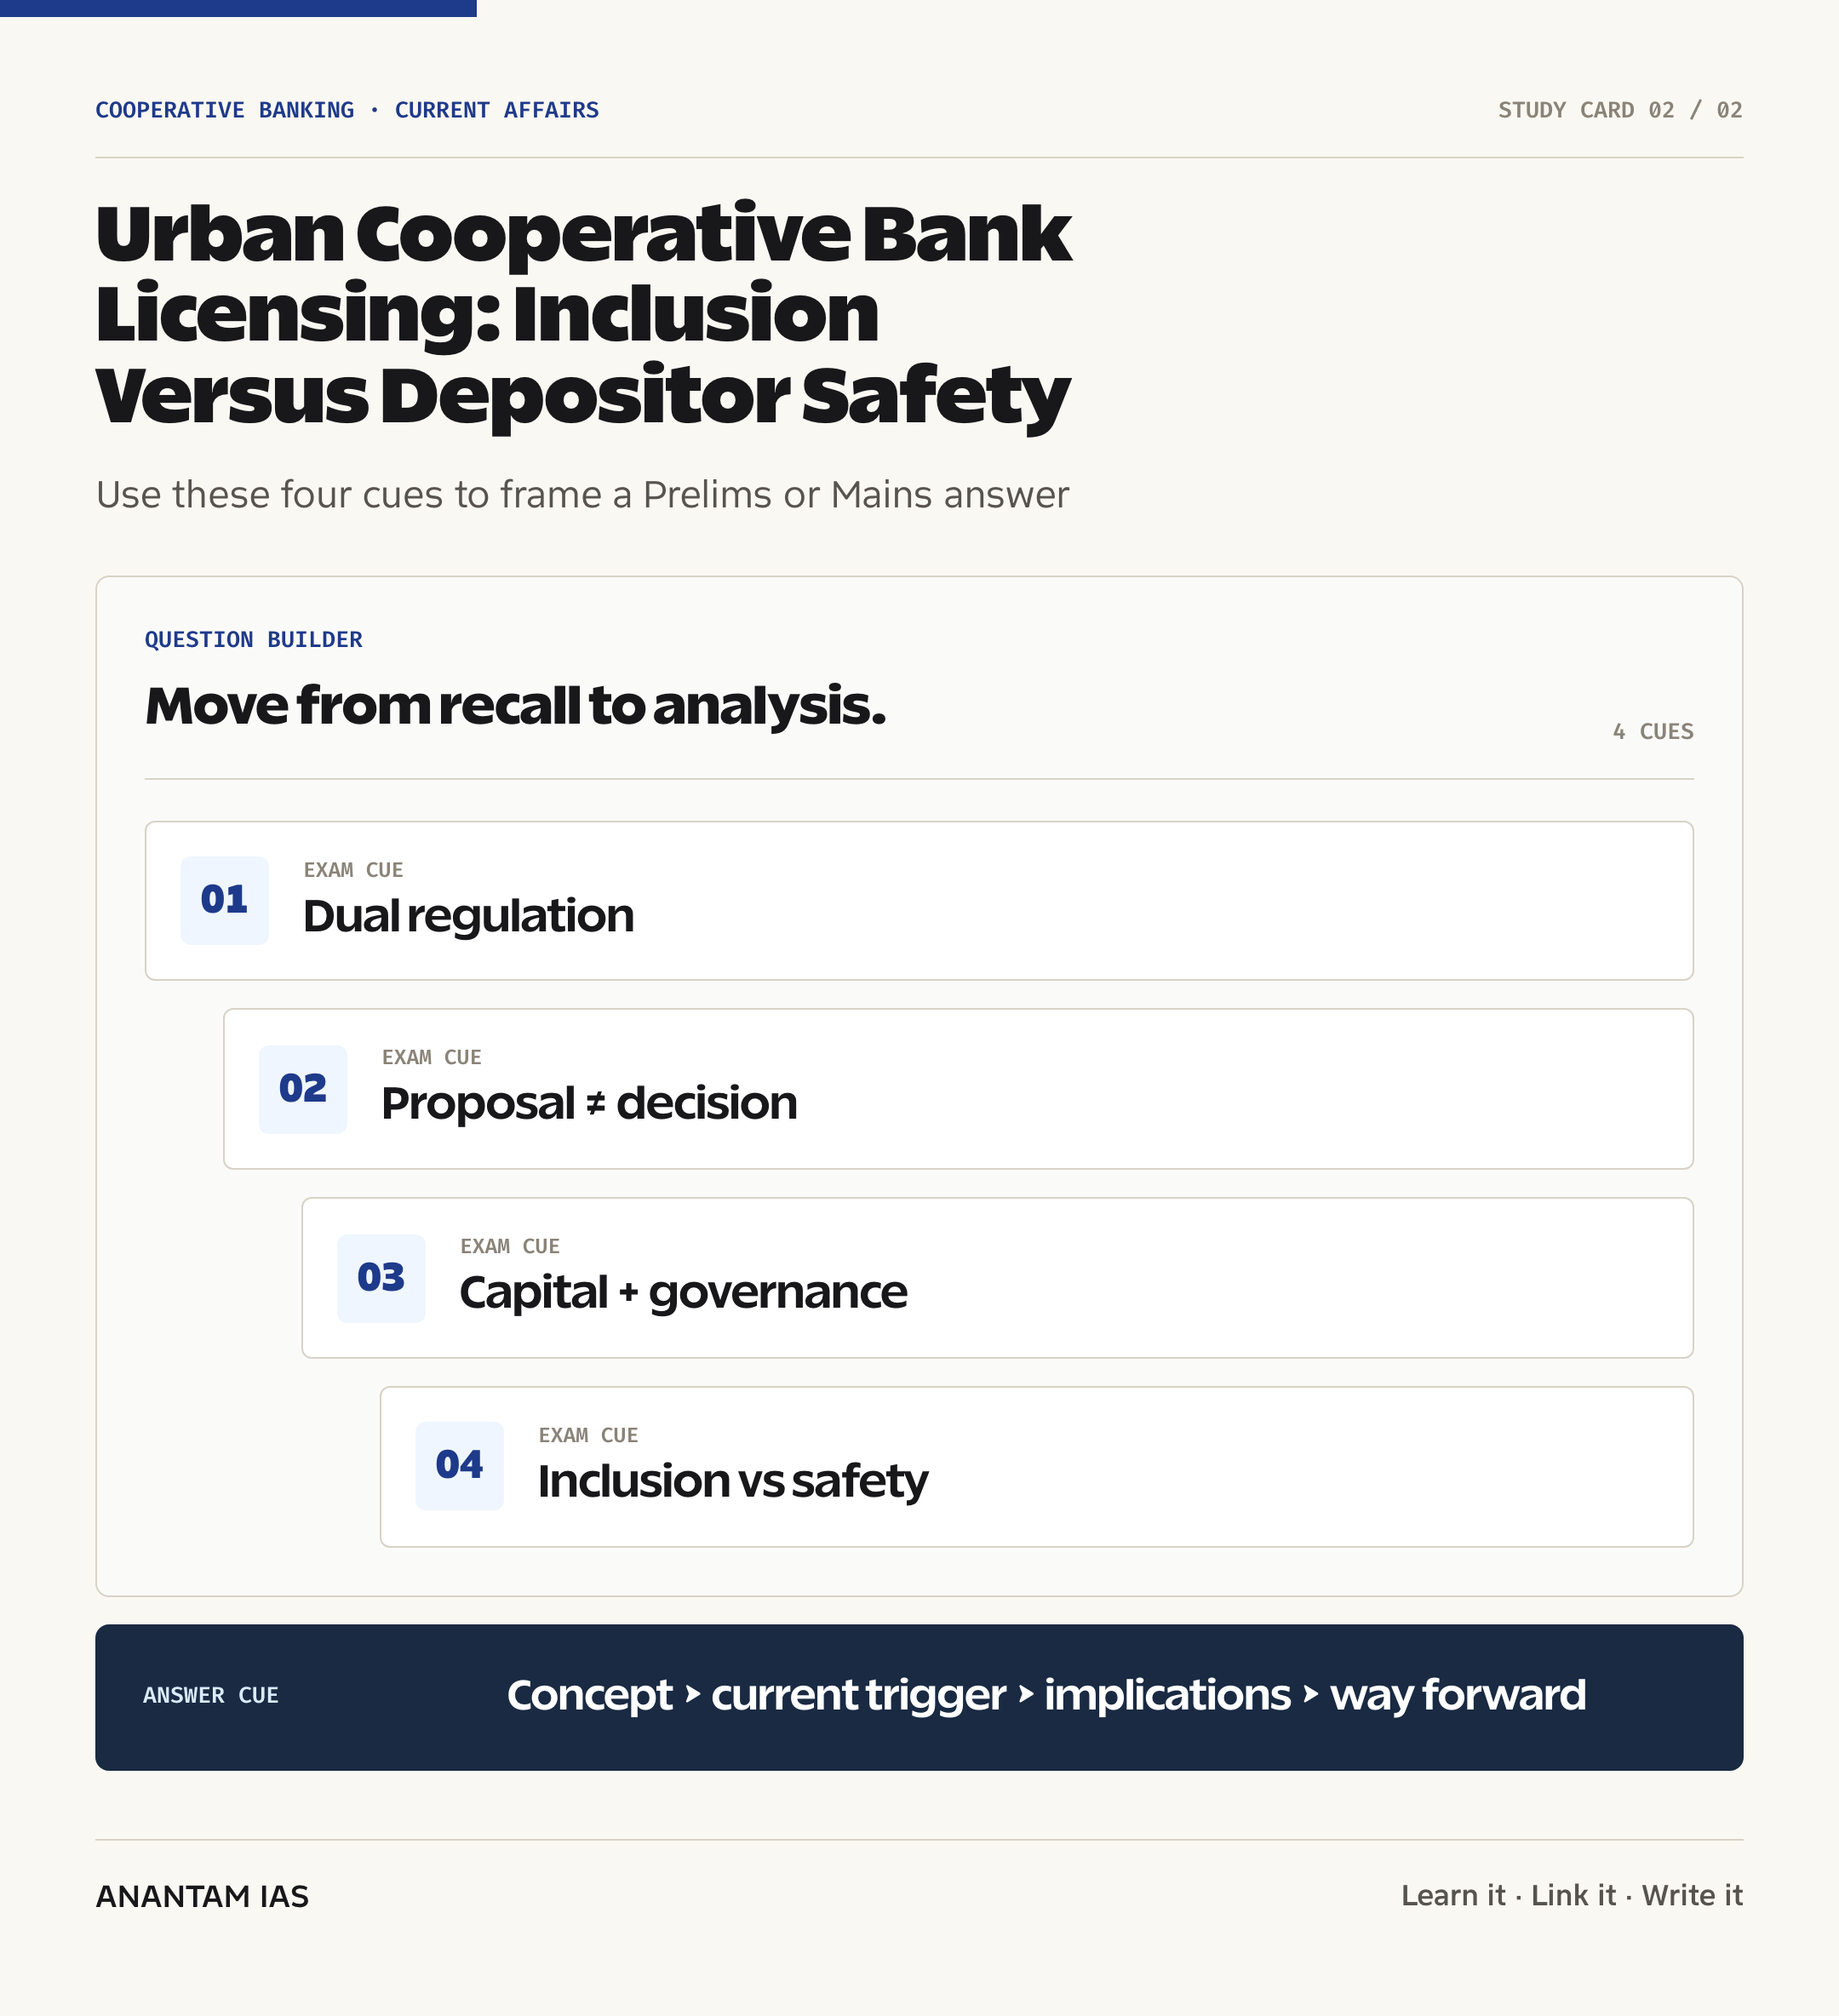
Dual regulation arises because a UCB is simultaneously a cooperative society and a banking institution.
- State List Entry 32 covers incorporation, regulation and winding up of cooperative societies within a State, while Union List Entry 45 covers banking.
- The State Registrar or Central Registrar handles the society’s registration, bye-laws, elections and other cooperative-law matters, depending on whether the entity is single-state or multi-state.
- RBI controls the banking function: licensing, prudential regulation, inspection, capital standards, restrictions, corrective action and cancellation of a bank licence.
- Banking laws first became applicable to cooperative societies in March 1966, creating the long-standing duality of jurisdiction.
- The 2020 amendment brought RBI’s regulatory and supervisory powers over UCBs closer to those used for commercial banks, especially for governance, audit and resolution.
- But the amendment didn’t erase the cooperative society’s legal identity or every role of the registrar. Coordination problems can still arise when banking directions require action under a separate cooperative law.
- The federal seam is also visible in the Banking Laws Amendment Act, which adjusted cooperative-bank governance without converting UCBs into commercial companies.
Why RBI Paused New Licences
The licensing pause followed evidence that rapid entry had produced too many weak institutions.
- After licensing norms were liberalised in May 1993, RBI issued 823 UCB licences up to June 2001.
- RBI later found that 31% of these newly licensed UCBs became financially unsound within a short period.
- In June 2004, RBI decided to consider fresh licences only after a comprehensive policy and a stronger legal and regulatory framework were in place.
- The screening approach increasingly favoured graduation from an established cooperative credit society with a demonstrated, verifiable track record rather than a newly created entity.
- A comprehensive policy in 2005 focused on financial health, coordination with governments and consolidation through mergers or closure of non-viable UCBs.
- The total number of UCBs fell from 2,104 on 31 December 2003 to 1,457 on 31 March 2025, reflecting consolidation as well as licence cancellation.
- The pause was a prudential response to experience, not a statutory ban imposed by Parliament. RBI can revisit entry policy, but it must still preserve the conditions in Section 22 governing a sound banking licence.
What RBI's 2026 Discussion Paper Actually Says
The paper opens a consultation and sketches safeguards; it doesn’t itself authorise a new bank.
- RBI released the paper on 13 January 2026 and sought public comments by 13 February on whether licensing should resume and what eligibility rules should apply.
- It tentatively favours starting with large cooperative credit societies, because established societies offer a longer record of governance and operating performance.
- A society would need at least ₹300 crore capital as on 31 March of the previous financial year merely to be eligible to apply under the proposed approach.
- The paper suggests at least 10 years of active operations and a good financial track record for at least five years.
- At the licensing stage, the proposed financial tests include assessed CRAR of at least 12% and net NPA not exceeding 3%.
- A wider geographic footprint is preferred for diversification and viability; multi-state societies may be favoured, though a compliant single-state society with sufficient spread could be considered.
- RBI says that after examining comments it may issue detailed draft guidelines for another round of public feedback. That sequencing confirms the July ministry request remains part of a live policy process.
The Sector Is Stronger but Still Uneven
Aggregate improvement supports reconsideration, while the distribution of weakness argues for strict entry norms.
- RBI counted 1,457 UCBs on 31 March 2025: 838 Tier 1, 535 Tier 2, 78 Tier 3 and six Tier 4 banks.
- The sector held ₹7.38 lakh crore in assets and ₹5.84 lakh crore in deposits at that date.
- Average CRAR was 18%, and 92% of UCBs had capital ratios above 12%, compared with 83% in 2015.
- Gross NPA stood at 6.2%, net NPA at 0.7% and provision coverage at 90.1%. These figures show stronger provisioning but don’t remove the burden of stressed assets.
- RBI reported 82 weak UCBs under various supervisory restrictions: 28 under All-Inclusive Directions, 32 under Prompt Corrective Action and 22 under the earlier Supervisory Action Framework.
- All 57 insolvent UCBs whose licences were cancelled in the disaggregated 2020-21 onward data were in Tiers 1-3, supporting RBI’s caution about small-bank failure.
- The latest aggregate health can be compared with Anantam IAS’s review of the RBI banking stability report, but UCBs require a separate risk lens from scheduled commercial banks.
Why the Ministry Wants Wider Coverage
The ministry’s case rests on geographic imbalance and the cooperative model’s potential to serve local borrowers.
- At the July event, RBI Central Board member Satish K. Marathe estimated that nearly 1,100 of about 1,450 UCBs were concentrated in Maharashtra, Gujarat and Karnataka.
- Those event figures are approximate and date-specific, while RBI’s formal March 2025 count is 1,457. Both indicate strong regional concentration rather than uniform national reach.
- A well-run UCB can use local information to assess small traders and enterprises that lack long credit histories or standard collateral.
- Member ownership can support relationship banking, local accountability and the recycling of community savings into community credit.
- New entrants in underserved towns could add competition, but a bank without scale, technology or diversified deposits may simply relocate risk rather than solve exclusion.
- Existing UCB branch expansion, small finance banks, business correspondents and digital public infrastructure are alternative ways to extend service. New licences should be compared against these channels, not treated as the only path.
- The wider cooperative-development context is covered in Anantam IAS’s note on India’s cooperative-sector reform push.
The Policy Tradeoffs
Licensing must reconcile cooperative participation with the non-negotiable duties of a deposit-taking institution.
- Inclusion versus viability: a small local bank may reach neglected borrowers, but a narrow customer and geographic base can create concentration risk.
- Democracy versus expertise: one-member-one-vote protects cooperative character, but elected boards may lack banking, risk, technology or treasury expertise.
- Local capital versus loss absorption: refundable member shares and entry or exit at face value make cooperative capital less permanent and less attractive to outside investors.
- Development versus connected lending: community knowledge can improve underwriting, while political capture or loans to directors and related interests can destroy credit discipline.
- Proportionality versus parity: smaller banks need rules suited to their scale, but depositors deserve common floors for capital, audit, cyber security and fit-and-proper management.
- Expansion versus consolidation: licensing a new institution may fill a map gap, while allowing a sound UCB to expand could achieve the same reach with an existing systems and compliance record.
- Innovation versus operational risk: digital channels lower delivery costs, but weak cyber security, vendor dependence and fraud controls can expose thousands of small depositors.
Four-Tier Regulation and Safety Nets
RBI now uses differentiated regulation, but tiering does not dilute the core duty to protect depositors.
- Tier 1 covers unit and salary-earner UCBs and other UCBs with deposits below ₹100 crore; Tier 2 covers ₹100 crore to below ₹1,000 crore.
- Tier 3 covers ₹1,000 crore to below ₹10,000 crore; Tier 4 covers ₹10,000 crore or more.
- The current prudential framework prescribes a minimum CRAR of 9% for Tier 1 and 12% for Tiers 2-4, with transition arrangements for existing banks.
- RBI’s Prompt Corrective Action framework for Tiers 2-4 permits early supervisory intervention when capital, asset quality or profitability weakens; Tier 1 remains under enhanced monitoring.
- The National Urban Co-operative Finance and Development Corporation became functional as an umbrella organisation in February 2024, intended to support technology, liquidity and shared services.
- DICGC cover of up to ₹5 lakh per depositor per bank limits household loss in an insured bank failure, but insurance cannot replace sound governance or prevent service disruption.
- A new licensing policy should be judged by its entry filters, continuing supervision and credible exit tools together. A high starting capital number alone cannot prevent fraud or mismanagement.
Way Forward
Complete the consultation transparently
- RBI should publish a reasoned response to stakeholder feedback and issue draft licensing guidelines before reopening applications.
- The final policy should state clearly that meeting eligibility conditions creates a right to apply, not an automatic entitlement to a bank licence.
Prefer proven institutions and underserved markets
- Require a verifiable operating record, professional management, clean related-party conduct and strong capital and asset quality.
- Use objective service-gap data so new licences address genuine exclusion rather than duplicating banks in already concentrated markets.
Align cooperative and banking governance
- Create common fit-and-proper, board-skill and audit standards through coordination among RBI, RCS and CRCS.
- Where State or multi-state laws block professional governance, pursue targeted legal amendments before licensing expansion.
Make technology a licensing condition
- Test core banking, cyber security, fraud monitoring, business continuity and vendor governance before a society begins public banking.
- Use the umbrella organisation for shared services without outsourcing the board’s responsibility for operational risk.
Review alternatives before creating a bank
- Compare a new licence with branch expansion by sound UCBs, small finance bank coverage and digital or business-correspondent delivery.
- Apply a staged approach with a small number of licences, close supervision and a public evaluation before wider rollout.
Conclusion
The Cooperation Ministry has identified a real map problem: UCBs remain heavily concentrated in a few States. But geographic scarcity doesn’t by itself prove that a new bank is the safest or cheapest solution. The relevant benchmark is durable access to trustworthy credit, not the count of licences.
RBI’s cautious sequence is sound: discussion paper, stakeholder feedback, draft guidelines and only then a possible licensing framework. If entry resumes, the model should combine cooperative ownership with bank-grade capital, professional governance, cyber resilience and early supervisory action. Inclusion that leaves depositors carrying governance risk isn’t inclusion.
UPSC Practice Questions
Prelims MCQ 1
With reference to Urban Cooperative Banks in India, consider the following statements:
- They require a licence from RBI under the Banking Regulation Act, 1949.
- They may be registered under a State Cooperative Societies Act or the Multi-State Cooperative Societies Act, 2002.
- Their banking functions are supervised by NABARD.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 1 and 2 are correct. RBI regulates and supervises UCB banking functions. NABARD supervises State Cooperative Banks and District Central Cooperative Banks, not UCBs.
Prelims MCQ 2
Which one of the following best describes RBI’s January 2026 paper on new UCB licensing?
(a) It immediately reopened licensing for every registered cooperative society (b) It transferred UCB licensing authority to the Ministry of Cooperation (c) It began consultation and tentatively proposed stringent eligibility for large cooperative credit societies (d) It abolished the four-tier regulatory framework for existing UCBs
Answer: (c) It began consultation and tentatively proposed stringent eligibility for large cooperative credit societies
Explanation:
The paper sought feedback and said RBI may later issue detailed draft guidelines. Its tentative safeguards included ₹300 crore capital, operating and financial track records, prudential tests and a wider footprint.
UPSC Mains Questions
- The case for new urban cooperative banks rests on local financial inclusion, while the case for restraint rests on depositor safety. Examine this tradeoff in light of RBI’s 2026 licensing discussion paper and the sector’s governance history. (250 words)
- Dual regulation is both a constitutional feature and an operational challenge for urban cooperative banks. Explain the division of authority between RBI and cooperative registrars, and suggest safeguards for any future reopening of the licensing window. (250 words)
Sources: Reserve Bank of India Discussion Paper and The Indian Express.
Frequently Asked Questions
What is an urban cooperative bank?
An urban cooperative bank is a cooperative society that has obtained an RBI licence to conduct banking business as a primary cooperative bank. It combines member-based ownership with banking functions such as accepting deposits and making loans. Its cooperative identity is governed by State or multi-state law, while RBI regulates its banking activities.
Has RBI reopened UCB licensing?
No final reopening follows merely from the January 2026 discussion paper or the Cooperation Ministry’s July request. RBI invited feedback on whether and how licensing should resume and said it may issue detailed draft guidelines afterward. A final framework and individual RBI approvals would still be required before a new UCB could operate.
Why were new licences paused?
RBI paused fresh licensing in 2004 after rapid entry produced weak banks. Of 823 UCB licences issued between May 1993 and June 2001, RBI found that 31% became financially unsound within a short period. The subsequent policy prioritised consolidation, stronger regulation and established credit societies with verifiable records.
What does dual regulation mean?
A UCB is regulated under two legal tracks. The State Registrar or Central Registrar oversees the cooperative society under the applicable cooperative law. RBI licenses and supervises its banking business under the Banking Regulation Act. The 2020 amendment strengthened RBI’s powers, but it didn’t eliminate the cooperative-law role of registrars.
What safeguards did RBI propose?
The discussion paper tentatively suggested large cooperative credit societies with at least ₹300 crore capital, 10 years of active operations, five years of good financial performance, CRAR of at least 12%, net NPA not above 3% and a wider geographical footprint. These are consultation proposals, not final licensing conditions.
Why are UCBs geographically concentrated?
The July policy discussion cited an estimate that nearly 1,100 of roughly 1,450 UCBs were in Maharashtra, Gujarat and Karnataka. The cooperative movement developed unevenly across States, producing strong regional clusters. Any response must compare new licences with expansion by sound existing banks and other inclusion channels.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.