Introduction
The Sustainable Harnessing and Advancement of Nuclear Energy for Transforming India Bill, 2025 — the SHANTI Bill, with the acronym standing for Sustainable Harnessing and Advancement of Nuclear Energy for Transforming India — is the single most consequential legislative pivot in India’s six-decade-old civil nuclear architecture. The Bill replaces the Atomic Energy Act of 1962 (the statute drafted under the influence of Homi J. Bhabha that had, until now, reserved the construction, ownership and operation of nuclear power plants exclusively for the Union government, channelled through the Nuclear Power Corporation of India Limited (NPCIL) and, for the fast-reactor stream, BHAVINI) and consolidates within itself the Civil Liability for Nuclear Damage Act, 2010. Introduced in the Lok Sabha on 15 December 2025, passed by the Lok Sabha on 17 December and the Rajya Sabha on 18 December, and granted Presidential assent on 20 December 2025, opens the civil nuclear sector to qualified private operators, restructures the liability framework that has frozen foreign reactor vendors out of the Indian market since 2010, and provides the legal scaffolding for Prime Minister Narendra Modi‘s announced target of 100 GW of installed nuclear capacity by 2047. For the UPSC aspirant, the SHANTI Bill is a Paper III science-and-technology and energy-security flagship, a Paper II governance-and-federalism question on regulatory independence, and a Paper IV ethics question on the dual-use character of nuclear technology.
The headline numbers anchor the policy stakes. India’s installed nuclear capacity stands at roughly 8,180 MW across 24 operating reactors, contributing under 3% of the national electricity mix — a share that has barely moved since the early 2000s despite the political weight given to the technology. The 100 GW target requires more than a twelve-fold expansion in two decades, an order of magnitude that NPCIL alone cannot deliver under existing statutory and capital constraints. This article unpacks the legal architecture of the SHANTI Bill, the parallel amendments to the Civil Liability for Nuclear Damage Act 2010, the state of India’s three-stage nuclear programme, the Bharat Small Modular Reactor (BSMR) push, the comparative position vis-à-vis China, France, the United States and Russia, and the criticisms already aired by independent analysts.

Quick Facts at a Glance
| Indicator | Value | Source |
|---|---|---|
| Bill name and date of introduction | SHANTI Bill, 2025 (Sustainable Harnessing and Advancement of Nuclear Energy for Transforming India), introduced in Lok Sabha 15 December 2025 | Parliament of India, PRS Legislative Research |
| Statute repealed and replaced | Atomic Energy Act, 1962 | Department of Atomic Energy |
| Statute repealed and consolidated | Civil Liability for Nuclear Damage Act, 2010 | Ministry of Law and Justice |
| Presidential assent | 20 December 2025 | Parliament of India |
| India’s installed nuclear capacity (2025) | 8,180 MW (24 reactors) | NPCIL Annual Report 2024-25 |
| Nuclear share in electricity mix | ~2.8% | Central Electricity Authority |
| Target installed nuclear capacity by 2047 | 100 GW | Union Budget 2025-26 / Nuclear Energy Mission |
| Operator liability cap, CLNDA 2010 (pre-replacement) | Rs 1,500 crore (fixed) | CLNDA Section 6(2) |
| Operator liability under SHANTI Act 2025 (Second Schedule) | Tiered: Rs 100 crore (up to 150 MW thermal + fuel cycle/transport) → Rs 300 crore (150-750 MW) → Rs 750 crore (750-1,500 MW) → Rs 1,500 crore (1,500-3,600 MW) → Rs 3,000 crore (above 3,600 MW thermal) | SHANTI Act 2025, Second Schedule; Norton Rose Fulbright analysis |
| BSMR programme — first reactor target year | BSMR-200 (200 MWe pressurised heavy water reactor, derivative of IPHWR-220) and SMR-55 (55 MW) targeted at Tarapur by 2033; conceptual design completed March 2025 | Department of Atomic Energy / PIB / NPCIL |
| Reactors under construction | ~7,300 MW (Kakrapar Unit 4, Rajasthan 7-8, Kudankulam 3-6, GHAVP 1-2) | NPCIL / IAEA PRIS database |
Background and Historical Context
The Indian civil nuclear story begins almost simultaneously with the Republic itself. The Atomic Energy Commission was constituted on 10 August 1948 under the chairmanship of Homi J. Bhabha, with a remit drafted personally by Prime Minister Jawaharlal Nehru who saw atomic energy as the developmental complement to the steel mills and dams of the Nehruvian programme. The first Atomic Energy Act was enacted in 1948, replaced by the more comprehensive Atomic Energy Act of 1962 after the Department of Atomic Energy was carved out as a separate administrative entity in 1954 reporting directly to the Prime Minister. The 1962 statute, drafted at a moment when nuclear technology was understood almost entirely through the security prism, vested ownership of all fissile material and reactor operation in the Central Government and prohibited private participation — a posture sharpened by the Pokhran-I peaceful nuclear explosion of 18 May 1974 and the consequent technology denial regimes led by the Nuclear Suppliers Group formed in 1974-75.
The deeper structural story, however, lies in the cycle of isolation and re-entry. The Pokhran-II tests of 11 and 13 May 1998 under Prime Minister Atal Bihari Vajpayee deepened sanctions but also clarified India’s strategic posture; the diplomatic breakthrough came with the Indo-US Civil Nuclear Agreement negotiated between Prime Minister Manmohan Singh and President George W. Bush, formalised through the Henry J. Hyde Act of 2006, the NSG waiver of 6 September 2008, and the 123 Agreement. The waiver allowed India — uniquely among non-NPT states — to engage in civil nuclear commerce without signing the Treaty on the Non-Proliferation of Nuclear Weapons, and was paired with a separation plan that placed 14 of India’s then 22 reactors under International Atomic Energy Agency (IAEA) safeguards. The India-specific Safeguards Agreement entered into force in 2009 and the Additional Protocol in 2014.
The hoped-for nuclear renaissance never quite arrived. The Civil Liability for Nuclear Damage Act, 2010, drafted in the wake of the Bhopal jurisprudence, introduced an operator-recourse provision in Section 17(b) that effectively channelled liability back to the equipment supplier in the event of patent or latent defect — a clause unparalleled in any other Convention on Supplementary Compensation jurisdiction. American vendors Westinghouse and GE Hitachi, French Areva (later EDF), and Russian Rosatom all read Section 17(b) as commercially uninsurable; the Jaitapur 9,900 MW EPR project in Maharashtra and the Kovvada AP-1000 site in Andhra Pradesh have remained on paper for over a decade. Combined with the political shock of Fukushima Daiichi (11 March 2011), the nuclear pipeline froze. The 2025 push reflects the Modi government’s reading that the demographic, climate and energy-security pressures of the next two decades make a third revival attempt unavoidable — and that this attempt cannot rely on NPCIL’s balance sheet or a 1962-vintage statute.
Key Features of the SHANTI Bill
What the Bill Changes — Private Participation Framework
The operative change in the SHANTI Bill is the abandonment of the exclusivity regime under the 1962 Act, which had reserved the production of atomic energy and the ownership of nuclear installations to the Central Government or its undertakings. The new statute introduces a category of licensed private operator — a domestically incorporated company satisfying technical, financial and security-clearance thresholds prescribed by the Atomic Energy Regulatory Board (AERB), which the Bill grants statutory status as an independent regulator. Foreign direct investment in nuclear power projects is capped at 49%, with majority control retained on the Indian side; private Indian companies may build, own and operate nuclear plants under AERB licensing, ending NPCIL’s de facto operating monopoly. Sensitive activities — uranium enrichment and isotopic separation, heavy-water production, spent-fuel management and reprocessing, and uranium/thorium exploration — remain exclusively reserved to the Central Government under the new statute. Reliance Industries, Tata Power, Adani Power, Vedanta and L&T are widely reported to have submitted expressions of interest in the run-up to the Bill’s introduction.
Civil Liability for Nuclear Damage — Parallel Amendments
Running in parallel — in fact, consolidated within the same statute — is the replacement of the Civil Liability for Nuclear Damage Act 2010 with a new liability architecture that addresses the supplier-recourse problem. The reformed treatment of Section 17(b) recasts supplier liability as contractual rather than statutory, allowing operator and supplier to negotiate the scope of recourse within the framework of the Convention on Supplementary Compensation for Nuclear Damage — which India ratified in 2016 — rather than mandating an open-ended statutory channel. The fixed Rs 1,500 crore operator-liability cap is replaced by a tiered, capacity-linked liability structure set out in the Second Schedule: Rs 100 crore for installations up to 150 MW thermal (and for fuel-cycle/transport activities), Rs 300 crore for 150-750 MW, Rs 750 crore for 750-1,500 MW, Rs 1,500 crore for 1,500-3,600 MW, and Rs 3,000 crore for installations above 3,600 MW thermal. The time limit for tort claims is harmonised with the CSC framework. The India Nuclear Insurance Pool, launched in June 2015 with a Rs 1,500 crore capacity underwritten by GIC Re and eleven other non-life insurers (with New India Assurance issuing the policy on behalf of the pool), is statutorily recognised as a vehicle for operator insurance. The combined effect is to bring Indian liability law into convergence with the Vienna Convention and Paris Convention regimes, removing the single biggest commercial obstacle that has held up Westinghouse and EDF.
Three-Stage Nuclear Programme — Where India Stands
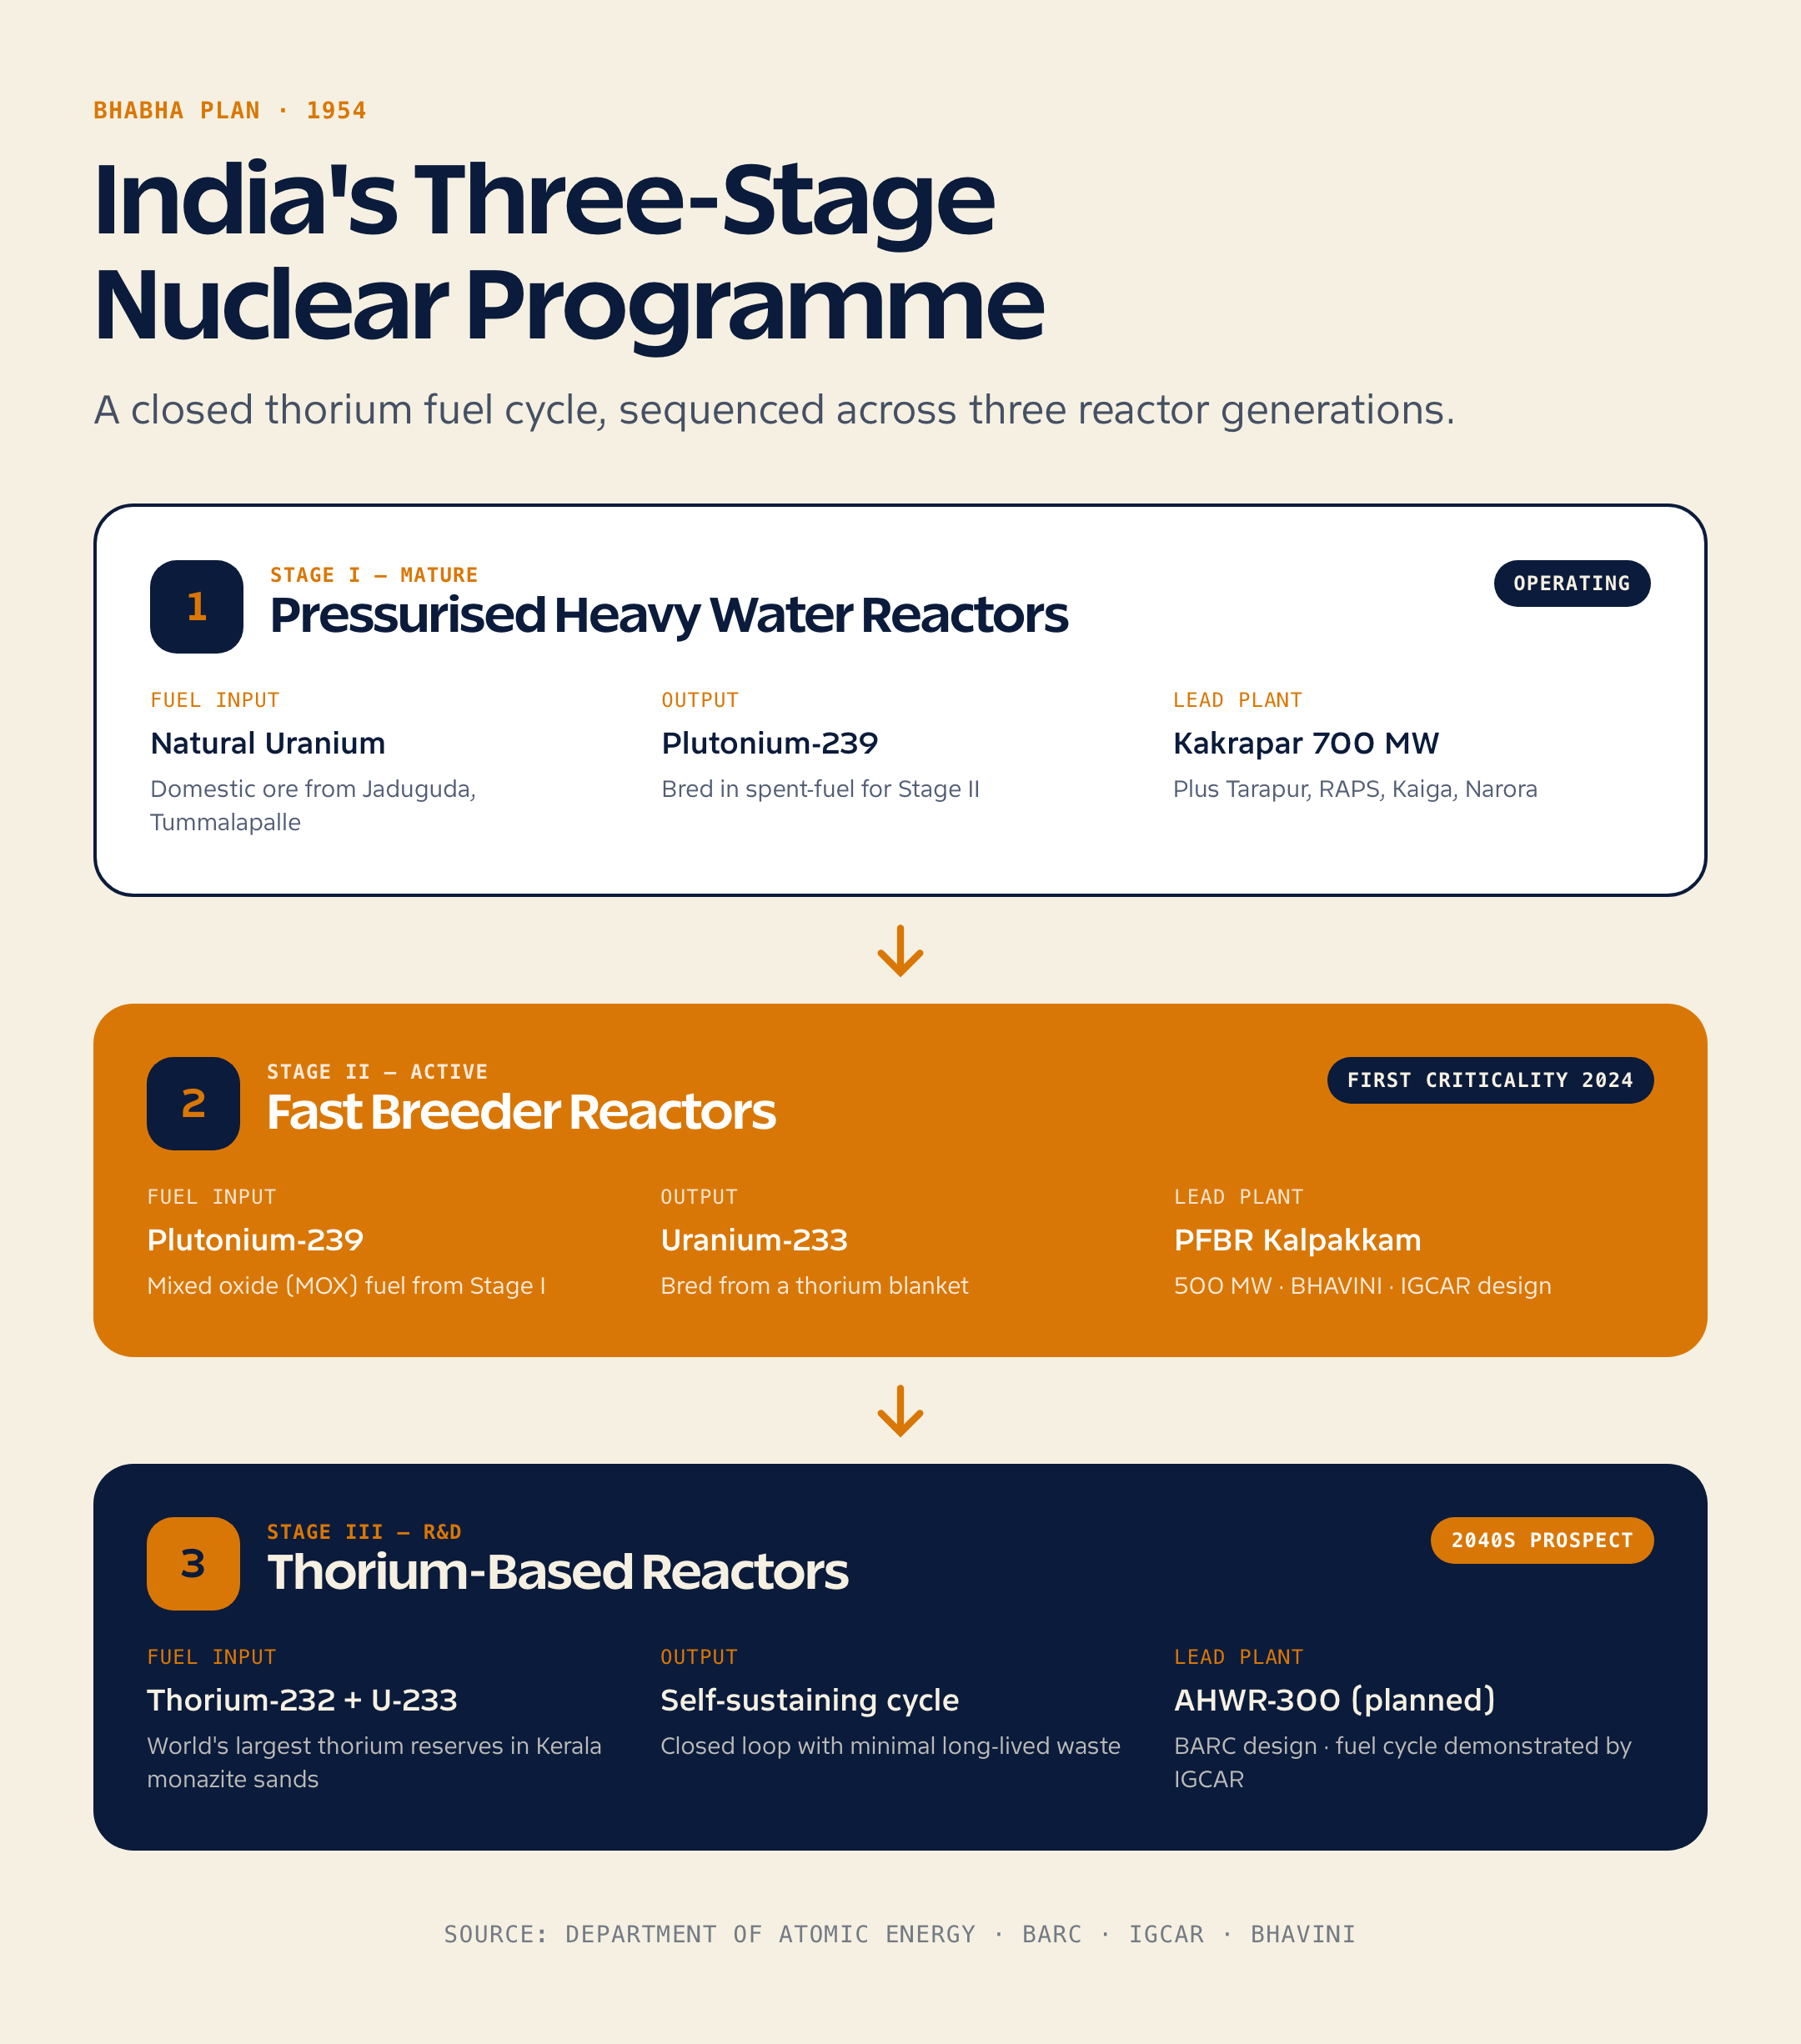
Bhabha’s three-stage nuclear programme, articulated in 1954, sequences India’s reactor strategy around domestic thorium reserves — the world’s largest, concentrated in Kerala’s monazite sands. Stage I uses natural uranium in Pressurised Heavy Water Reactors (PHWRs) to generate electricity and breed plutonium-239; this stage is mature, with the indigenous 540 MW and 700 MW PHWR designs at Tarapur, Kakrapar, Kaiga and Rajasthan Atomic Power Station. Stage II uses Pu-239 in Fast Breeder Reactors (FBRs) with a U-238/thorium blanket; the Prototype Fast Breeder Reactor (PFBR) at Kalpakkam, operated by BHAVINI, achieved first criticality in March 2024 after a sixteen-year delay. Stage III envisages thorium-fuelled Advanced Heavy Water Reactors using U-233 bred from thorium; the Indira Gandhi Centre for Atomic Research (IGCAR) has demonstrated the fuel cycle but a commercial Stage III reactor remains a 2040s prospect. The SHANTI Bill is officially neutral on stage selection but the private-participation language is drafted with PHWR and SMR designs in mind.
Bharat Small Modular Reactor (BSMR) Programme
The Bharat Small Modular Reactor (BSMR) programme, announced in Union Budget 2024-25 by Finance Minister Nirmala Sitharaman and operationalised through the Nuclear Energy Mission in Budget 2025-26 with an initial outlay of Rs 20,000 crore, is the technology vector that the SHANTI Bill is designed to enable. The flagship BSMR-200 — a 200 MWe pressurised heavy water reactor derivative of the indigenous IPHWR-220 design, using slightly enriched uranium fuel and passive safety features — is being developed jointly by NPCIL and BARC, with conceptual design completed in March 2025; the BSMR-200 along with a 55 MWe SMR-55 variant are targeted for deployment at Tarapur by 2033. Estimated capital cost is around Rs 30 crore per MWe. SMRs are factory-fabricated, transported to site as modules, and require land footprints of under 50 hectares — a fraction of the 800-1,500 hectare exclusion zones around conventional 1,000 MW units. The Bill carves out a separate licensing pathway for SMRs with shortened environmental clearance timelines and dedicated allocations of fuel from the Nuclear Fuel Complex at Hyderabad. Industrial customers — particularly steel, aluminium, refining and data centres — are explicitly named as eligible captive offtakers.
Significance for UPSC and General Knowledge
- Direct GS3 syllabus hit on science and technology — developments and applications in everyday life and energy security.
- GS3 energy and environment overlap on the role of nuclear power in India’s net-zero-by-2070 transition and the Panchamrit commitments at COP26.
- GS2 governance hit on parliamentary procedure, Bill drafting, and the regulatory independence of the Atomic Energy Regulatory Board.
- GS2 international relations anchor on the NSG waiver, IAEA safeguards, the 123 Agreement and the Convention on Supplementary Compensation.
- Prelims static fodder on the three-stage programme, named reactors, BHAVINI, IGCAR, BARC, NPCIL and the Atomic Energy Act 1962.
- GS4 ethics linkage on dual-use technology, intergenerational equity in spent-fuel management, and the public-interest dimension of liability law.
- Essay paper data bank on energy transition, technological self-reliance and the Atmanirbhar Bharat framing.
Detailed Analysis: India’s Nuclear Energy Roadmap to 2047
India’s installed nuclear fleet today comprises 24 operating reactors aggregating to 8,180 MW, distributed across seven sites and dominated structurally by indigenous PHWR designs of 220 MW and 540 MW vintage with the newer 700 MW PHWRs at Kakrapar and Rajasthan as the leading edge. The Kudankulam Nuclear Power Plant in Tamil Nadu hosts the only Russian VVER-1000 units in commercial operation — Units 1 and 2 (1,000 MW each, commissioned 2014 and 2017) — with Units 3 through 6 under construction. Tarapur Atomic Power Station in Maharashtra, commissioned in 1969, holds the distinction of being India’s oldest operating nuclear plant and one of the oldest in continuous commercial service anywhere in the world; its two original GE-supplied BWR units (TAPS-1 and TAPS-2, 160 MW each) operate alongside two 540 MW PHWRs commissioned in 2005-06.
| Plant | State | Capacity (MW) | Reactor Type |
|---|---|---|---|
| Tarapur Atomic Power Station (TAPS 1-4) | Maharashtra | 1,400 | BWR + PHWR |
| Rajasthan Atomic Power Station (RAPS 1-6) | Rajasthan | 1,180 | PHWR |
| Madras Atomic Power Station (MAPS) | Tamil Nadu | 440 | PHWR |
| Narora Atomic Power Station | Uttar Pradesh | 440 | PHWR |
| Kakrapar Atomic Power Station (KAPS 1-3) | Gujarat | 1,140 | PHWR (incl. 700 MW) |
| Kaiga Generating Station (1-4) | Karnataka | 880 | PHWR |
| Kudankulam (KKNPP 1-2 operating) | Tamil Nadu | 2,000 | VVER-1000 (Russia) |
| Kakrapar Unit 4 (under construction) | Gujarat | 700 | PHWR |
| Rajasthan Units 7-8 (under construction) | Rajasthan | 1,400 | PHWR (700 MW each) |
| Kudankulam 3-6 (under construction) | Tamil Nadu | 4,000 | VVER-1000 (Russia) |
| GHAVP 1-2 (Gorakhpur, under construction) | Haryana | 1,400 | PHWR (700 MW each) |
| PFBR (Kalpakkam, BHAVINI) | Tamil Nadu | 500 | FBR (Stage II) |
The arithmetic of the 100 GW by 2047 target is unforgiving. Adding the operating fleet (8.18 GW) and the under-construction pipeline (~7.3 GW) yields roughly 15.5 GW of capacity that will be on the grid by the early 2030s under best-case execution. Reaching 100 GW therefore requires roughly 85 GW of additional capacity in 15 years — which works out to an annual addition of around 5.7 GW, more than five times the average annual addition rate India has actually achieved since 2000. NPCIL alone, even with concessional sovereign financing, can credibly deliver perhaps 30-35 GW of this. The remainder must come from private operators under SHANTI, foreign-vendor partnerships, and the SMR pipeline. The fleet mode procurement framework approved in 2017 — which authorised ten 700 MW PHWRs in series production — is treated by the Department of Atomic Energy as the template for scaling, and the SHANTI Bill explicitly contemplates parallel fleet orders for SMRs.
Site identification and land acquisition remain the politically combustible parts of the plan. The Modi government has retained Jaitapur in Ratnagiri district of Maharashtra (six EPRs of 1,650 MW each, in partnership with EDF), Kovvada in Srikakulam district of Andhra Pradesh (originally GE Hitachi, potentially repositioned for Westinghouse AP-1000s), Mithi Virdi in Gujarat (now repurposed), and Haripur in West Bengal (effectively shelved after Mamata Banerjee’s opposition) on the master site list. The SHANTI Bill streamlines the environmental impact assessment regime for nuclear sites by integrating AERB and Ministry of Environment, Forest and Climate Change clearances into a single-window process, and creates a deemed-approval clock for state-level No Objection Certificates — a federalism choice that has already drawn pushback from non-BJP-ruled states.
The fuel cycle is the second binding constraint. Domestic uranium reserves, concentrated at Jaduguda in Jharkhand and the newer Tummalapalle deposit in Andhra Pradesh, supply only the indigenous unsafeguarded reactor stream. Safeguarded reactors — including all VVERs and any future foreign-vendor units — depend on imported uranium under bilateral supply agreements with Kazakhstan, Russia, Canada, France, Australia and Uzbekistan. The Uranium Corporation of India Limited (UCIL), headquartered at Jaduguda, mines and processes domestic ore; the Nuclear Fuel Complex (NFC) at Hyderabad fabricates fuel assemblies. The SHANTI Bill empowers the central government to allocate fuel to private operators on a regulated-price basis, removing the legal ambiguity that had previously prevented NFC from contracting with non-NPCIL entities.
The economic logic is finely balanced. The Central Electricity Authority‘s 2024 levelised-cost analysis pegs PHWR tariffs at Rs 4.5-5.5 per unit and imported VVER tariffs at Rs 5-6 per unit — competitive with coal at the busbar but well above firm solar-plus-storage at Rs 3-3.5 per unit and uncompetitive with merchant solar at Rs 2-2.5 per unit. The case for nuclear rests not on average levelised cost but on three system-level attributes: round-the-clock dispatchability that storage cannot yet match at scale, a land-use intensity roughly 100 times more efficient than utility-scale solar per MW-yr, and a capacity factor above 80% that anchors grid stability as the variable renewable share crosses 50%. The Survey-style framing the government has adopted — that nuclear is an “anchor” rather than a “competitor” to renewables — is the analytical core the SHANTI Bill is built on.
What the closing chapters of the legislative architecture make clear is that 2047 is not the binding date — 2031 is. India’s Nationally Determined Contribution under the Paris Agreement requires non-fossil capacity to reach 50% of installed power capacity by 2030, a milestone effectively already achieved on paper through the renewables build-out. But energy generation, not capacity, is the harder denominator: without 30-40 GW of additional nuclear capacity between 2031 and 2040, the trajectory to net-zero-by-2070 requires implausibly steep deployment of green hydrogen, carbon capture, or geological storage. The SHANTI Bill is, in this sense, less an energy Bill than a climate Bill written in nuclear language.
Comparative Perspective
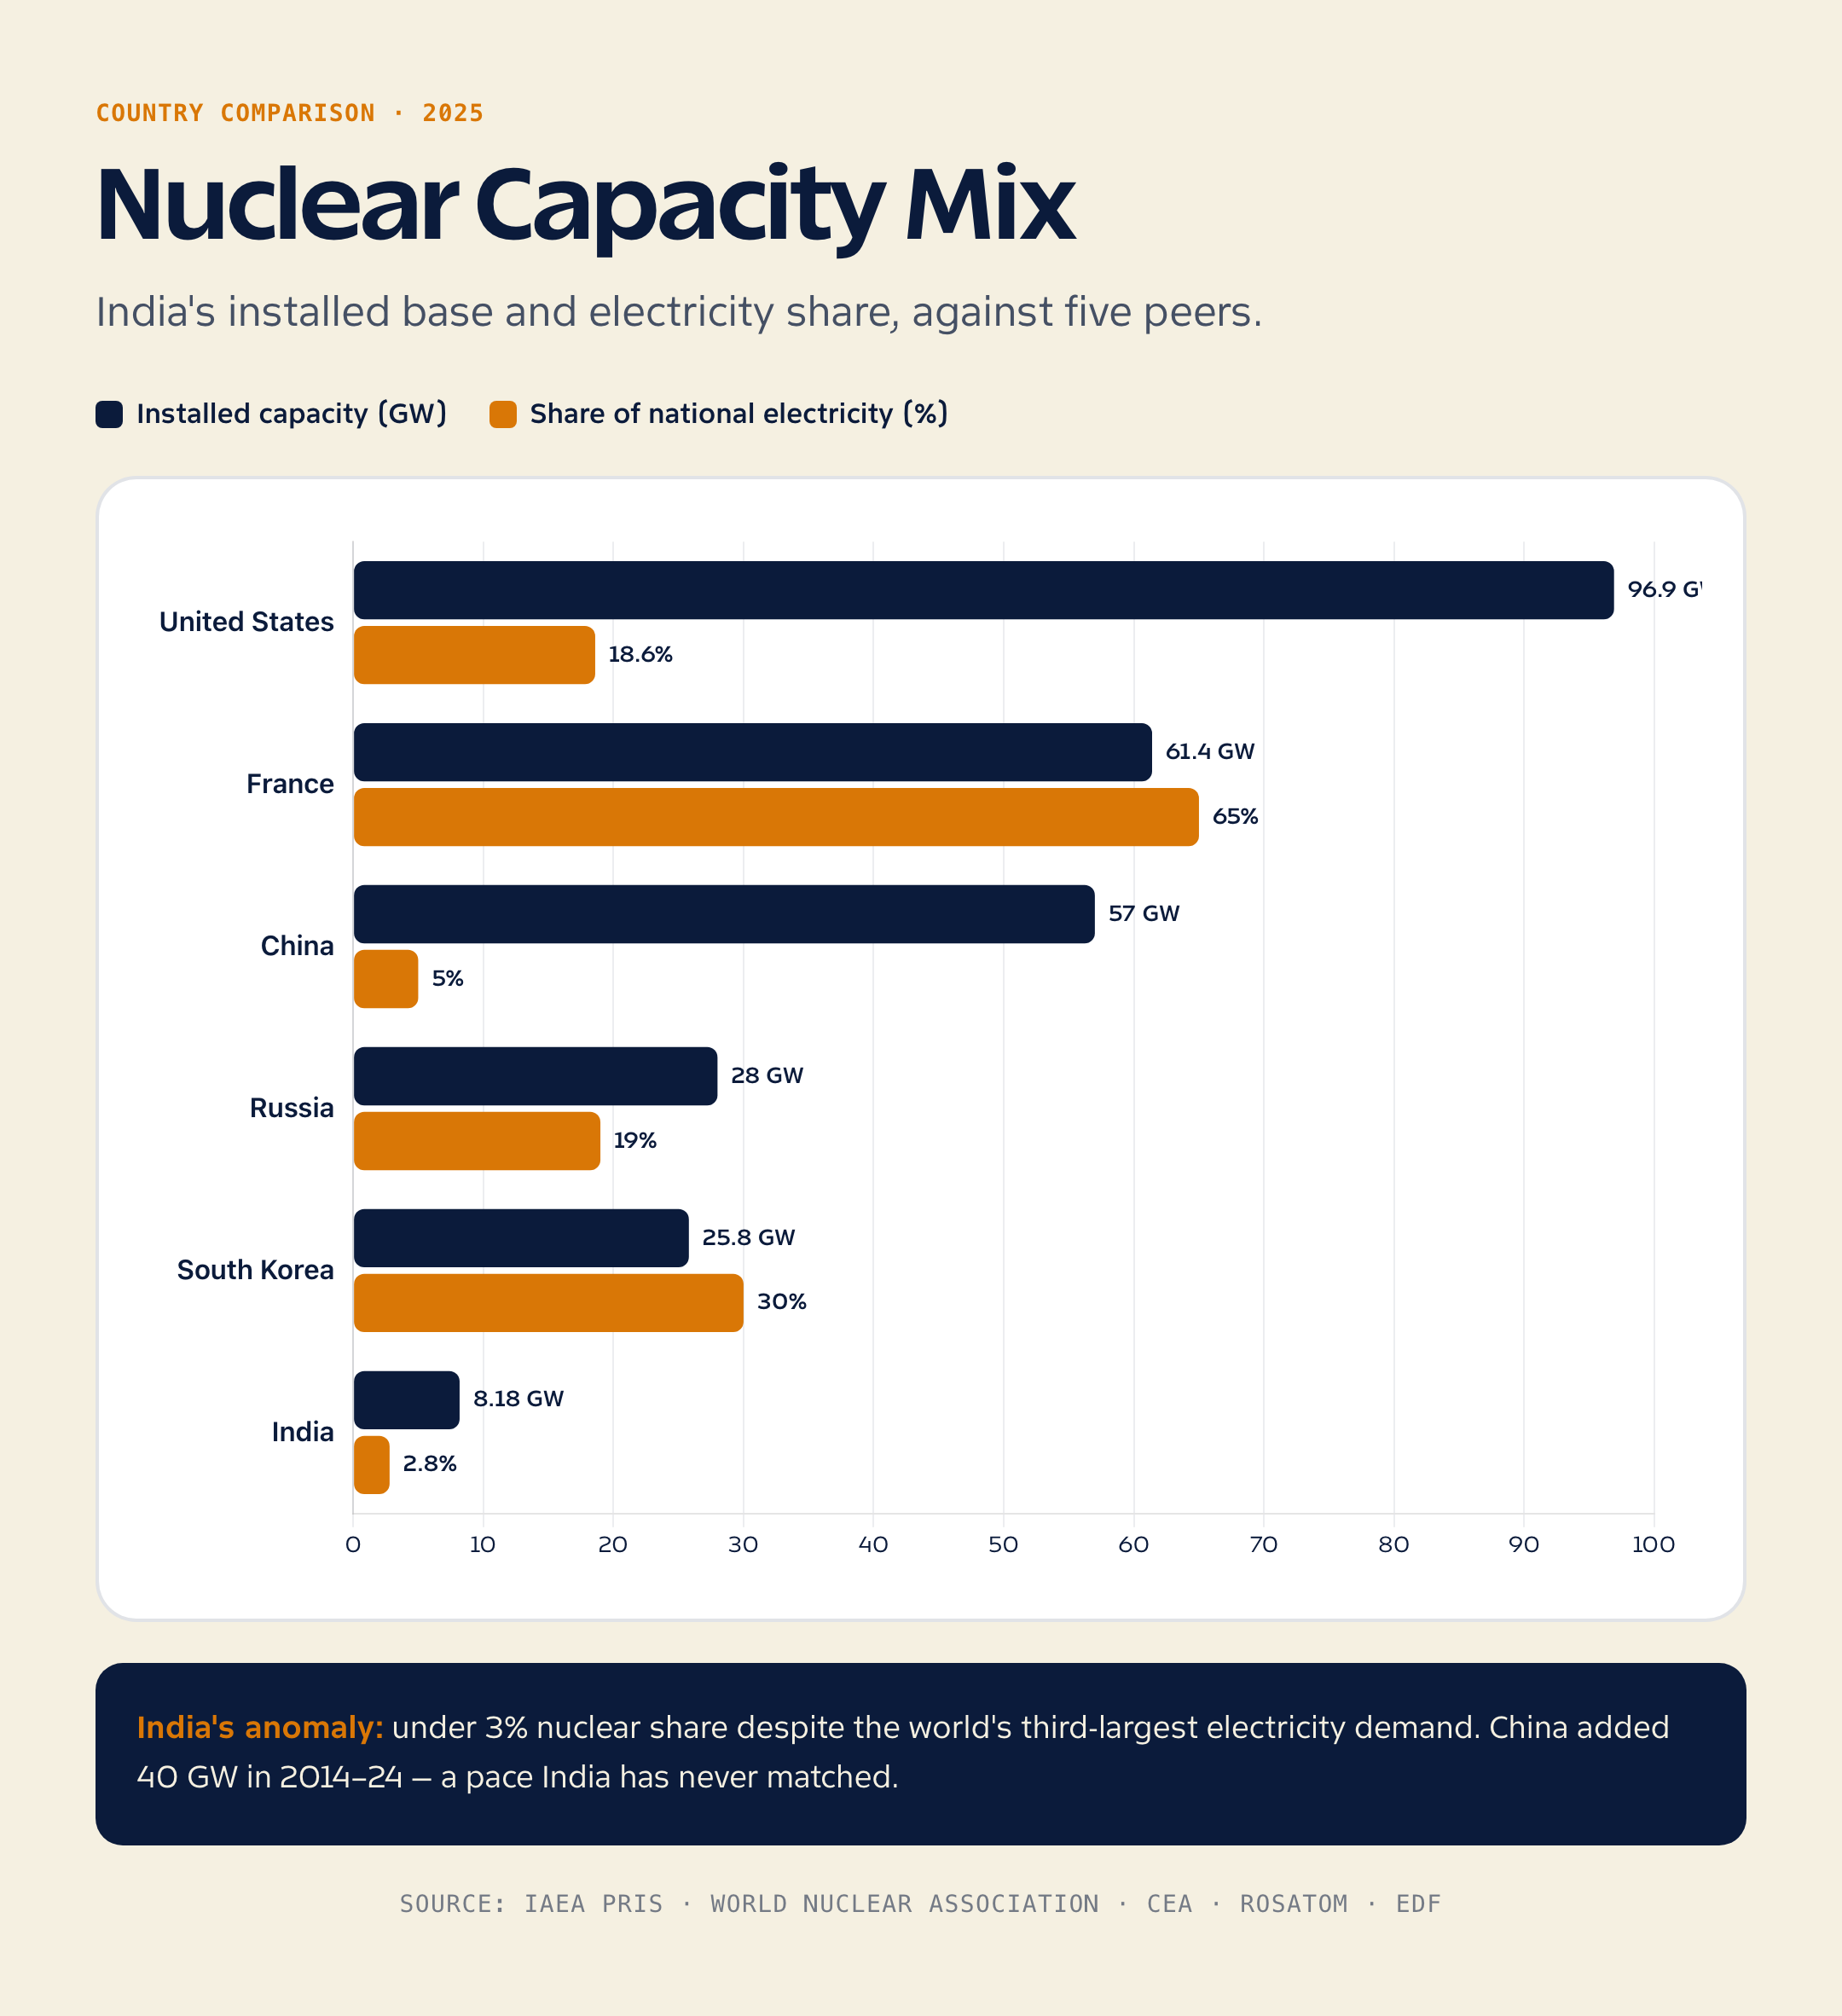
India’s nuclear position is best understood against the four major civil-nuclear powers and one fast-rising peer. The United States retains the world’s largest operating fleet but has barely added capacity in two decades and is now relying on SMR demonstration at NuScale and TerraPower. France derives an unusually high share of its electricity from nuclear — a legacy of the Messmer Plan of 1974 — but is now extending plant lifetimes rather than building new EPR2 capacity. Russia, through Rosatom, is the world’s largest exporter of nuclear technology and has VVER projects under construction in Bangladesh, Egypt, Turkey and Hungary. China is the only country whose new-build programme matches the scale India is now contemplating: 56 reactors operating, over 30 under construction, and a target of 200 GW by 2035.
| Country | Installed Nuclear Capacity (GW, 2025) | Share in National Electricity Mix |
|---|---|---|
| United States | ~96.9 GW (94 reactors) | ~18.6% |
| France | ~61.4 GW (56 reactors) | ~65% |
| China | ~57.0 GW (56 reactors operating) | ~5% |
| Russia | ~28.0 GW (37 reactors) | ~19% |
| India | 8.18 GW (24 reactors) | ~2.8% |
| South Korea | ~25.8 GW (26 reactors) | ~30% |
The structural insight from this table is that India’s nuclear share — under 3% — is anomalously low for a country of its size, electricity demand and stated climate ambition. Even reaching 100 GW by 2047 would lift the share to perhaps 9-10% on plausible electricity-demand-growth assumptions, which is closer to the United States’ present share than to France’s. The instructive comparison is not absolute capacity but pace: China added 40 GW of nuclear capacity in the decade 2014-2024, an annual rate of 4 GW that India has never come close to matching. China’s path was paved by a state-owned holding structure (CNNC, CGN, SPIC) with quasi-private operating subsidiaries — a model that the SHANTI architecture — Indian-side majority ownership (with FDI capped at 49%) paired with AERB-licensed private operators — partially imitates without admitting it.
Challenges and Criticisms
The most sustained academic critique of the SHANTI framework comes from M.V. Ramana at the University of British Columbia’s Liu Institute for Global Issues and a long-standing voice on the Coalition for Nuclear Disarmament and Peace (CNDP). Ramana’s argument, developed across multiple publications including a recent piece in the Bulletin of the Atomic Scientists, is that the 100 GW target rests on optimistic levelised-cost assumptions, ignores the construction-time overruns that have plagued every Generation III+ project worldwide (Olkiluoto, Flamanville, Vogtle, Hinkley Point C), and underweights the cost-trajectory of solar-plus-storage which has fallen by over 80% in the same window during which nuclear costs have risen. The Centre for Strategic and International Studies (CSIS), in its 2025 brief on the Indo-US civil nuclear partnership, raised a parallel concern that the liability amendments, while convergent with CSC, may still face challenge before the Supreme Court on grounds of inconsistency with the absolute liability doctrine articulated in M.C. Mehta v. Union of India (1987).
The proliferation and security architecture is the second flank of critique. India is one of only four nuclear-weapons-possessing states outside the NPT (alongside Pakistan, Israel and North Korea), and the SHANTI Bill’s expansion of fissile-material handling to private operators raises classical safeguards-and-security questions. The Bill’s drafters have responded with a tightened physical protection regime aligned with the IAEA’s INFCIRC/225/Rev.5, mandatory background-clearance for all employees handling fissile material, and a centralised nuclear material accountancy system run by the Department of Atomic Energy. Critics from the disarmament community, including former Atomic Energy Commission member A. Gopalakrishnan, have argued that genuine regulatory independence — rather than the AERB’s current status as a creature of the DAE — is a precondition for credibly licensing private operators, and that the SHANTI Bill stops short of the Nuclear Safety Regulatory Authority Bill first drafted in 2011 which proposed a statutorily independent regulator.
The third criticism is local and political. Site-level resistance has been a recurring feature of the Indian nuclear story — at Kudankulam in 2011-12, at Jaitapur through the 2010s, at Haripur from 2007 onwards — and these movements, whether mobilised under the banner of the People’s Movement Against Nuclear Energy (PMANE) led by S.P. Udayakumar at Kudankulam or articulated by fisherfolk associations on the Konkan coast, have produced multi-year delays. The SHANTI Bill’s deemed-approval clock for state NOCs is already being read by state governments in Tamil Nadu, Kerala and West Bengal as an erosion of the cooperative-federalism framework. The Standing Committee on Energy, to which the Bill has been referred, will hear depositions from state governments, environmental groups and industry through Q1 2026, and the final shape of the deemed-approval provision will be the test of whether the Centre is willing to trade speed for legitimacy.

Prelims Pointers
- The SHANTI Bill 2025 was introduced in the Lok Sabha on 15 December 2025; passed by Lok Sabha on 17 December and Rajya Sabha on 18 December; received Presidential assent on 20 December 2025.
- SHANTI stands for Sustainable Harnessing and Advancement of Nuclear Energy for Transforming India.
- The Bill repeals and replaces both the Atomic Energy Act 1962 and the Civil Liability for Nuclear Damage Act 2010, consolidating the framework into a single statute.
- The Atomic Energy Commission was established on 10 August 1948 under the chairmanship of Homi J. Bhabha.
- The Department of Atomic Energy was created in 1954 and reports directly to the Prime Minister.
- India’s three-stage nuclear programme was articulated by Bhabha in 1954: Stage I PHWR, Stage II FBR, Stage III thorium-fuelled AHWR.
- Pokhran-I (Smiling Buddha) was conducted on 18 May 1974; Pokhran-II on 11 and 13 May 1998.
- The NSG waiver for India was granted on 6 September 2008; the 123 Agreement followed.
- The India-specific IAEA Safeguards Agreement entered into force in 2009; the Additional Protocol in 2014.
- India’s installed nuclear capacity is 8,180 MW across 24 operating reactors; nuclear share in electricity mix is around 2.8%.
- The Prototype Fast Breeder Reactor (PFBR) at Kalpakkam, operated by BHAVINI, achieved first criticality in March 2024 (500 MW).
- Tarapur Atomic Power Station (TAPS), commissioned in 1969, is India’s oldest operating nuclear plant.
- Kudankulam hosts India’s only operating Russian VVER-1000 reactors (Units 1 and 2 commissioned 2014 and 2017).
- The Bharat Small Modular Reactor (BSMR) programme was announced in Union Budget 2024-25; the Nuclear Energy Mission outlay is Rs 20,000 crore.
- The Convention on Supplementary Compensation for Nuclear Damage (CSC) was ratified by India in 2016.
- Operator liability under the SHANTI Act 2025 is restructured from a fixed Rs 1,500 crore cap to a tiered, capacity-linked range running approximately Rs 100 crore to Rs 3,000 crore.
- Foreign Direct Investment in nuclear power projects is capped at 49% under the SHANTI Act 2025, with majority control retained on the Indian side; uranium enrichment, heavy-water production and spent-fuel reprocessing remain reserved to the Central Government.
Mains Practice Questions
- The Atomic Energy (Amendment) Bill 2025 (SHANTI) opens India’s civil nuclear sector to private participation for the first time since 1962. Critically examine the structural rationale for this pivot and the regulatory safeguards required to make it credible. (15 marks)
- Discuss India’s three-stage nuclear programme as conceived by Homi J. Bhabha. Where does the programme stand today, and how does the SHANTI Bill alter the technology trajectory? (15 marks)
- The Civil Liability for Nuclear Damage Act 2010 effectively froze India’s nuclear pipeline by creating supplier-side recourse risk. Evaluate the proposed amendments to Section 17(b) and their consistency with the absolute liability doctrine in M.C. Mehta v. Union of India (1987). (15 marks)
- “India’s 100 GW nuclear target by 2047 is less an energy Bill than a climate Bill written in nuclear language.” Examine this claim in light of India’s NDCs and net-zero-by-2070 commitment. (10 marks)
- The Bharat Small Modular Reactor (BSMR) programme is positioned as the technology vector for nuclear capacity scaling. Discuss the technical, economic and siting advantages of SMRs against conventional 1,000 MW units. (10 marks)
- Compare India’s civil nuclear trajectory with that of China since 2008. What institutional, financing and supply-chain choices explain the divergence in installed capacity? (15 marks)
- Examine the role of the Atomic Energy Regulatory Board in licensing private nuclear operators. Should AERB be granted full statutory independence under a separate Nuclear Safety Regulatory Authority? (10 marks)
- The 1948 Atomic Energy Act, the 1962 Atomic Energy Act, the NSG waiver of 2008, and the SHANTI Bill of 2025 mark four inflection points in India’s civil nuclear story. Trace this trajectory and assess what each transition reveals about the relationship between strategic autonomy and economic openness. (15 marks)
Conclusion
The SHANTI Bill, read as a whole, completes a sixty-three-year arc that began with Homi Bhabha’s 1962 statute and the proposition that atomic energy was too consequential to be left to private hands. The 2025 amendment does not abandon that proposition — the 49% cap on foreign direct investment, the centralised fuel allocation, and the AERB’s licensing chokepoint preserve Union strategic control — but it does concede that the proposition cannot be financed, executed or scaled by the Union alone in the climate-pressed two decades ahead. Whether the resulting hybrid architecture delivers on the 100 GW target depends less on the legal text and more on three downstream variables: the speed at which the Atomic Energy Regulatory Board can license private operators without compromising safety, the willingness of foreign vendors to re-enter under the amended liability regime, and the political durability of fleet-mode procurement once the first SMR sites face local opposition.
For the year ahead, three watchpoints follow directly from the Bill. The first is the Standing Committee on Energy’s report, expected by Q1 2026, which will determine whether the deemed-approval clock on state NOCs survives in its current form or is restructured along cooperative-federalism lines. The second is the first private-operator licence application — most likely from Tata Power or Reliance Industries in partnership with NPCIL on a brownfield site — which will set the regulatory precedent for everything that follows. The third is the BSMR programme’s execution against its 2033 Tarapur deployment date for the BSMR-200 and SMR-55; any slippage compounds rapidly against the 2047 schedule, and the 100 GW headline number begins to look notional.
For the aspirant, the line worth carrying into the answer booklet is that the SHANTI Bill is the moment when India’s civil nuclear sector stopped being a sovereignty project and became an industrial policy. The next decade of nuclear regulation will be judged not on whether the 100 GW number is reached but on whether the hybrid public-private architecture it has invented can be made to combine the discipline of a regulated utility with the execution speed of a competitive market — a question the Bill poses with unusual clarity but does not yet answer.
Frequently Asked Questions
What is the SHANTI Bill, 2025, and which laws does it replace?
SHANTI stands for Sustainable Harnessing and Advancement of Nuclear Energy for Transforming India. Introduced in the Lok Sabha on 15 December 2025, the Bill replaces the Atomic Energy Act of 1962 and consolidates the Civil Liability for Nuclear Damage Act, 2010 into a single statute. The 1962 Act had reserved the construction, ownership and operation of nuclear power plants exclusively for the Union government, channelled through the Nuclear Power Corporation of India Limited (NPCIL) and, for the fast-reactor stream, BHAVINI. The new framework opens civil nuclear generation to qualified private operators and rewrites the liability rules that had kept foreign reactor vendors out of the Indian market since 2010.
Can private companies build and operate nuclear power plants in India under the SHANTI Bill?
Yes, but only as licensed operators and only within limits. The Bill creates a category of licensed private operator, meaning a domestically incorporated company that satisfies the technical, financial and security-clearance thresholds prescribed by the Atomic Energy Regulatory Board (AERB), which the Bill grants statutory status as an independent regulator. Foreign direct investment in nuclear power projects is capped at 49% with majority control retained on the Indian side, and uranium enrichment and isotopic separation, heavy-water production, spent-fuel management and reprocessing, and uranium and thorium exploration remain reserved exclusively for the Central Government. Reliance Industries, Tata Power, Adani Power, Vedanta and L&T are widely reported to have submitted expressions of interest.
How does the SHANTI framework change the operator liability cap under the Civil Liability for Nuclear Damage Act, 2010?
It replaces the flat Rs 1,500 crore operator cap with a tiered, capacity-linked structure set out in the Second Schedule. The tiers run from Rs 100 crore for installations up to 150 MW thermal (and for fuel-cycle and transport activities), to Rs 300 crore for 150-750 MW, Rs 750 crore for 750-1,500 MW, Rs 1,500 crore for 1,500-3,600 MW, and Rs 3,000 crore for installations above 3,600 MW thermal. The time limit for tort claims is harmonised with the Convention on Supplementary Compensation framework. The India Nuclear Insurance Pool, launched in June 2015 with a Rs 1,500 crore capacity underwritten by GIC Re and eleven other non-life insurers, is statutorily recognised as a vehicle for operator insurance.
Why did Section 17(b) of the Civil Liability for Nuclear Damage Act, 2010 keep foreign reactor vendors out of India?
Section 17(b) gave the operator a right of recourse against the equipment supplier in the event of patent or latent defect, effectively channelling liability back to the vendor in a way that no other Convention on Supplementary Compensation jurisdiction did. Westinghouse, GE Hitachi, French Areva (later EDF) and Russia’s Rosatom all read the clause as commercially uninsurable, and the 9,900 MW Jaitapur EPR project in Maharashtra and the Kovvada AP-1000 site in Andhra Pradesh stayed on paper for over a decade. The SHANTI framework recasts supplier liability as contractual rather than statutory, letting operator and supplier negotiate the scope of recourse within the Convention on Supplementary Compensation framework, which India ratified in 2016.
What is India’s installed nuclear capacity, and how realistic is the 100 GW by 2047 target?
India’s installed nuclear capacity stands at roughly 8,180 MW across 24 operating reactors, contributing about 2.8% of the national electricity mix. Adding the under-construction pipeline of around 7,300 MW (Kakrapar Unit 4, Rajasthan 7-8, Kudankulam 3-6 and GHAVP 1-2) yields roughly 15.5 GW on the grid by the early 2030s under best-case execution. Reaching 100 GW therefore requires about 85 GW of additional capacity in 15 years, an annual addition of around 5.7 GW, which is more than five times the average rate India has actually achieved since 2000. NPCIL alone can credibly deliver perhaps 30-35 GW of that, so the rest has to come from private operators, foreign-vendor partnerships and the small modular reactor pipeline.
What is the Bharat Small Modular Reactor (BSMR) programme?
BSMR is India’s small-reactor push, announced in Union Budget 2024-25 and operationalised through the Nuclear Energy Mission in Budget 2025-26 with an initial outlay of Rs 20,000 crore. The flagship BSMR-200 is a 200 MWe pressurised heavy water reactor derived from the indigenous IPHWR-220 design, using slightly enriched uranium fuel and passive safety features, developed jointly by NPCIL and BARC with conceptual design completed in March 2025. The BSMR-200 and a 55 MWe SMR-55 variant are targeted for deployment at Tarapur by 2033. SMRs are factory-fabricated and transported to site as modules, need land footprints of under 50 hectares against the 800-1,500 hectare exclusion zones around conventional 1,000 MW units, and get a separate licensing pathway, with steel, aluminium, refining and data centres named as eligible captive offtakers.
Where does India’s three-stage nuclear programme stand today?
Stage I is mature, Stage II has barely started, and Stage III remains a 2040s prospect. Stage I uses natural uranium in Pressurised Heavy Water Reactors to generate electricity and breed plutonium-239, with the indigenous 540 MW and 700 MW PHWR designs running at Tarapur, Kakrapar, Kaiga and Rajasthan Atomic Power Station. Stage II uses that plutonium in Fast Breeder Reactors with a U-238 and thorium blanket, and the 500 MW Prototype Fast Breeder Reactor at Kalpakkam, operated by BHAVINI, has run about sixteen years behind its original schedule. Stage III envisages thorium-fuelled Advanced Heavy Water Reactors running on U-233 bred from thorium, and although IGCAR has demonstrated the fuel cycle, a commercial Stage III reactor is not expected before the 2040s. Bhabha framed the sequence in 1954 around India’s thorium reserves, the world’s largest, concentrated in Kerala’s monazite sands.
What are the main criticisms of the SHANTI Bill?
Three lines of criticism dominate. M.V. Ramana of the University of British Columbia argues that the 100 GW target rests on optimistic levelised-cost assumptions, ignores the construction-time overruns that hit every Generation III+ project worldwide (Olkiluoto, Flamanville, Vogtle, Hinkley Point C), and underweights solar-plus-storage costs that have fallen by over 80% in the same window in which nuclear costs rose. The Centre for Strategic and International Studies has flagged that the liability changes, though convergent with the Convention on Supplementary Compensation, may still be challenged before the Supreme Court as inconsistent with the absolute liability doctrine in M.C. Mehta v. Union of India (1987). Former Atomic Energy Commission member A. Gopalakrishnan holds that genuine regulatory independence for the AERB, of the kind the 2011 Nuclear Safety Regulatory Authority Bill proposed, is a precondition for licensing private operators, while Tamil Nadu, Kerala and West Bengal read the deemed-approval clock on state No Objection Certificates as an erosion of cooperative federalism.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.