Why in News?
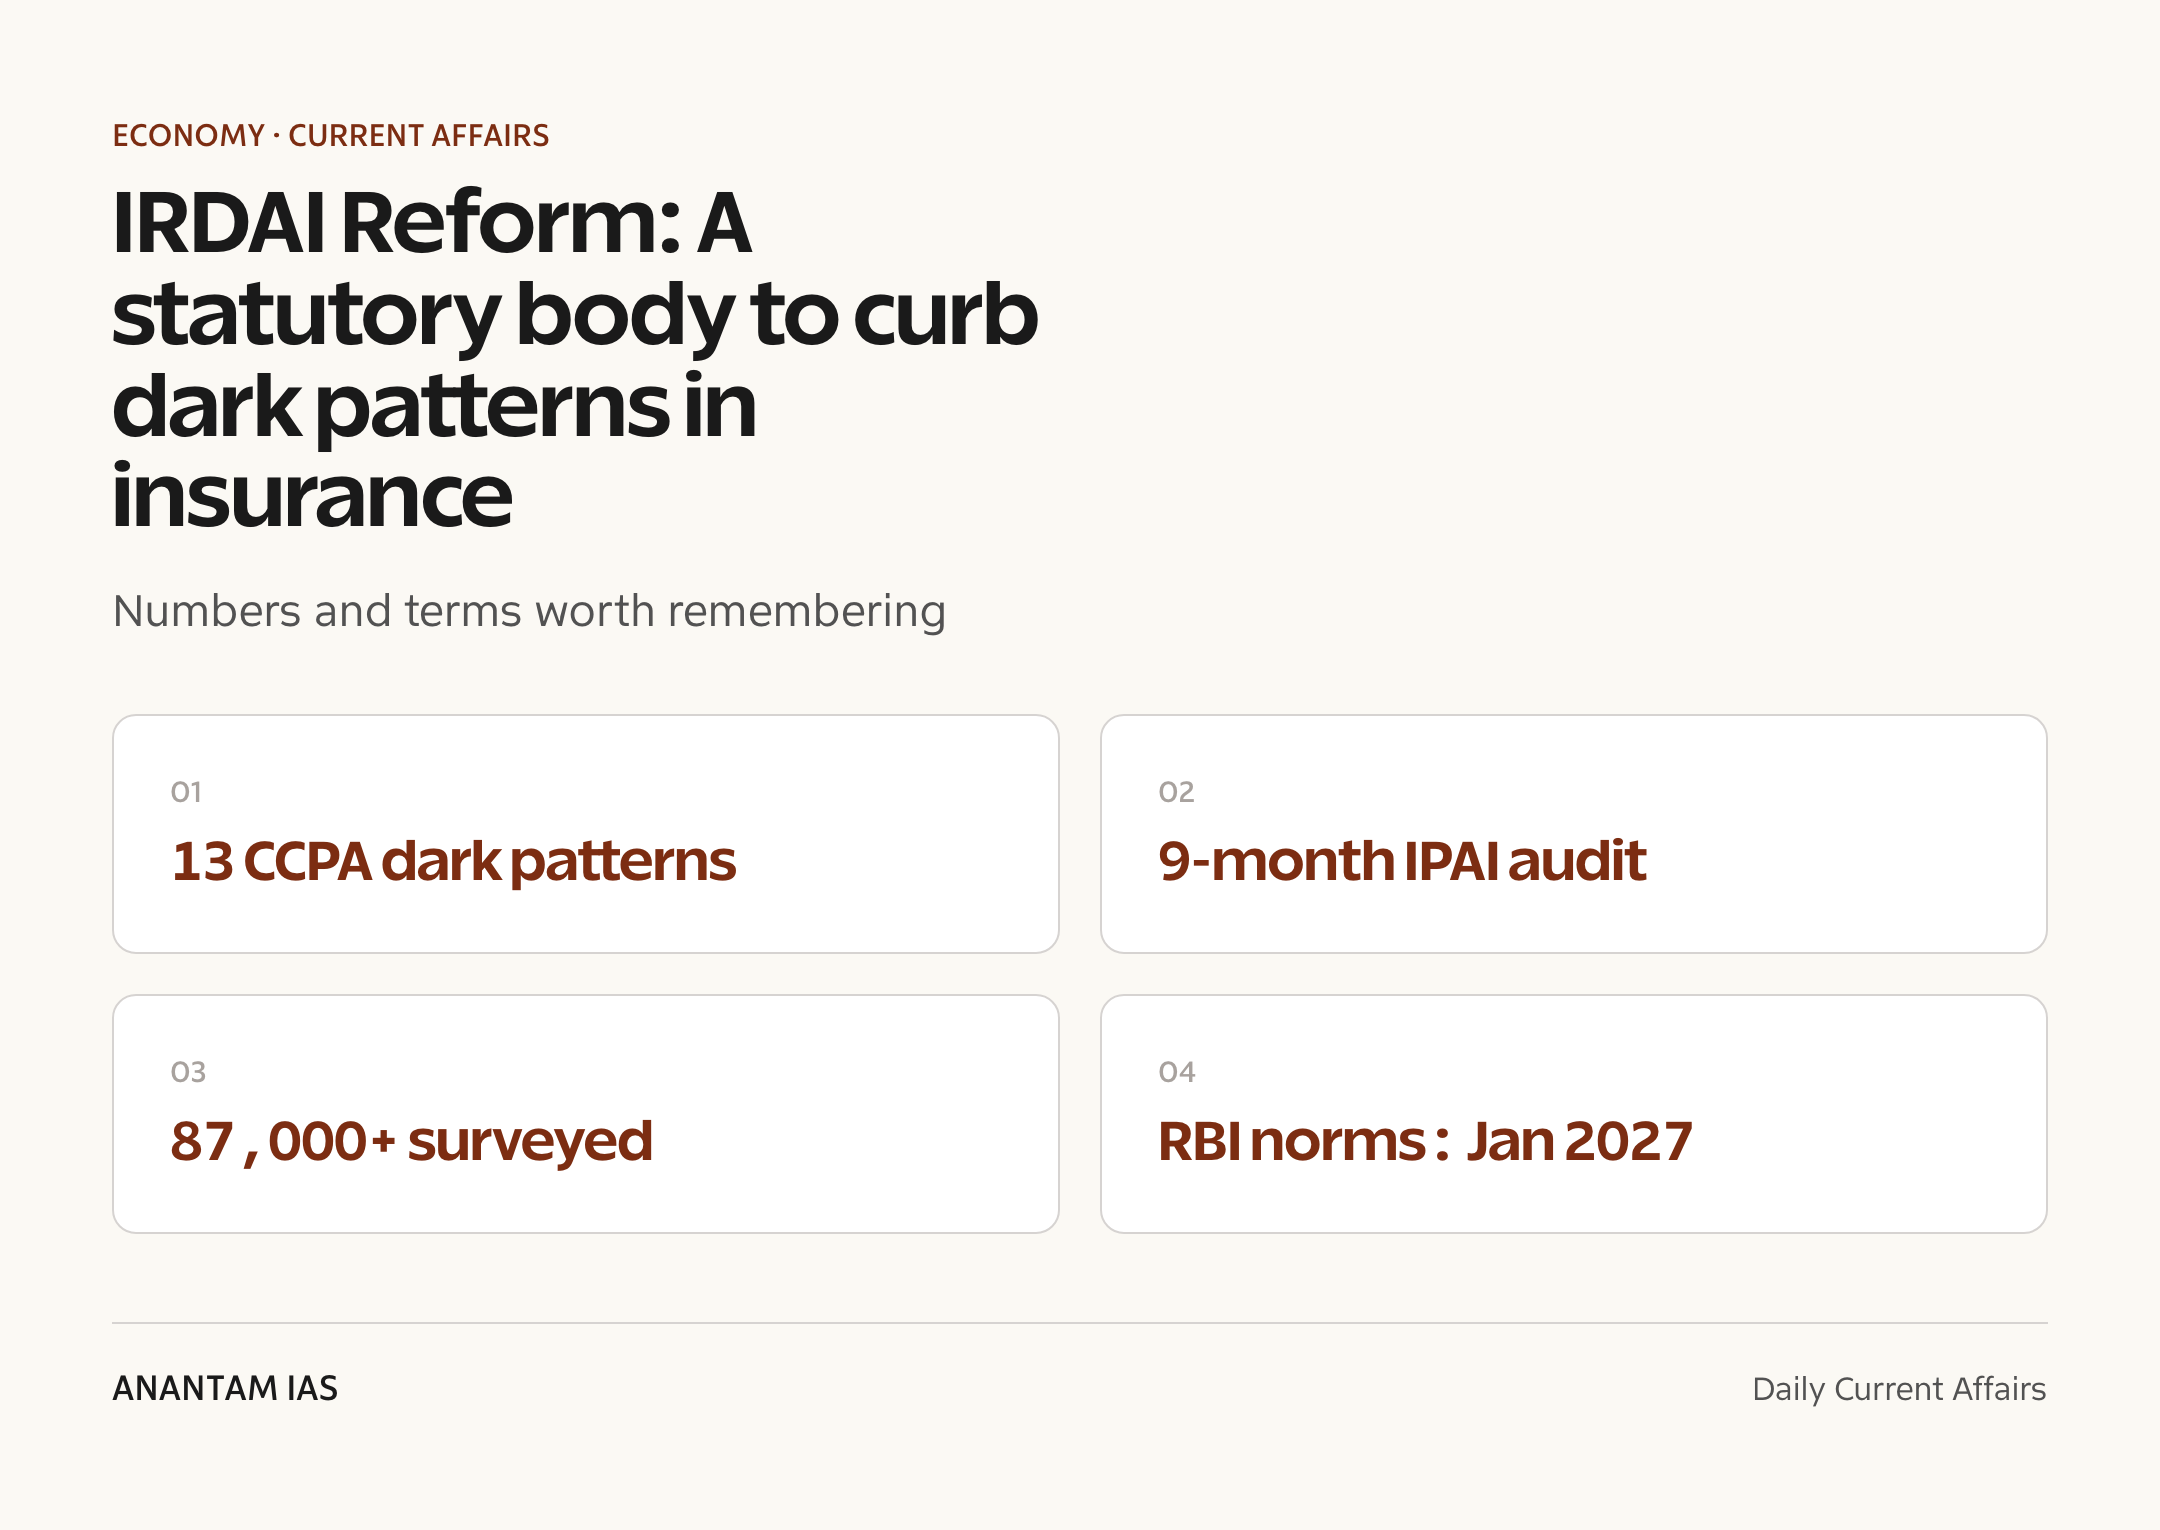
The Insurance Regulatory and Development Authority of India (IRDAI) has partnered with the Institute of Public Auditors of India (IPAI) to independently study and monitor dark patterns — manipulative digital design practices — across the insurance industry over a period of nine months. The Indian Express reported the move on July 2, 2026, after IRDAI Chairman Ajay Seth announced it at an industry event in Mumbai.
The trigger was telling: when IRDAI directed insurers in April 2026 to self-assess their platforms against the dark-pattern guidelines and report back, almost every insurer claimed it had none. The regulator has now moved from self-certification to independent third-party monitoring, and will follow up with a consultation paper on insurance distribution reforms in July, targeting mis-selling and the commission-based distribution model.
- IPAI, a body of public-audit professionals drawn from the CAG fraternity, will track over nine months which insurers use dark patterns and which don’t.
- The April 2026 directive had asked insurers to align with the CCPA’s dark-pattern guidelines, run a self-assessment and submit action plans — the near-universal denial prompted the external audit.
- A LocalCircles survey of over 87,000 respondents across 341 districts found about 80% faced hidden charges, difficulty in cancelling policies or forced data sharing on insurance platforms.
- Around 90% of surveyed users reported being pushed through unsolicited calls and messages to buy or renew policies.
- IRDAI’s July consultation paper is expected to propose steps to curb mis-selling across distribution channels, improve transparency and rework commission structures.
- The move follows the RBI’s framework curbing mis-selling and dark patterns by banks, which takes effect from January 1, 2027.
The development matters in the context of:
- This sits at the junction of financial regulation and consumer protection — a behavioural-economics problem (manipulation by design) being answered with institutional machinery (audit, disclosure, distribution reform).
- Trust is the binding constraint on financial inclusion in insurance: India’s insurance penetration was about 3.7% of GDP in FY24, and manipulative selling repels precisely the hesitant first-time buyer.
- It also illustrates regulatory convergence: the CCPA, RBI and IRDAI are now acting on the same harm — dark patterns — within their respective jurisdictions.
UPSC Relevance
Prelims Relevance
- IRDAI — statutory body under the IRDA Act, 1999; headquartered in Hyderabad; set up on the recommendations of the Malhotra Committee (1994).
- Dark patterns — deceptive user-interface designs that manipulate users into choices they didn’t intend; regulated in India by the CCPA guidelines, 2023.
- CCPA — Central Consumer Protection Authority, established under the Consumer Protection Act, 2019; its 2023 guidelines specify 13 dark patterns.
- Examples of the 13 specified patterns: false urgency, basket sneaking, confirm shaming, subscription trap, drip pricing, bait and switch, nagging, interface interference, forced action, disguised advertisement, trick wording, SaaS billing, rogue malware.
- Institute of Public Auditors of India (IPAI) — professional body of public auditors (est. 1996) engaged by IRDAI for the nine-month dark-patterns study.
- RBI framework on mis-selling by banks — bans compulsory bundling and dark patterns, mandates explicit consent and refunds; effective January 1, 2027.
- Digital Personal Data Protection (DPDP) Act, 2023 — consent-based data processing; relevant to forced data-sharing patterns.
- Bima Trinity — Bima Sugam (digital marketplace), Bima Vistaar (composite cover), Bima Vaahak (women-led distribution); part of IRDAI’s Insurance for All by 2047 vision.
- India’s insurance penetration: about 3.7% of GDP in FY24 (IRDAI Annual Report).
Mains Relevance
GS Paper 3
- Financial-sector regulation: mis-selling as a market failure; incentive misalignment in commission-based distribution.
- Financial inclusion: why consumer trust is infrastructure — low insurance penetration despite digital distribution.
- Digital economy: platform design, behavioural manipulation and the limits of caveat emptor online.
GS Paper 2
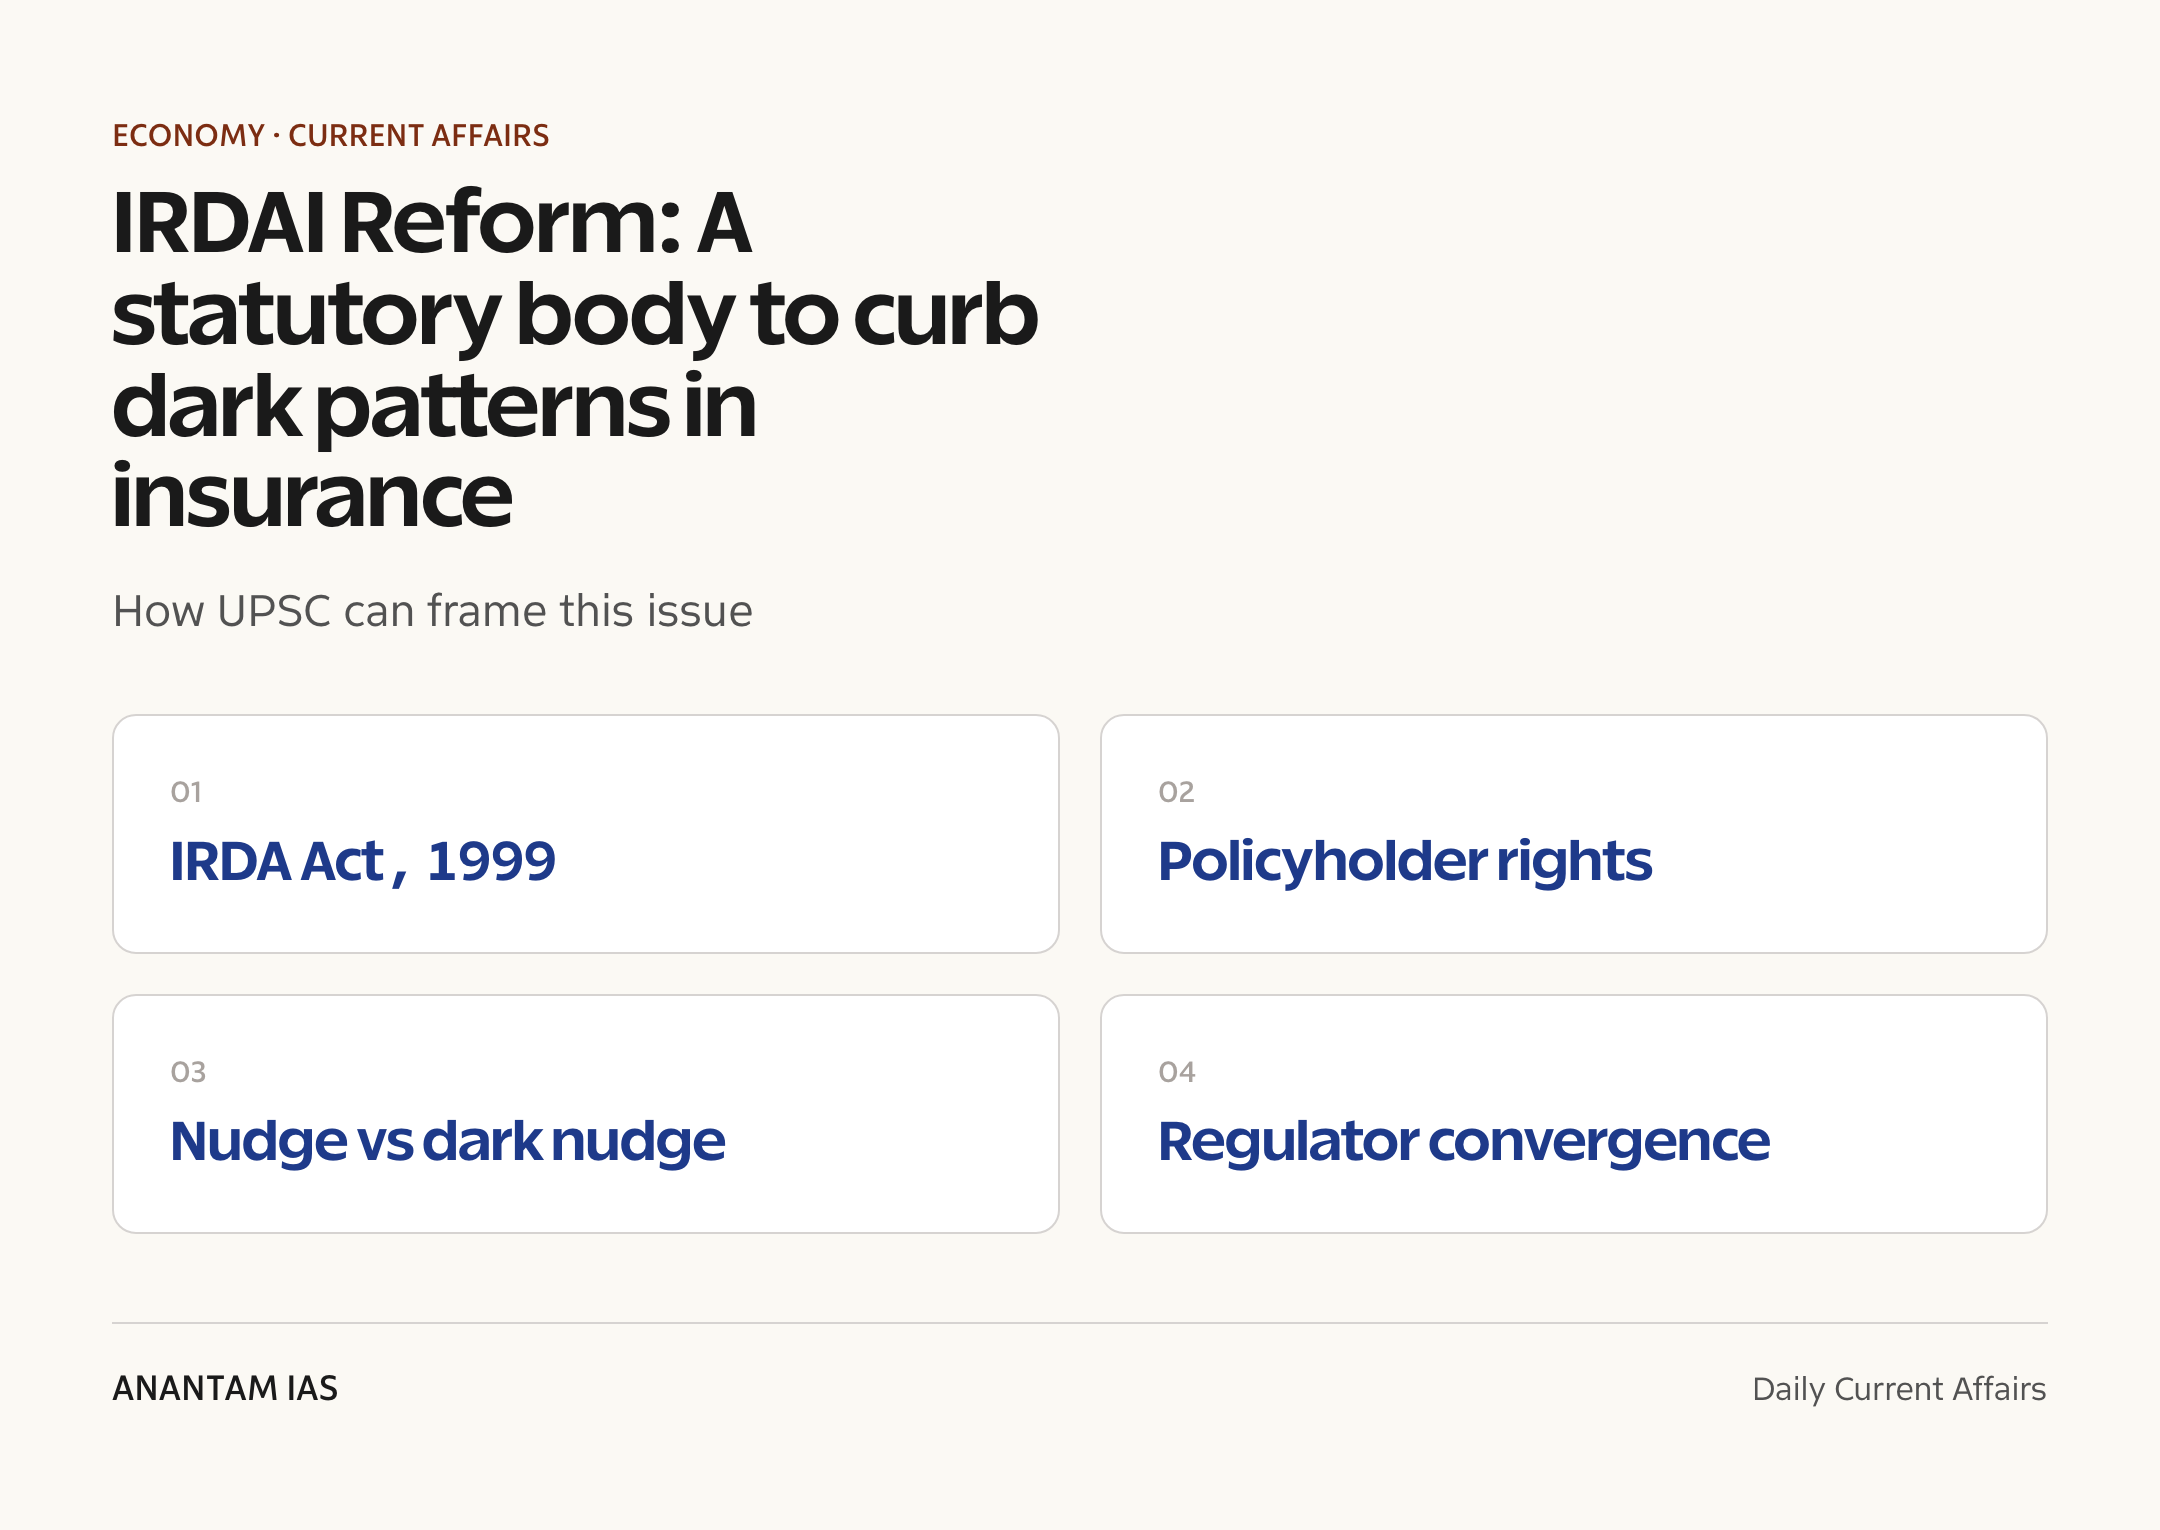
- Statutory and regulatory bodies: IRDAI’s mandate under the IRDA Act, 1999; independent audit as a governance instrument.
- Regulatory coordination: CCPA–RBI–IRDAI acting on the same consumer harm — case for harmonised norms.
- Government policies for vulnerable sections: protecting the first-time financial consumer.
GS Paper 4
- Ethics of persuasion in business: the line between a legitimate nudge and a manipulative dark pattern; corporate governance and probity.
Essay
- Trust is the true currency of a financial system — regulation can protect it, only conduct can earn it.
- Technology amplifies both choice and manipulation: the case for designing markets around the consumer.
- Financial inclusion without financial protection is a promise half kept.
Background and Context
What Are Dark Patterns?
Dark patterns are design tricks built into websites and apps that steer users into decisions they wouldn’t otherwise make.
- The term covers deceptive user-interface and user-experience practices that pressurise, mislead or trap users — into sharing data, paying more, or staying subscribed.
- India’s legal definition comes from the Guidelines for Prevention and Regulation of Dark Patterns, 2023, notified by the Central Consumer Protection Authority (CCPA) under the Consumer Protection Act, 2019.
- The guidelines specify 13 dark patterns: false urgency, basket sneaking, confirm shaming, forced action, subscription trap, interface interference, bait and switch, drip pricing, disguised advertisement, nagging, trick question/trick wording, SaaS billing and rogue malware.
- In insurance, the typical forms are: forcing users to hand over personal data before showing quotes, making policy cancellation deliberately hard, hiding charges deep in the purchase flow, and relentless spam calls pushing products.
- Behavioural economists distinguish a nudge (choice-preserving help toward a better decision) from sludge or dark nudges (friction and framing engineered against the user’s interest) — dark patterns are the latter, at industrial scale.
IRDAI: The Regulator Behind the Move
The exam-relevant anchor here is the institution itself — a statutory financial regulator with an explicit policyholder-protection mandate.
- IRDAI is a statutory body constituted under the Insurance Regulatory and Development Authority Act, 1999, and became operational in April 2000.
- It was created on the recommendations of the Malhotra Committee (1994) on insurance-sector reforms; headquarters: Hyderabad.
- Composition: a chairperson, up to five whole-time members and four part-time members, all appointed by the Government of India.
- Its mandate under the Act: protect policyholders’ interests, and regulate, promote and ensure the orderly growth of the insurance and reinsurance business.
- Its current agenda is framed by the Insurance for All by 2047 vision and the Bima Trinity — Bima Sugam, Bima Vistaar and Bima Vaahak.
- The current chairman, Ajay Seth, has framed the dark-patterns drive as a trust problem: financial inclusion must be “more understandable, more trusted, and more actionable”.
The New Monitoring Mechanism
IRDAI’s response escalated in three steps once self-regulation visibly failed.
- Step 1 — April 2026 directive: insurers were told to align with the CCPA’s dark-pattern guidelines, run a self-assessment of their digital platforms and submit their observations and action plans.
- Step 2 — the denial problem: almost all insurers reported they had no dark patterns. As Chairman Seth put it, that response is exactly why the regulator went external.
- Step 3 — independent audit: IRDAI has engaged the Institute of Public Auditors of India (IPAI) — a professional body of public-audit experts drawn from the CAG-led audit fraternity, set up in 1996 — to study and monitor the industry for nine months and establish who uses dark patterns and who doesn’t.
- A consultation paper on insurance distribution is due in July 2026 — expected to cover curbs on mis-selling across channels, better transparency, and changes to the commission-based distribution model.
- Seth also flagged a specific practice for scrutiny: insurers demanding extensive personal information before revealing product, price or performance details — which kills product discovery for hesitant buyers.
Mis-Selling: How Big Is the Problem?
Dark patterns are the digital face of a much older disease in Indian insurance — mis-selling.
- Mis-selling means selling a financial product through unfair, deceptive or unsuitable means — wrong product for the buyer’s profile, incomplete or misleading information, or sales without informed consent.
- Agents, brokers and bancassurance channels have long been accused of pushing complex products — endowment and ULIP-style policies in particular — onto customers who wanted simple protection or savings.
- A LocalCircles survey covering over 87,000 respondents across 341 districts found roughly 80% had faced hidden charges, cancellation hurdles or forced data sharing on insurance platforms.
- About 90% said they were repeatedly pushed through unsolicited calls and messages to buy or continue policies.
- The study covered India’s biggest digital insurance marketplaces — Policybazaar, Acko and Tata AIG among them — showing the problem is industry-wide, not confined to fringe players.
- The macro cost: mistrust suppresses demand in a market where insurance penetration is already only about 3.7% of GDP (FY24) — far below the world average.
The Wider Regulatory Architecture
IRDAI isn’t acting alone — three regulators now target the same behavioural harm from different statutory bases.
- CCPA (Consumer Protection Act, 2019): its 2023 guidelines make deploying any of the 13 specified dark patterns an unfair trade practice, applicable to all platforms, advertisers and sellers in India.
- RBI: a comprehensive framework curbing mis-selling by banks takes effect from January 1, 2027 — it bans compulsory bundling of third-party products, requires explicit customer consent and suitability assessment, mandates refunds plus compensation where mis-selling is established, and expressly prohibits dark patterns. Details are on the RBI website.
- Seth acknowledged the RBI’s guidelines and noted the overlap: banks selling insurance are IRDAI licensees too — “now it is our turn to bring in suitable guidelines for them”.
- IRDAI’s own toolkit: the Protection of Policyholders’ Interests regulations (consolidated in 2024), the Bima Bharosa grievance portal, and the Insurance Ombudsman system for policyholder disputes.
- DPDP Act, 2023: forced data sharing — the most common insurance dark pattern — also collides with the Act’s requirement of free, specific and informed consent for processing personal data.
Significance and the Sceptic's View
The reform matters beyond insurance — it tests whether Indian regulators can police design, not just disclosure.
- Trust as infrastructure: for first-time buyers “already on the fence”, one manipulative funnel can mean permanent exit from formal insurance — undermining Insurance for All by 2047.
- From disclosure to design: classic regulation polices what firms say; dark-pattern regulation polices how choice architecture is built. That’s a conceptual shift in Indian financial regulation.
- Industry impact: an analyst quoted by the Indian Express expects only a short-term sales hit for insurers — largely inconsequential — while tighter norms build durable consumer trust.
- Sceptic’s concerns: the self-assessment episode shows self-regulation failed; enforcement capacity for continuous UI/UX audits is untested; and three regulators acting separately risks overlapping jurisdiction and inconsistent standards.
- Compliance burden: smaller insurtech distributors may struggle with parallel CCPA, RBI and IRDAI norms — a harmonised code would cut duplication.
- This is a live case study for the governance theme of regulatory bodies adapting to the digital economy.
Way Forward
Codify and enforce
- Convert the IPAI study’s findings into binding conduct regulations with graded penalties, rather than advisory circulars.
- Publish audit outcomes — a public scorecard of platforms — so reputational pressure reinforces enforcement.
- Harmonise definitions and penalties across CCPA, RBI and IRDAI so a single dark pattern doesn’t face three inconsistent rulebooks.
Fix the incentive engine
- Use the July consultation to rework commission structures — trail-based and persistency-linked pay over upfront commissions that reward one-time pushy sales.
- Mandate suitability assessment and meaningful free-look windows for complex products, mirroring the RBI’s refund-plus-compensation standard.
- Let consumers see product, price and performance before KYC — quote-first journeys as the default, with Bima Sugam enabling neutral comparison.
Alongside supply-side fixes, invest in financial literacy so consumers recognise manipulation — an informed buyer is the cheapest regulator of all.
Conclusion
IRDAI’s dark-patterns audit is a small mechanism with a large signal: when an industry certifies itself clean against the evidence of 87,000 consumers, the regulator’s answer is independent verification. Pairing the IPAI study with distribution reform attacks both the symptom (manipulative interfaces) and the cause (commissions that reward mis-selling).
For aspirants, the topic bundles three durable syllabus threads — a statutory regulator exercising its policyholder-protection mandate, consumer protection law extending into digital design, and the economics of trust and financial inclusion. Watch the July consultation paper and the RBI framework’s January 2027 rollout for the next developments.
UPSC Practice Questions
Prelims MCQ 1
With reference to the Insurance Regulatory and Development Authority of India (IRDAI), consider the following statements:
- It is a statutory body established under an Act of Parliament.
- It was set up on the recommendations of the Malhotra Committee.
- It is headquartered in Mumbai.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
IRDAI is a statutory body under the IRDA Act, 1999 (statement 1 correct), created on the recommendations of the Malhotra Committee, 1994 (statement 2 correct). It is headquartered in Hyderabad, not Mumbai (statement 3 incorrect).
Prelims MCQ 2
The ‘Guidelines for Prevention and Regulation of Dark Patterns, 2023’, which specify 13 manipulative design practices such as false urgency, drip pricing and subscription trap, were issued by:
(a) The Reserve Bank of India (b) The Insurance Regulatory and Development Authority of India (c) The Central Consumer Protection Authority (d) The Ministry of Electronics and Information Technology
Answer: (c) The Central Consumer Protection Authority
Explanation:
The CCPA, established under the Consumer Protection Act, 2019, notified the dark-patterns guidelines in 2023, specifying 13 patterns and treating their use as an unfair trade practice. IRDAI and RBI have since applied the concept within their own sectors.
UPSC Mains Questions
- Dark patterns sit at the intersection of consumer protection, data protection and financial regulation. In the light of recent measures by the CCPA, RBI and IRDAI, examine why manipulative digital design demands regulatory coordination rather than isolated sectoral action.
- Mis-selling of insurance undermines both policyholder welfare and India’s goal of ‘Insurance for All by 2047’. Analyse the structural causes of mis-selling in India and evaluate whether reforming the commission-based distribution model can address them.
- Self-regulation is the first casualty of misaligned incentives. Discuss with reference to IRDAI’s decision to commission an independent nine-month audit of dark patterns after insurers’ self-assessments denied their existence.
Sources: IRDAI and Indian Express Explained.
Frequently Asked Questions
What are dark patterns in insurance?
Dark patterns are manipulative website and app design tricks that push users into unintended choices — forcing personal data before showing quotes, hiding charges, making cancellation difficult, or bombarding users with calls. India’s CCPA guidelines, 2023 specify 13 such patterns and treat their use as an unfair trade practice.
What has IRDAI announced on dark patterns?
IRDAI has partnered with the Institute of Public Auditors of India (IPAI) to independently study and monitor dark patterns across insurers for nine months. It follows an April 2026 directive asking insurers to self-assess, to which nearly all claimed they had no dark patterns.
What is the Institute of Public Auditors of India?
IPAI is a professional body of public-audit experts, set up in 1996 and drawn largely from the CAG-led audit community. IRDAI has engaged it as an independent third party to establish which insurers use dark patterns, replacing reliance on the industry’s own self-certification.
Is IRDAI a statutory body?
Yes. IRDAI was constituted under the Insurance Regulatory and Development Authority Act, 1999, on the Malhotra Committee’s recommendations, and became operational in 2000. Headquartered in Hyderabad, it regulates the insurance sector and is legally mandated to protect policyholders’ interests.
What are the CCPA’s 13 dark patterns?
The CCPA’s 2023 guidelines list false urgency, basket sneaking, confirm shaming, forced action, subscription trap, interface interference, bait and switch, drip pricing, disguised advertisement, nagging, trick question or wording, SaaS billing, and rogue malware. They apply to all platforms, advertisers and sellers in India.
How is the RBI tackling mis-selling by banks?
The RBI’s framework, effective January 1, 2027, bans compulsory bundling of third-party products, requires explicit customer consent and suitability checks, prohibits dark patterns, and mandates full refunds plus compensation where mis-selling is established. Banks selling insurance also remain IRDAI licensees.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.