Why in News?
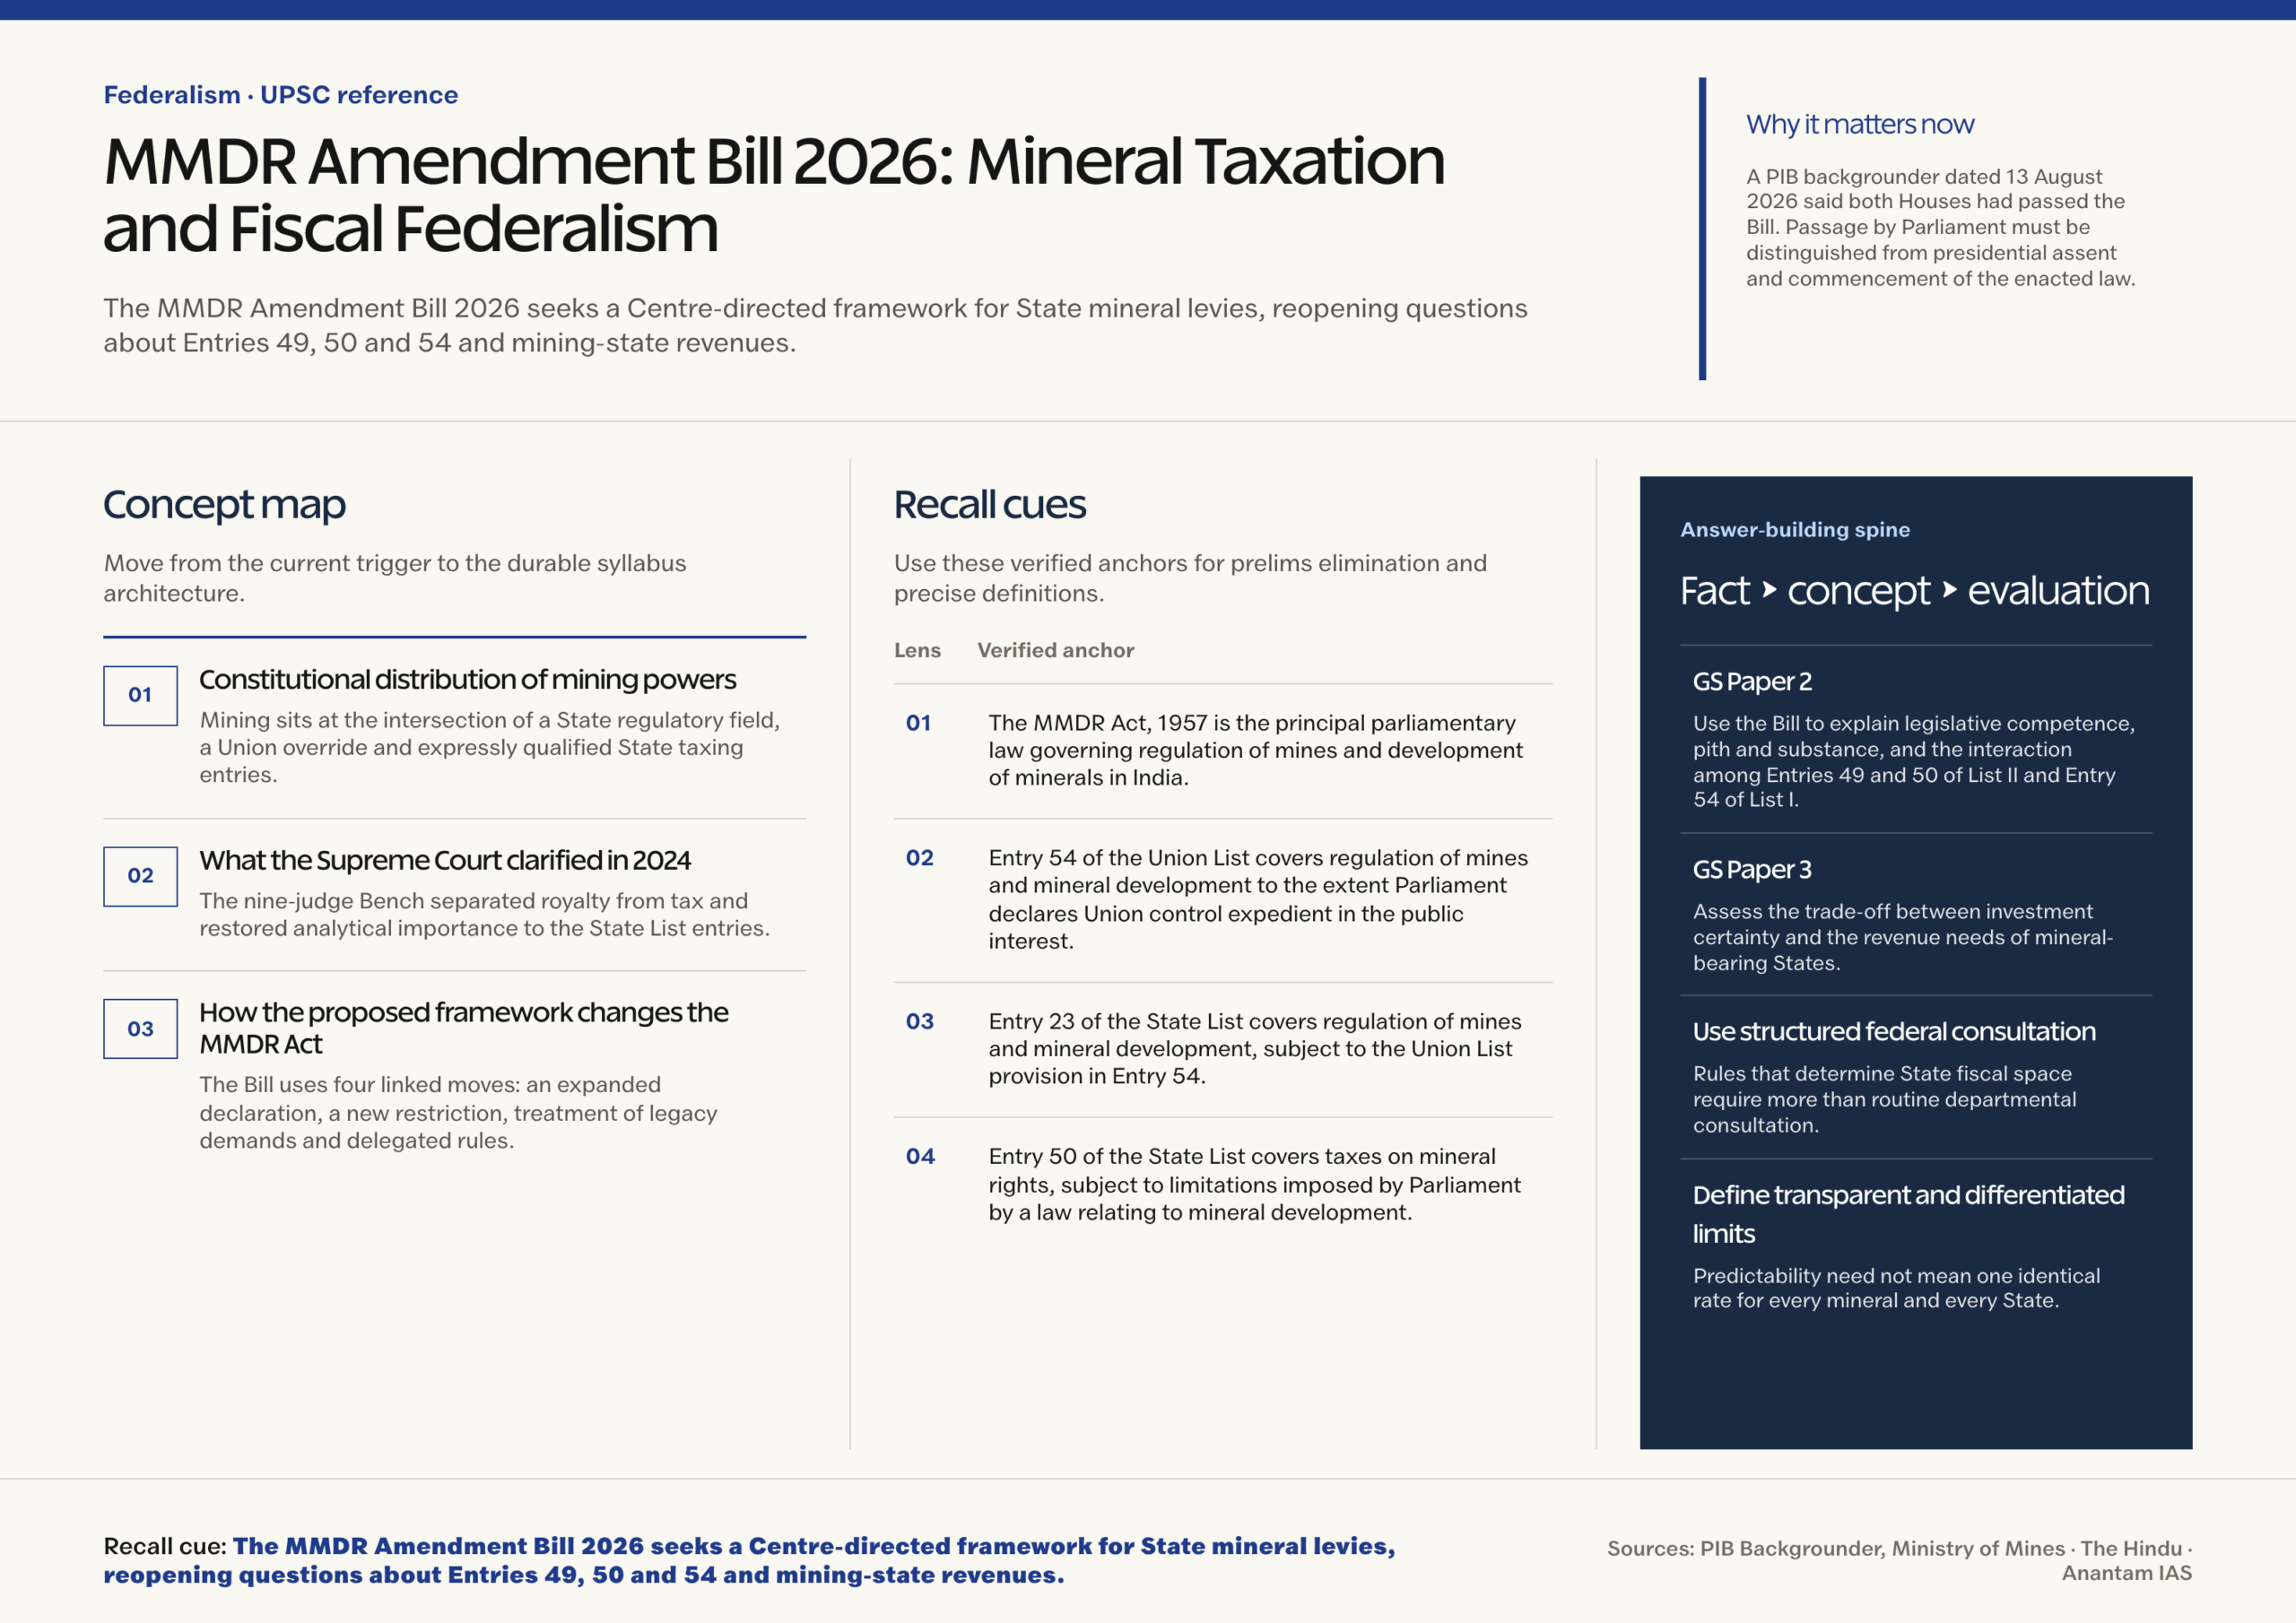
Parliament passed the Mines and Minerals (Development and Regulation) Amendment Bill, 2026 , which seeks to regulate State taxes, cesses and other levies on mineral rights and mineral-bearing land through conditions or restrictions prescribed by the Union government.
- A PIB backgrounder dated 13 August 2026 said both Houses had passed the Bill. Passage by Parliament must be distinguished from presidential assent and commencement of the enacted law.
- The Bill proposes a new Section 9D: a State levy on mineral rights or mineral-bearing land, whether calculated by quantity, value, royalty or another basis, may operate only under Union-prescribed conditions or restrictions.
- It would widen the declaration of Union control under Section 2 of the MMDR Act to cover mineral-bearing land identified according to centrally prescribed parameters, alongside regulation of mines and mineral development.
- It would treat unpaid or uncollected pre-commencement levies as invalid, while denying refunds of amounts already deposited or recovered before commencement.
- It would amend Section 13 to authorise Central rules specifying the conditions or restrictions under which States may impose the covered levies.
- The controversy follows the Supreme Court’s 2024 ruling in Mineral Area Development Authority v. Steel Authority of India, which held by an 8:1 majority that royalty is not a tax and that States possess legislative.
- The dispute is not merely about who receives money. It concerns how the Constitution divides regulatory control, taxing power and responsibility for mining-related social and ecological costs.
- A uniform fiscal regime may improve predictability for industry, but excessive central control can narrow the revenue space of States that bear land acquisition, displacement, pollution, public-health and infrastructure burdens.
UPSC Relevance
Prelims Relevance
- The MMDR Act, 1957 is the principal parliamentary law governing regulation of mines and development of minerals in India.
- Entry 54 of the Union List covers regulation of mines and mineral development to the extent Parliament declares Union control expedient in the public interest.
- Entry 23 of the State List covers regulation of mines and mineral development, subject to the Union List provision in Entry 54.
- Entry 50 of the State List covers taxes on mineral rights, subject to limitations imposed by Parliament by a law relating to mineral development.
- Entry 49 of the State List covers taxes on lands and buildings; a tax’s legal character depends on its true subject, not merely the method used to calculate it.
- Royalty under Section 9 is a contractual or statutory payment for extracting minerals, while a tax is a compulsory exaction for public purposes; the Supreme Court held that the two are not identical.
Mains Relevance
GS Paper 2
- Use the Bill to explain legislative competence, pith and substance, and the interaction among Entries 49 and 50 of List II and Entry 54 of List I.
- Evaluate whether centrally prescribed limits represent legitimate constitutional coordination or an erosion of State fiscal autonomy in a resource-asymmetric federation.
GS Paper 3
- Assess the trade-off between investment certainty and the revenue needs of mineral-bearing States.
- Link mining levies to domestic mineral availability, import dependence, downstream manufacturing, infrastructure costs and environmental externalities.
Essay
- Natural resources test whether federalism can combine national purpose with local justice.
Background and Context
Constitutional distribution of mining powers
Mining sits at the intersection of a State regulatory field, a Union override and expressly qualified State taxing entries.
- Under Entry 23 of List II, States ordinarily regulate mines and mineral development, but that field is subject to Parliament’s declaration under Entry 54 of List I.
- Section 2 of the MMDR Act declares it expedient in the public interest that the Union take control of mine regulation and mineral development to the extent provided by the Act.
- Taxing powers are separately enumerated. Entry 50 gives States power over taxes on mineral rights, expressly subject to limitations imposed by Parliament through a law relating to mineral development.
- Entry 49 gives States power to tax lands and buildings. A land tax does not automatically become a mineral-rights tax merely because mineral value is used as a measure; courts examine the levy’s pith and.
- The Bill seeks to use Parliament’s mineral-development field to build a nationwide ceiling framework. The constitutional question is how far that framework may constrain distinct State taxing fields without emptying them of substance.
What the Supreme Court clarified in 2024
The nine-judge Bench separated royalty from tax and restored analytical importance to the State List entries.
- In Mineral Area Development Authority v. Steel Authority of India, the majority held that royalty is not a tax. Royalty arises from the right to extract minerals and forms part of the consideration owed by.
- The majority held that the MMDR Act, as it then stood, did not contain a limitation that denuded States of their Entry 50 competence merely because Parliament regulated royalties.
- The Court also recognised Entry 49 as a distinct source of State taxing power over land. The tax measure may refer to mineral produce or value if the true subject remains land.
- The later order on temporal operation allowed relevant State demands from 1 April 2005, directed payment in instalments over twelve years beginning 1 April 2026, and barred interest and penalties on demands for the period.
- This remedial issue is explained in the published note on the doctrine of prospective overruling and the mineral-rights verdict. The new Bill attempts a legislative response to pending and future liabilities, which may itself.
How the proposed framework changes the MMDR Act
The Bill uses four linked moves: an expanded declaration, a new restriction, treatment of legacy demands and delegated rules.
- First, mineral-bearing lands containing mineral content, identified through centrally prescribed parameters, would enter the declared field of Union control under Section 2.
- Second, proposed Section 9D would cover a tax, cess or other levy by whatever name, imposed on mineral rights or mineral-bearing land and calculated through mineral quantity, mineral value, royalty or another basis.
- Third, States could impose a covered levy only under the conditions or restrictions prescribed by the Central government. The operative fiscal space will depend heavily on rules made after enactment.
- Fourth, pre-commencement amounts not paid or collected would be treated as invalid, while amounts already deposited or recovered would not be refundable. This creates a sharp line based on collection status.
- The text must not be confused with royalty rates, DMF contributions or NMET contributions already structured under the MMDR Act. Each payment has a different legal basis and beneficiary.
The Union's case for uniformity
The Centre frames the amendment as a response to cumulative costs and uncertainty rather than as a transfer of mineral wealth.
- The PIB backgrounder identifies multiple State taxes, cesses and levies, non-uniform rates, retrospective demands and new charges introduced after mining operations began as sources of regulatory uncertainty.
- A predictable ceiling can lower compliance costs, reduce cascading burdens and help investors price long-gestation mining projects more accurately.
- Lower and more stable extraction costs may strengthen local mineral supply chains, downstream steel and manufacturing, and India’s wider critical-minerals strategy.
- The strongest Union argument rests on Entry 50’s own wording: State mineral-rights taxes are constitutionally subject to limitations imposed by Parliament through a mineral-development law.
- Uniformity alone is not proof of fairness. The Centre must disclose the evidence behind any ceiling, assess mineral-specific economics and account for ecological costs instead of assuming that every State levy is distortionary.
Way Forward
Use structured federal consultation
- Create a standing Union-State mineral fiscal council with representation from mineral-bearing and consuming States, tribal-affairs institutions, finance officials and independent mining economists.
- Publish draft Section 9D rules, fiscal-impact assessments and responses to State objections before notification.
- Review conditions periodically because mineral prices, ore grades, transport costs and environmental liabilities change over time.
Conclusion
- The MMDR Amendment Bill 2026 is a consequential attempt to convert a contested field of State levies into a more predictable national framework.
- The sound policy test is neither maximum State discretion nor maximum central uniformity.
UPSC Practice Questions
Prelims MCQ 1
With reference to the constitutional framework for mineral taxation in India, consider the following statements:
- Entry 50 of the State List concerns taxes on mineral rights and is subject to limitations imposed by Parliament through a law relating to mineral development.
- Entry 54 of the Union List concerns regulation of mines and mineral development to the extent declared by Parliament to be expedient in the public interest.
- The Supreme Court held in Mineral Area Development Authority that royalty is constitutionally identical to a tax.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 1 and 2 reproduce the relevant constitutional division. Statement 3 is incorrect because the Supreme Court’s 2024 majority held that royalty is not a tax; it is consideration connected with the right to extract minerals.
Prelims MCQ 2
Which one of the following correctly distinguishes the District Mineral Foundation from the National Mineral Exploration Trust?
(a) DMF supports mining-affected persons and areas, while NMET supports mineral exploration (b) DMF fixes royalty rates, while NMET adjudicates inter-State tax disputes (c) DMF is a constitutional body, while NMET is created by a State law (d) DMF regulates mine safety, while NMET grants environmental clearances
Answer: (a) DMF supports mining-affected persons and areas, while NMET supports mineral exploration
Explanation:
Section 9B of the MMDR Act provides for DMFs for mining-affected persons and areas. Section 9C provides for NMET to promote regional and detailed mineral exploration. Neither body performs the functions stated in the other options.
UPSC Mains Questions
- The MMDR Amendment Bill 2026 tests the boundary between parliamentary coordination and State fiscal autonomy. Examine with reference to Entries 49 and 50 of the State List and Entry 54 of the Union List. (250 words)
- A uniform mineral-tax framework can improve investment certainty but may under-compensate mineral-bearing regions for local externalities. Discuss a cooperative federal design that can reconcile these objectives. (250 words)
Sources: PIB Backgrounder, Ministry of Mines and The Hindu.
Frequently Asked Questions
What does the MMDR Amendment Bill 2026 propose?
It proposes Union control over specified mineral-bearing lands and a new Section 9D. States could impose taxes, cesses or other levies on mineral rights or mineral-bearing lands only under conditions or restrictions prescribed by the Central government. It also addresses.
Does the Bill completely abolish the States’ power to tax minerals?
The stated design does not transfer a named mineral tax to the Union. It conditions the exercise of covered State levies on centrally prescribed rules. Whether the resulting rules leave States meaningful fiscal space will depend on their content and.
What did the Supreme Court decide about mineral royalty in 2024?
The majority in Mineral Area Development Authority held that royalty is not a tax and that States have competence under Entry 50 to tax mineral rights, subject to parliamentary limitations. It also treated Entry 49 land taxation as a distinct.
Why do mineral-bearing States oppose centrally determined limits?
They argue that extraction imposes concentrated costs: displacement, forest loss, pollution, mine-related infrastructure and public-health burdens. If national limits reduce their own-source revenue without adequate compensation, resource-rich regions may finance national supply chains while remaining fiscally constrained and socially under-served.
How are royalty and a tax different?
Royalty is linked to the right to extract minerals under a lease or statutory regime and is calculated with reference to extraction. A tax is a compulsory public exaction imposed under legislative authority. The distinction matters because constitutional taxing powers.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.