Why in News?
The Reserve Bank of India’s latest treatment of Tata Sons under the Upper-Layer NBFC framework has renewed the debate over whether the privately held group holding company must list its equity shares.
- Tata Sons was identified as an NBFC-UL in the RBI’s first list issued on September 30, 2022, in the category of a core investment company.
- The RBI’s 2021 Scale Based Regulation framework says an NBFC-UL shall be mandatorily listed within three years of identification and must adopt listed-company-like disclosures even before listing.
- Tata Sons has sought cancellation of its RBI registration as a core investment company. The RBI stated in its January 16, 2025 list that continued inclusion was without prejudice to the outcome of that application, which.
- The dispute turns on regulatory status, size, interconnectedness and public-funds linkages; repayment of direct debt does not settle every concern.
- A public listing would bring market disclosure, shareholder, related-party transaction and corporate-governance obligations in addition to the RBI’s prudential oversight.
- Large NBFCs can transmit stress to banks, bond markets and group companies. Systemic importance depends on linkages, not only labels.
- A core investment company mainly holds and finances group companies. Its balance sheet can become a channel through which risks and funding conditions travel across a conglomerate.
- The case separates prudential regulation by the RBI from market disclosure regulation by SEBI.
UPSC Relevance
Prelims Relevance
- A Non-Banking Financial Company is regulated principally by the RBI under Chapter IIIB of the Reserve Bank of India Act, 1934; it is not a bank and cannot issue cheques drawn on itself.
- The RBI’s scale-based framework has four layers: Base, Middle, Upper and Top. Regulation becomes progressively more intensive as an entity moves upward.
- The Top Layer is intended to remain empty, but the RBI may place an Upper-Layer NBFC there if its potential systemic risk rises substantially.
- Core investment companies, housing finance companies, infrastructure finance companies and deposit-taking NBFCs are placed in the Middle or Upper Layer, depending on the applicable rules.
- Under the original 2021 framework, the Upper Layer included NBFCs specifically identified through parameters and scoring, while the ten largest eligible NBFCs by asset size were to remain in it.
- An NBFC-UL is subject to Middle-Layer requirements plus stronger rules concerning capital, leverage, large exposures, governance and disclosure.
Mains Relevance
GS Paper 3
- Explain why size, interconnectedness, complexity and funding channels can make an NBFC systemically important even without a bank-like deposit franchise.
- Assess scale-based regulation as an instrument for reducing regulatory arbitrage between large NBFCs and banks while preserving a differentiated financial system.
GS Paper 2
- Discuss the governance case for public disclosure, independent oversight and scrutiny of related-party transactions in economically important private holding companies.
- Examine the need for transparent, rule-based regulatory decisions when deregistration, exemption or transition requests affect large corporate groups.
Essay
- Good regulation should follow the risk generated by an institution, not only the legal form it chooses.
Background and Context
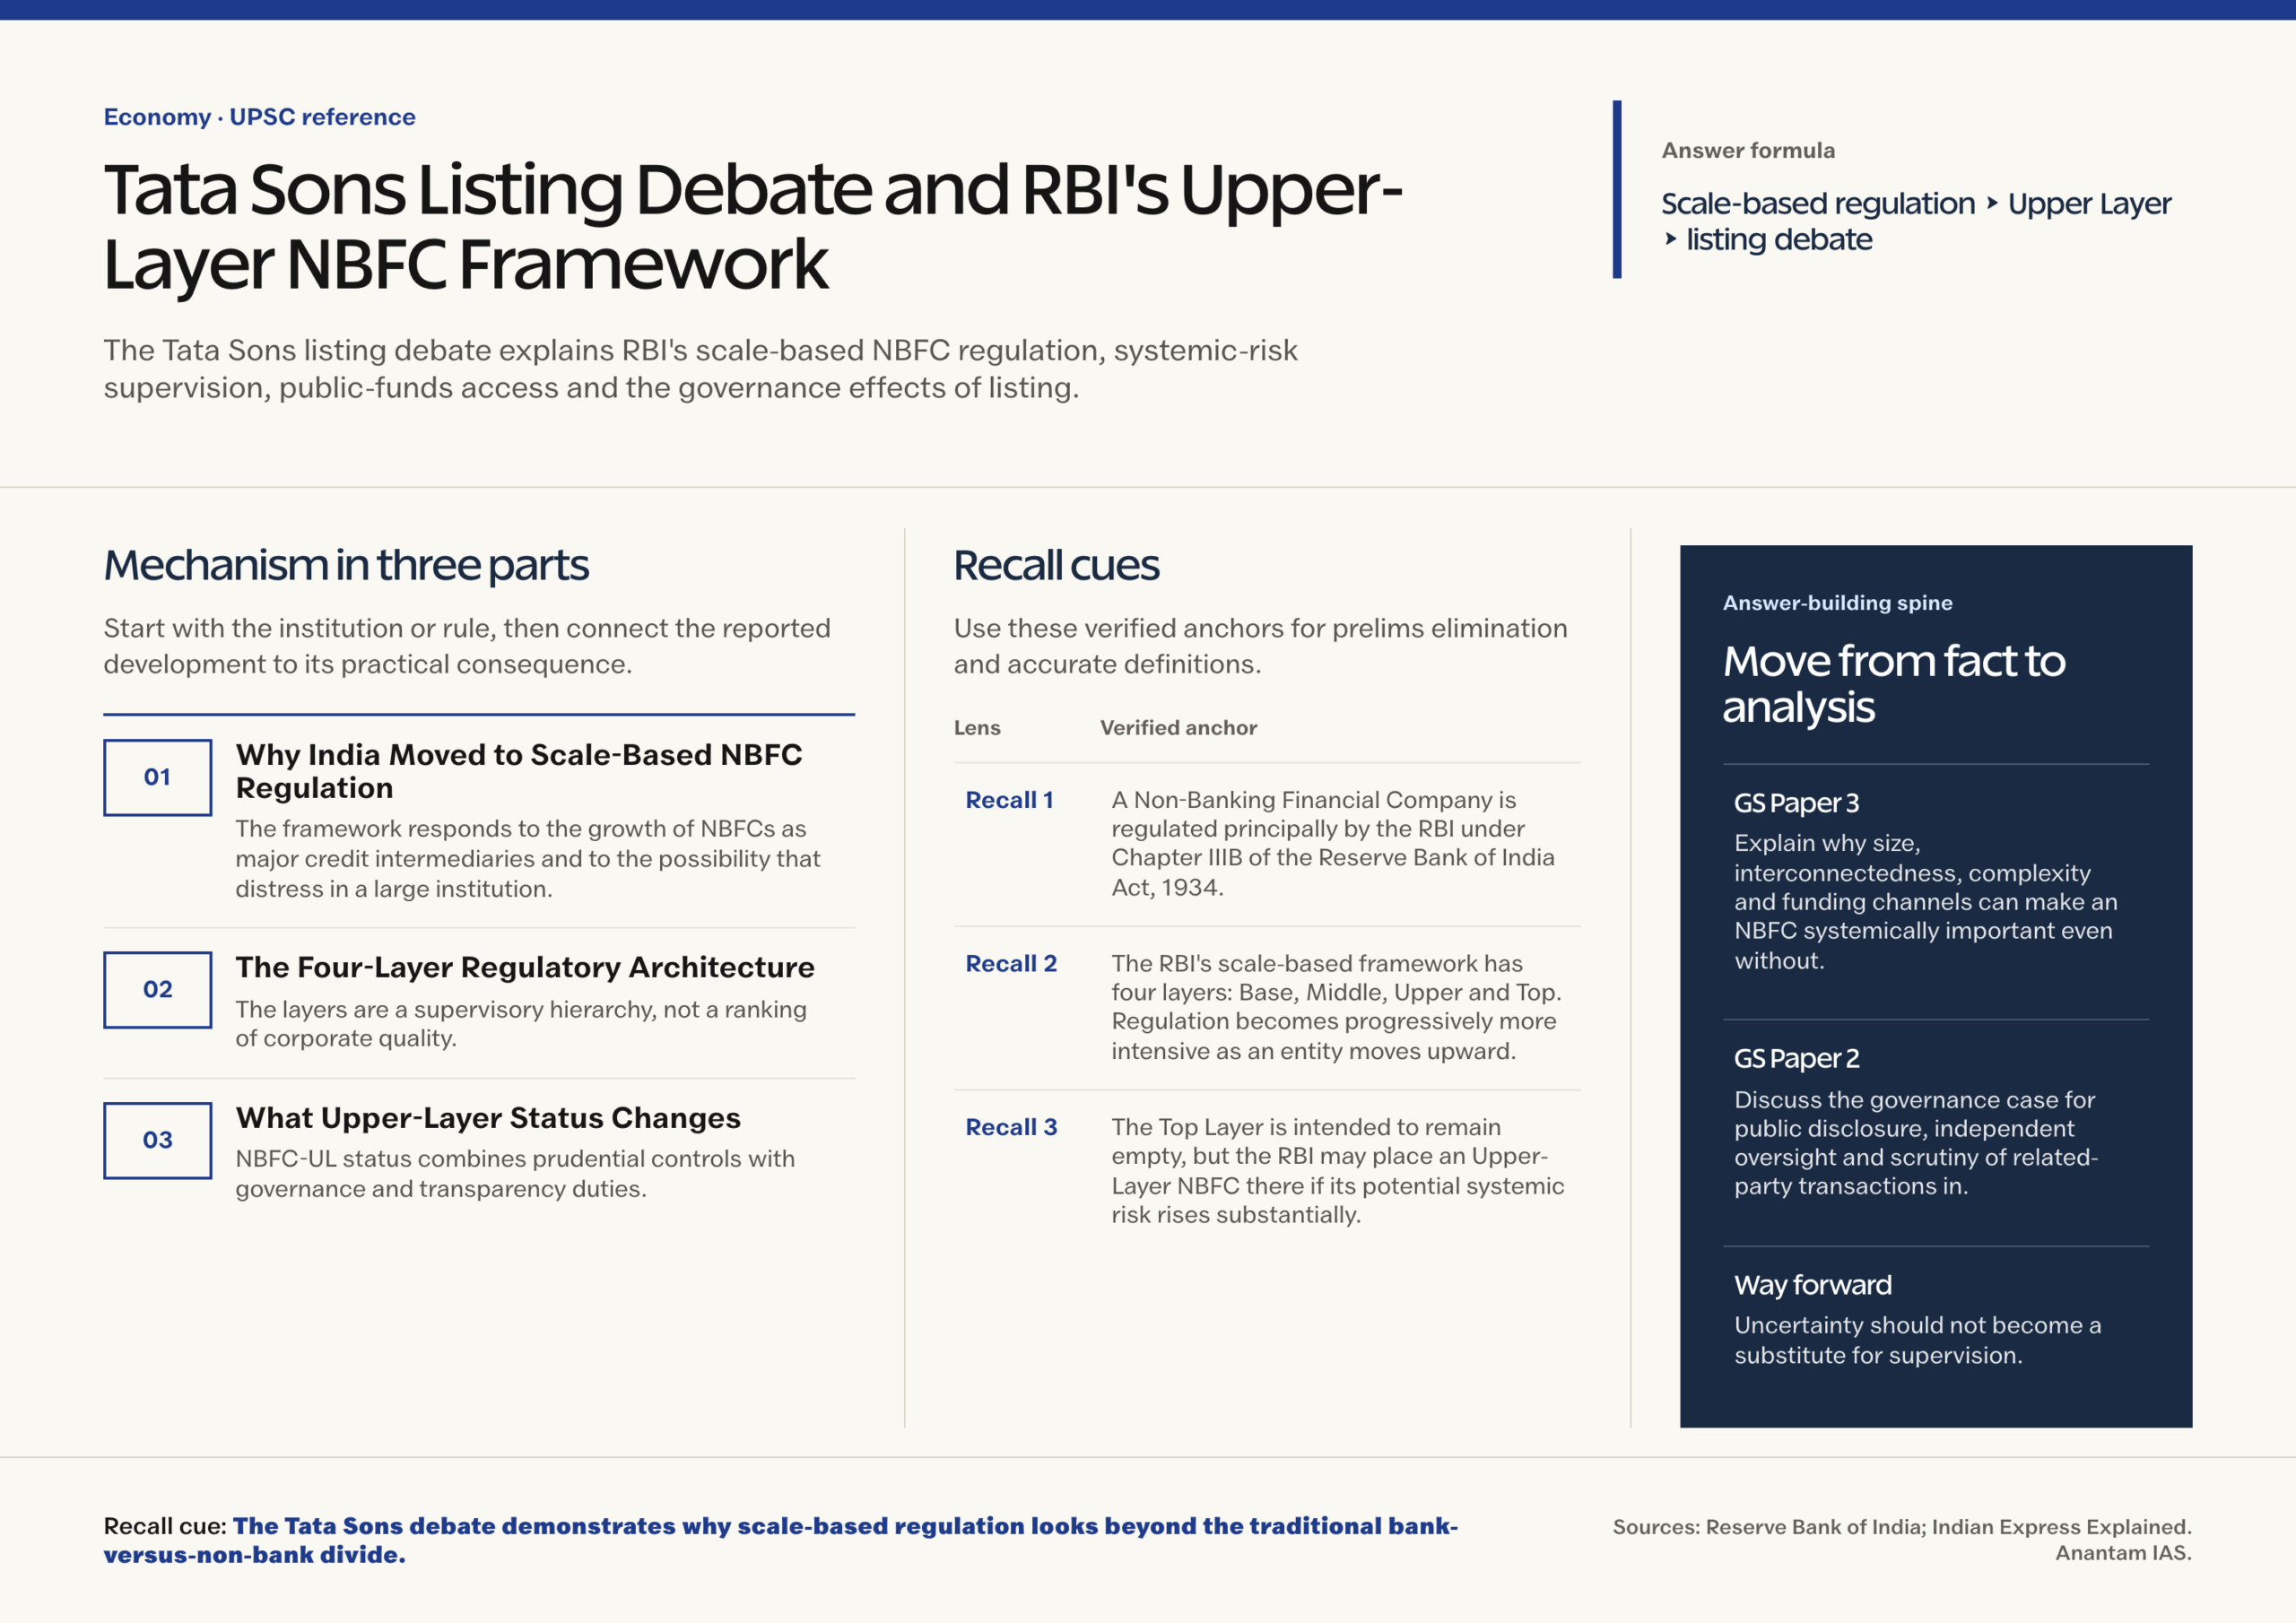
Why India Moved to Scale-Based NBFC Regulation
The framework responds to the growth of NBFCs as major credit intermediaries and to the possibility that distress in a large institution can spread through the financial system.
- NBFCs supplement banks through housing, vehicle, infrastructure, consumer and microfinance. Their specialised models can expand credit access.
- Expansion also increases interconnectedness. Bank borrowing, debt issuance and group investments allow a funding shock to travel across markets.
- A uniform rulebook would overburden small NBFCs or under-regulate large ones. The RBI adopted proportionality, with stronger requirements in higher layers.
- The framework, broadly effective from October 1, 2022, links regulation to size, activity and perceived riskiness and limits regulatory arbitrage.
- The design reflects a key financial-stability lesson: an institution need not resemble a commercial bank to create bank-like spillovers. Wholesale borrowing can connect an NBFC to banks and bond investors, while concentrated group investments can transmit.
The Four-Layer Regulatory Architecture
The layers are a supervisory hierarchy, not a ranking of corporate quality.
- The Base Layer contains smaller non-deposit-taking NBFCs and specified categories such as peer-to-peer platforms and account aggregators.
- The Middle Layer includes all deposit-taking NBFCs, larger non-deposit-taking NBFCs and specified categories such as CICs and housing finance companies, unless placed higher.
- The Upper Layer contains NBFCs identified for enhanced regulation, while the Top Layer is expected to remain empty unless systemic risk rises substantially.
- Movement upward adds obligations without erasing lower-layer safeguards, so intensity follows spillover risk.
- The RBI’s 2021 framework required the ten largest eligible NBFCs by asset size to remain in the Upper Layer irrespective of other factors, alongside entities selected through the prescribed assessment. The approach recognised that absolute scale.
What Upper-Layer Status Changes
NBFC-UL status combines prudential controls with governance and transparency duties.
- The RBI requires an Internal Capital Adequacy Assessment Process covering credit, market, operational and residual risks.
- Upper-Layer NBFCs face differential provisioning, leverage discipline and a Large Exposure Framework for concentrated counterparty and group exposures.
- Boards need appropriate competence; premature exit of an independent director must be reported to supervisors.
- Listed-company-like disclosure before listing narrows information gaps, while mandatory listing adds market discipline. Neither replaces RBI supervision.
- Transition rules separate immediate planning from full implementation. Within three months of being advised about Upper-Layer status, the NBFC must adopt a Board-approved plan and submit its roadmap to the RBI; the enhanced requirements must be.
Why Tata Sons Is a Special Case
Tata Sons is both a private holding company and a core investment company at the centre of a large corporate group.
- As a CIC, its significance comes mainly from holdings and financial relationships within the Tata group, not conventional retail lending.
- The RBI included Tata Sons in the inaugural September 2022 Upper-Layer list and again identified it as a CIC in the official 2024-25 list published on January 16, 2025.
- Its deregistration application raises whether NBFC-specific obligations continue if the RBI cancels its certificate. An application is not approval.
- Lower direct leverage does not settle concerns about indirect public funds, group linkages, asset concentration or stress at a central holding entity.
- The RBI’s phrase without prejudice preserves a separate decision on deregistration while classification continues.
Way Forward
Issue a Reasoned, Time-Bound Regulatory Decision
- The RBI should conclude the deregistration application through a speaking order or an appropriately detailed public explanation of the governing principles, while protecting genuinely confidential supervisory information.
- The decision should state how the listing timeline, five-year retention rule and transition obligations interact with cancellation; comparable NBFCs need the same criteria.
- Regulators should map guarantees, cross-holdings, funding flows, common counterparties and concentrated exposures across the group to identify contagion channels.
- Stress tests should examine valuation shocks, funding freezes and group-company distress; regulator information-sharing needs clear safeguards.
Conclusion
- The Tata Sons debate demonstrates why scale-based regulation looks beyond the traditional bank-versus-non-bank divide.
- The durable policy answer is a transparent, consistent and risk-sensitive decision.
UPSC Practice Questions
Prelims MCQ 1
With reference to the RBI’s Scale Based Regulation framework for NBFCs, consider the following statements:
- The regulatory structure comprises Base, Middle, Upper and Top Layers.
- The Top Layer is intended to contain the ten largest eligible NBFCs at all times.
- An NBFC identified in the Upper Layer is ordinarily subject to enhanced regulation for at least five years.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 1 and 3 are correct. The Top Layer is intended to remain empty and may be populated only when the RBI sees a substantial increase in potential systemic risk. The largest eligible NBFCs are associated with Upper-Layer identification, not permanent placement in the Top Layer.
Prelims MCQ 2
Which one of the following best describes a Core Investment Company in the context of RBI regulation?
(a) An NBFC whose principal function is operating a retail payments system (b) A company primarily holding shares, securities and financial exposures in group companies, subject to prescribed conditions (c) A scheduled bank created solely to finance infrastructure projects (d) A securities exchange that lists corporate bonds
Answer: (b) A company primarily holding shares, securities and financial exposures in group companies, subject to prescribed conditions
Explanation:
A CIC is a specialised NBFC centred on investments and financial exposures in group companies. It is not a bank, payment-system operator or stock exchange.
UPSC Mains Questions
- How does the RBI’s scale-based regulatory framework address systemic risk in the non-banking financial sector? Explain with reference to the Tata Sons listing debate. (250 words)
- Public listing can strengthen transparency but cannot replace prudential supervision. Discuss in the context of large NBFCs and core investment companies. (250 words)
Sources: Reserve Bank of India and Indian Express Explained.
Frequently Asked Questions
Why is Tata Sons discussed as an NBFC?
Tata Sons is the principal holding company of the Tata group and has been registered with the RBI as a core investment company, a specialised category of NBFC. Its financial holdings and relationships with group companies bring it within.
What is an Upper-Layer NBFC?
An NBFC-UL is an NBFC specifically identified by the RBI for enhanced regulation because of its scale and risk significance. It follows Middle-Layer rules plus stronger capital, exposure, governance and disclosure requirements. Under the framework, Upper-Layer NBFCs are also required.
Does Tata Sons’ deregistration application automatically cancel the listing requirement?
No. Filing an application does not amount to approval. The RBI’s January 2025 release said Tata Sons’ inclusion in the Upper Layer was without prejudice to its deregistration application, which remained under examination. The legal consequences depend on the RBI’s.
What are indirect public funds?
In this regulatory context, indirect public funds are funds received through associates or group entities that themselves have access to public funds. The concept helps the RBI examine the substance of a funding chain, so an entity cannot be assessed.
Why can a debt-free holding company still attract systemic-risk scrutiny?
Direct debt is only one source of risk. A central holding company may have concentrated investments, guarantees, cross-holdings, common creditors and funding links with major group entities. Stress at that node can affect listed companies and lenders, so the RBI.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.