Why in News?
India’s Research, Development and Innovation Fund has moved from policy design to actual allocation.
- The Union Cabinet approved the scheme on July 1, 2025, and it was formally launched on November 3, 2025 for a six-year period.
- The government sanctioned ₹1,000 crore each to the Technology Development Board and the Biotechnology Industry Research Assistance Council as initial Second-Level Fund Managers.
- The official July update recorded ₹500 crore disbursed to TDB in March 2026. TDB had approved 22 projects with a combined project cost of ₹4,744 crore and proposed RDIF support of ₹2,192 crore.
- BIRAC had shortlisted eight biotechnology projects involving ₹390.35 crore of support, showing that deployment has begun across more than one institutional channel.
- The scheme’s published guidelines recognise that domain experts on an investment committee may themselves be investors in ideas or companies. That makes conflict management part of the fund’s core design, not a peripheral ethics issue.
- Deep-tech ventures usually face long development cycles, uncertain technical outcomes, expensive testing and a difficult lab-to-market gap. Conventional lenders often cannot value this risk, while short-horizon equity may demand returns before the technology matures.
- Public capital can absorb part of this risk and crowd in private investment, but weak selection can socialise losses, favour connected applicants or lock money into technologies with little additional public value.
- The governance problem is a balance: an excessively bureaucratic process may reject frontier ideas, while unchecked discretion may weaken fairness, additionality and accountability.
UPSC Relevance
Prelims Relevance
- The Department of Science and Technology is the nodal department for implementing the RDI Scheme.
- A Special Purpose Fund under ANRF operates as the first-level custodian; it does not directly choose every beneficiary enterprise.
- Second-Level Fund Managers may include AIFs, DFIs, NBFCs and Focused Research Organisations, subject to the applicable selection route and guidelines.
- TDB and BIRAC were initially approved as public Focused Research Organisation fund managers; additional commercial managers are selected through a competitive process.
- Permitted forms include long-term loans at low or nil interest, equity in select startup cases, and contributions to deep-tech or RDI-focused funds of funds.
- The scheme does not provide grants or short-term loans under its published design.
Mains Relevance
GS Paper 3
- Examine how patient public finance can address market failure in strategic and sunrise technologies without replacing private risk assessment.
- Assess the fund’s role in bridging the valley between a validated prototype and commercial scale, especially for technologies at TRL 4 and above.
GS Paper 2
- Analyse delegated decision-making, conflict-of-interest safeguards and auditability when public money is deployed through private or arm’s-length financial intermediaries.
- Discuss how disclosure, reasoned decisions, recusal and independent oversight can reconcile expertise with impartiality.
Essay
- Innovation policy succeeds when the state is willing to take intelligent risks and equally willing to make the process of taking those risks open to scrutiny.
Background and Context
Why deep-tech needs patient capital
Deep-tech finance differs from ordinary startup finance because technical risk, capital intensity and time to market are unusually high.
- A laboratory result must pass engineering validation, safety or regulatory review, pilot production and customer adoption before it becomes a scalable product. Each stage can reveal a new failure mode.
- Banks prefer predictable cash flows and collateral. Many deep-tech firms have neither because their main asset is unproven intellectual property and their early revenue is limited.
- Venture investors can finance uncertainty, but fund life, exit expectations and portfolio strategy may not match a project that needs many years of testing before commercial returns.
- The state has a case for intervention when innovation produces wider benefits such as strategic resilience, skilled employment, knowledge spillovers or lower dependence on imported critical technology.
- Public support should remain additional: it should unlock a socially valuable project that the market underfunds, not merely subsidise activity that a firm would have financed on normal commercial terms.
How the two-tier RDI Fund works
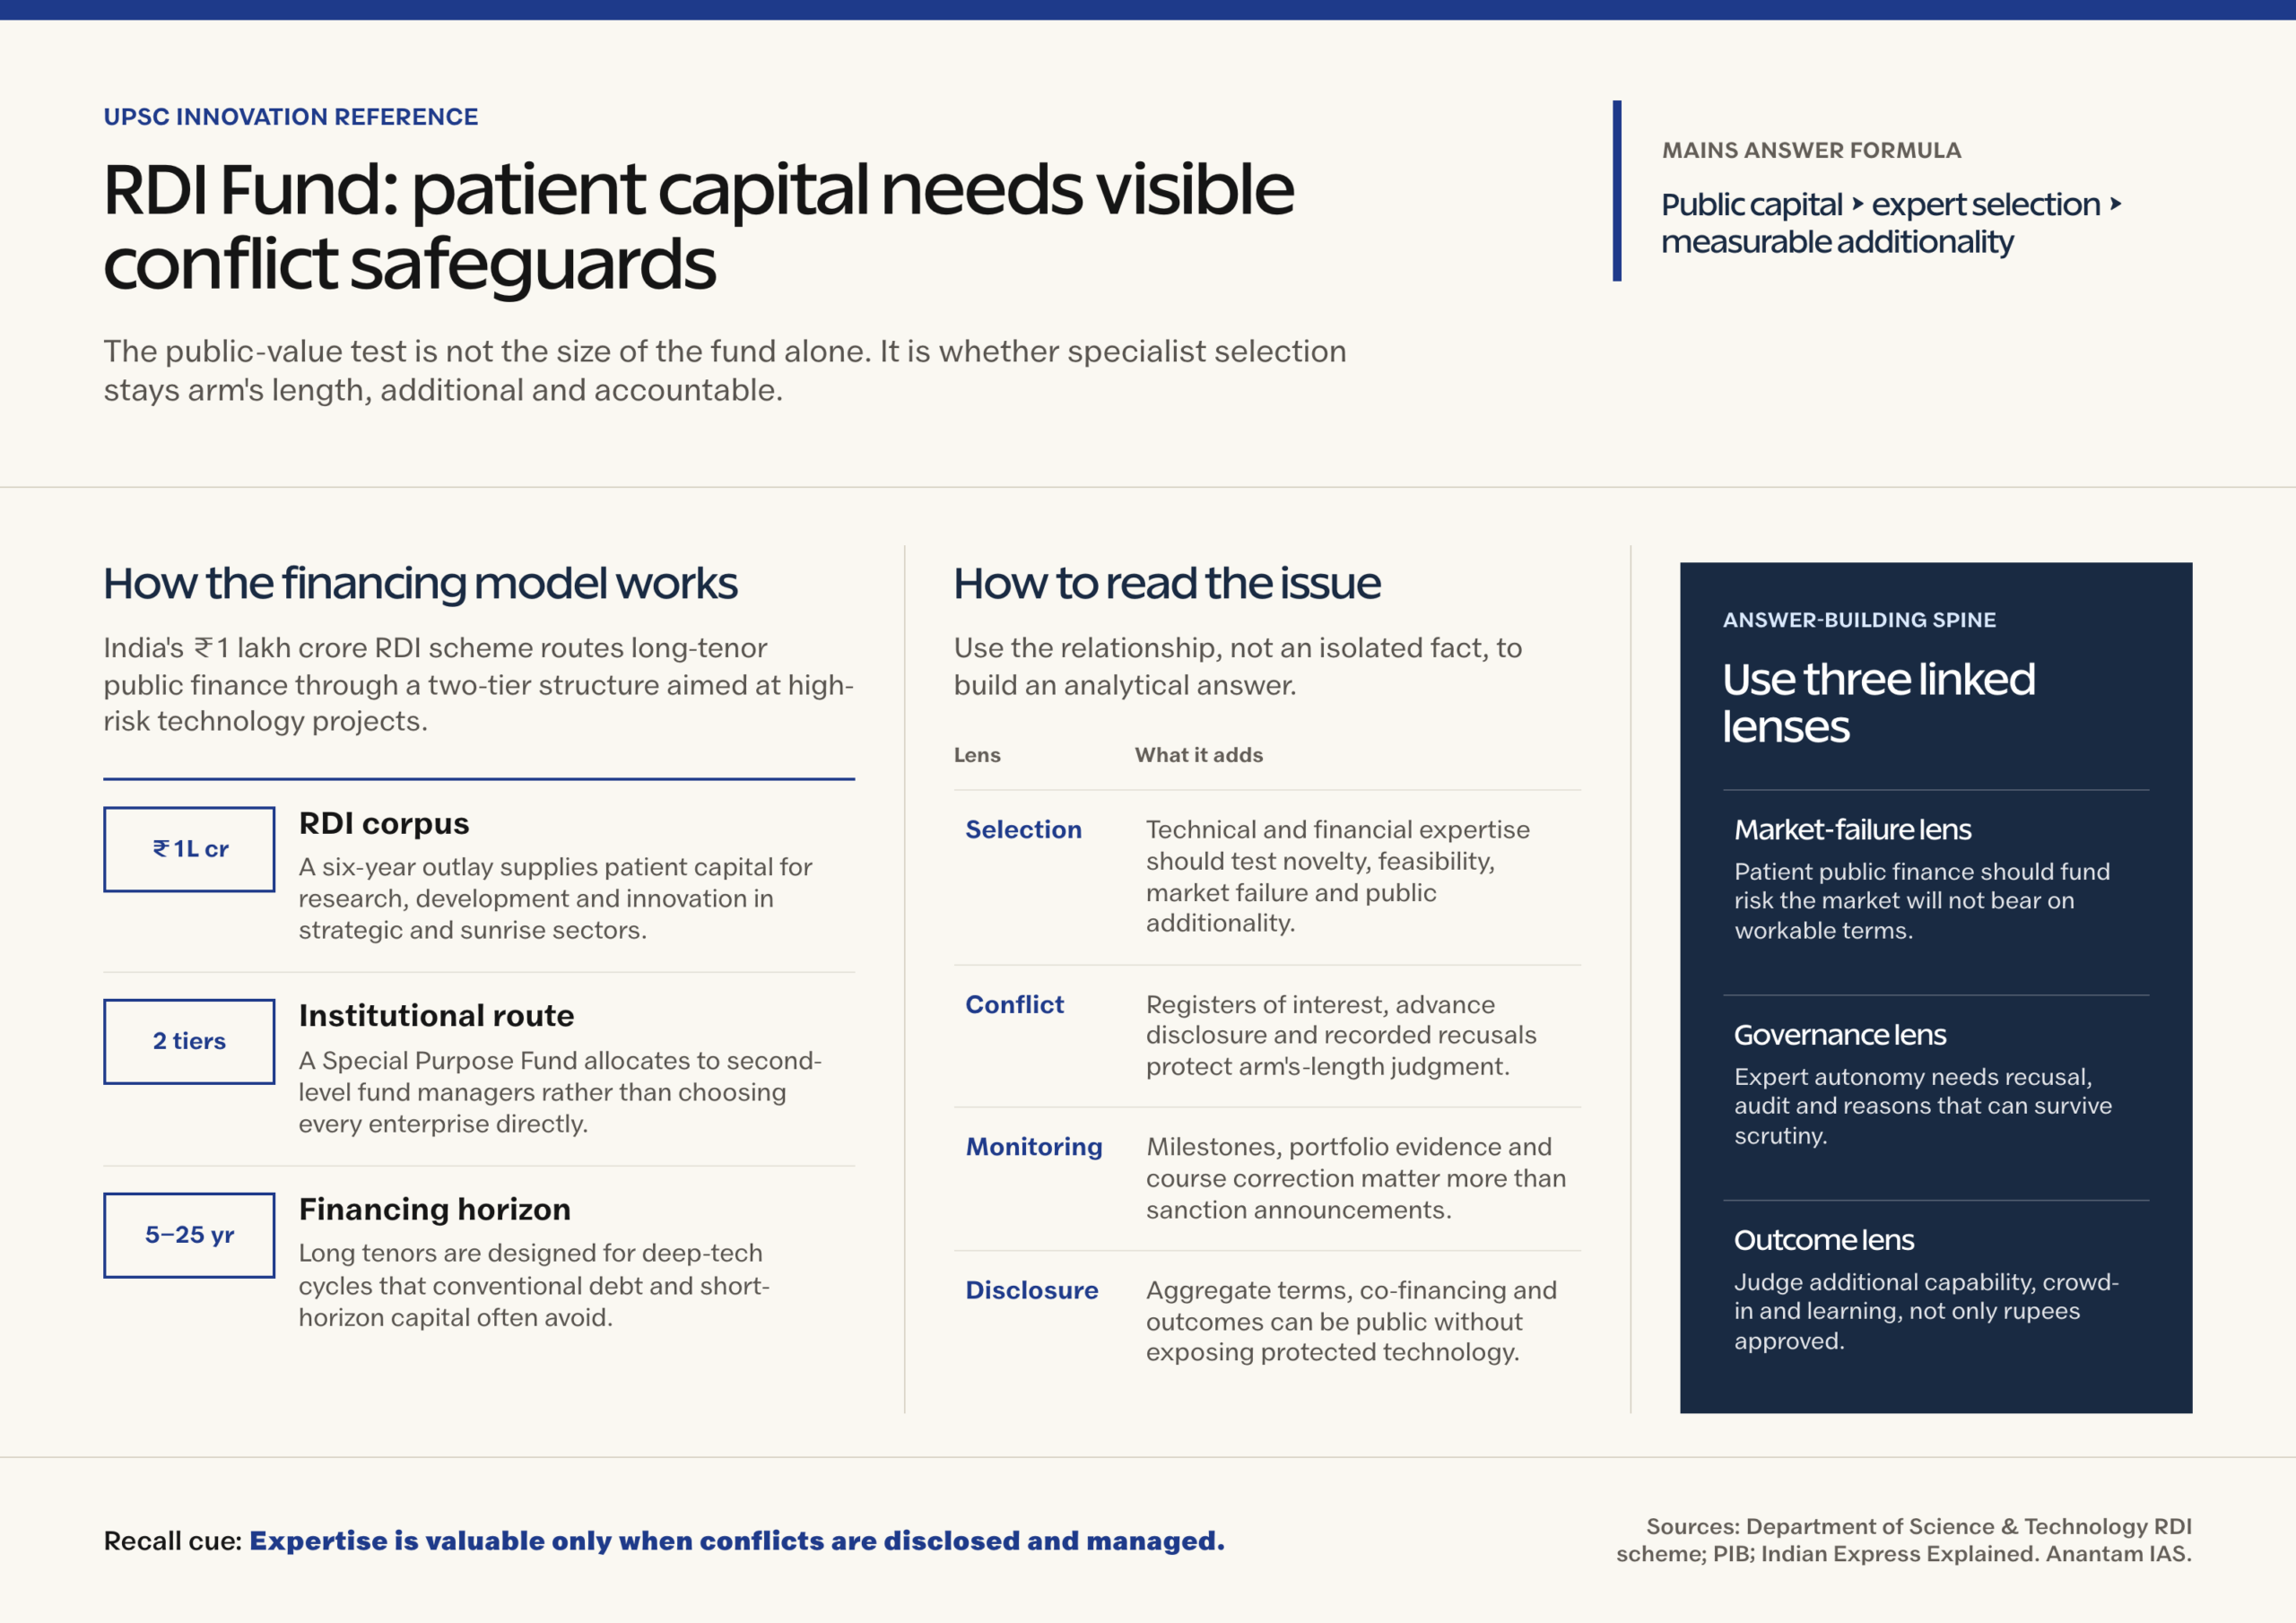
The architecture separates custody and policy direction from project-level investment judgment.
- At the first level, a Special Purpose Fund within ANRF holds and channels the corpus. DST acts as the nodal department and has framed implementation guidelines and special financial rules.
- At the second level, approved fund managers evaluate enterprises and projects. Their categories can include Alternative Investment Funds, Development Finance Institutions, Non-Banking Financial Companies and specialised public research-finance organisations.
- This separation is intended to keep individual project selection closer to people with technical, financial and market knowledge while retaining a public policy framework at the top.
- Commercial fund managers are evaluated through Quality and Cost Based Selection. The Executive Council recommends names to the EGoS, which makes the final approval decision.
- Project support may use patient debt, select equity or fund-of-funds contributions. Because the scheme excludes grants, capital recovery and recycling remain part of its financing logic.
What the first allocations show
Early deployment provides a baseline for judging whether a large announced corpus becomes a diverse, disciplined innovation portfolio.
- The official July 2026 update said TDB had approved 22 projects with ₹2,192 crore in RDIF support against a total project cost of ₹4,744 crore.
- The same update said BIRAC had shortlisted eight projects involving ₹390.35 crore, placing biotechnology alongside TDB’s wider cross-sector mandate.
- These figures describe approvals or shortlisting, not completed outcomes. They should not be treated as proof that technologies have reached market, generated returns or achieved strategic self-reliance.
- A credible evaluation should distinguish amounts sanctioned, amounts disbursed, milestones completed, private capital mobilised, intellectual property created, regulatory clearances obtained and products commercially adopted.
- Portfolio concentration also matters. A few sectors may legitimately dominate when proposal quality is stronger, but the public record should explain why selection reflects merit rather than institutional familiarity or investment fashion.
Where conflicts of interest can arise
Deep-tech expertise is concentrated, so the most knowledgeable evaluators may have prior, current or prospective relationships with applicants.
- An investment-committee member may be a limited partner in a fund, a general partner, an adviser, a board member, a shareholder, a research collaborator or an investor in a competing company.
- A fund manager may prefer an enterprise already in its network, allocate a valuable opportunity between public and private portfolios, or set terms that increase its own fee income without maximising public value.
- Technical experts can also carry non-financial conflicts, such as institutional rivalry, intellectual-property disputes, close academic collaboration or commitment to a particular technological pathway.
- The published guidelines acknowledge that fund-manager team members may sit on the investment committee and that domain experts may also be investors in ideas or companies. Recognition is useful, but an operational safeguard needs defined disclosure.
- The risk is not cured by excluding all industry experts. That would weaken technical judgment. The sound response is to identify interests early, grade their materiality and remove conflicted members from access, discussion or voting where.
Way Forward
Create a uniform conflict protocol
- Require annual and meeting-specific declarations covering financial interests, advisory roles, board positions, close institutional relationships and interests in competing entities.
- Classify conflicts as manageable, recusal-required or disqualifying, with a written rationale and a cooling-off rule for recent relationships.
- Ensure that a conflicted member neither receives sensitive applicant material beyond what is necessary nor participates in discussion, scoring, voting or post-investment monitoring.
Conclusion
- The RDI Fund addresses a real market failure: India cannot build strategic technologies if promising firms lack capital between proof of concept and commercial scale.
- That strength also creates its main governance risk.
UPSC Practice Questions
Prelims MCQ 1
With reference to India’s Research, Development and Innovation Scheme, consider the following statements:
- The Special Purpose Fund under ANRF serves as the first-level custodian of funds.
- The scheme supports transformative RDI only through grants and short-term loans.
- Second-Level Fund Managers may include AIFs, DFIs, NBFCs and Focused Research Organisations.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 1 and 3 are correct. The Special Purpose Fund under ANRF is the first-level custodian, while eligible intermediaries act as Second-Level Fund Managers. Statement 2 is incorrect because the scheme excludes grants and short-term loans; it uses patient debt, select equity and fund-of-funds contributions.
Prelims MCQ 2
Which body gives final approval to additional Second-Level Fund Managers under the published RDI Scheme selection structure?
(a) Governing Board of ANRF (b) Technology Development Board (c) Empowered Group of Secretaries (d) Securities and Exchange Board of India
Answer: (c) Empowered Group of Secretaries
Explanation:
Applications are assessed under the prescribed selection framework. The ANRF Executive Council recommends suitable Second-Level Fund Managers, and the Empowered Group of Secretaries gives final approval.
UPSC Mains Questions
- India’s RDI Fund must combine the risk appetite of venture finance with the accountability expected of public expenditure. Discuss the institutional design needed to achieve this balance. (250 words)
- Why are conflict-of-interest safeguards central to a fund-of-funds model for deep technology? Suggest mechanisms that preserve expert judgment without allowing regulatory or network capture. (250 words)
Sources: PIB, Ministry of Science & Technology and The Indian Express Explained.
Frequently Asked Questions
What is the RDI Fund?
The Research, Development and Innovation Fund is a ₹1 lakh crore, six-year public financing initiative designed to catalyse private investment in high-risk, high-impact R&D. It targets strategic and sunrise sectors and routes support through approved intermediaries rather than relying on.
Why does the RDI Fund use a two-tier structure?
A Special Purpose Fund under ANRF holds and channels the corpus at the first level. Second-Level Fund Managers evaluate and finance projects at the second level. This separates policy custody from specialist project selection, while allowing the public framework to.
Which institutions are Second-Level Fund Managers?
The categories can include Alternative Investment Funds, Development Finance Institutions, Non-Banking Financial Companies and Focused Research Organisations. TDB and BIRAC were the first approved public fund managers. Additional commercial managers are considered through the notified competitive selection process.
Why can conflicts of interest arise in deep-tech selection?
India’s deep-tech networks are specialised and relatively concentrated. A technically qualified reviewer may also be an investor, adviser, board member, research collaborator or competitor of an applicant. The issue is managed through prior disclosure, materiality assessment, recusal, independent review and.
Does the RDI Fund provide grants to startups?
No. The published scheme design excludes grants and short-term loans. Its financing modes include long-term loans at low or nil interest, equity in select startup cases, and contributions to deep-tech or RDI-focused funds of funds, routed through approved managers.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.