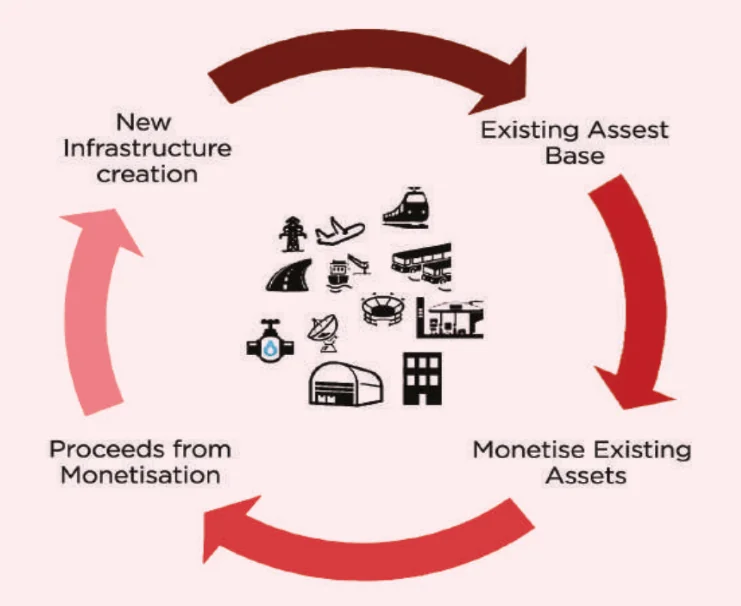
The National Monetisation Pipeline (NMP), launched in August 2021 with an original target of Rs 6 lakh crore over FY22-25, is India's flagship programme for recycling capital from existing public infrastructure assets to finance the creation of new ones. It sits alongside the Union Budget's three-pronged infrastructure financing strategy — enhanced Union Budget capex, the National Bank for Financing Infrastructure and Development (NaBFID), and asset monetisation. For UPSC GS III, NMP is a high-probability theme because it touches fiscal policy, infrastructure, PPP design, and financial markets.
What asset monetisation means
Asset monetisation is the transfer of operating rights over core infrastructure assets to the private sector for a fixed period, against an upfront or phased payment, with ownership staying with the government. It is distinct from privatisation — the asset reverts to the government at the end of the concession.
Core assets covered: national highways, power transmission lines, railway stations, airports, ports, gas pipelines, power generation stations, telecom towers, hotels and sports stadiums.
Not covered: non-core assets (surplus land and buildings), which are monetised separately by the National Land Monetisation Corporation (NLMC).
Global parallels. Australia's Asset Recycling Initiative raised over $17 billion and funded new infrastructure. Indonesia's Limited Concession Scheme (LCS) is another comparable model.
Why NMP exists
The NIP Task Force estimated that traditional sources — Union and state budgets, multilateral debt, domestic borrowing — can finance only about 85% of the NIP's capital needs. The remaining 15% must come from innovative mechanisms, and NMP is the core tool to close this gap. By unlocking the embedded value of brownfield assets, the government can redirect capital into greenfield capex without expanding borrowing.
Monetisation models
Direct contractual models
- Operate-Maintain-Transfer (OMT), deployed as Toll-Operate-Transfer (ToT) in national highways
- Operate-Maintain-Develop (OMD), deployed as the Operation Management Development Agreement (OMDA) in airports
- Long-term lease agreements for telecom towers, bus terminals, stadiums
Structured financing models
- Real Estate Investment Trusts (REITs) for real estate assets
- Infrastructure Investment Trusts (InvITs) for operating infrastructure assets
PowerGrid, NHAI and IRB have all floated InvITs, raising several tens of thousands of crores from domestic and foreign institutional investors.
Benefits
- Unlocks embedded value in decades-old public infrastructure, converting idle balance sheet capacity into fresh investable capital.
- Finances new infrastructure without adding to government debt — addresses the post-Covid tension between capex needs and fiscal consolidation.
- Better O&M. Private operators typically deliver higher service quality and lower life-cycle costs because their revenues depend on uptime.
- Attracts long-term capital from pension funds, sovereign wealth funds and insurance companies, deepening capital markets.
- Targeted cost recovery. Only users pay through tolls or charges, rather than the general taxpayer funding the asset.
- De-risks private sector. Private investors take on operational risk only; the government carries the original construction risk.
Challenges and concerns
- Execution capacity of government. NMP assumes the government will continue to build assets efficiently. Persistent delays in land acquisition, clearances and dispute resolution undermine asset quality before they reach the pipeline.
- User charge impact. Consumers may face higher tariffs and tolls under private operators, raising political sensitivity.
- Missing regulators. Roads and railways lack independent sectoral regulators. Without clear rules, private investors fear arbitrary policy shifts and adverse renegotiation. An independent regulator can set rules, ensure market-determined charges and resolve disputes.
- Value realisation risk. In a risk-averse market, the government may not extract fair value if bidding is thin. This was evident in several early ToT tranches on highways.
- Thin financing depth. REIT and InvIT awareness among retail investors remains limited. Banks are reluctant to lend against concessional assets. Corporate bond markets are still developing.
- Concentration risk. A small set of large conglomerates tends to bid for flagship assets, raising concerns about crony capitalism and reduced competition.
- Contract design. PPP contracts need flexibility for unforeseen events (climate disasters, pandemics), clear quality benchmarks for handed-over assets, guardrails against arbitrary government cancellation, and robust dispute resolution.
Strategies (NITI Aayog recommendations)
- Streamline investment guidelines. SEBI caps on insurance and pension fund participation in REITs/InvITs (e.g., 3% for insurance funds) should be liberalised to channel long-term institutional money.
- Tax incentives for retail. Income tax benefits on investments in REITs and InvITs can broaden participation.
- Bring REITs/InvITs under IBC. Currently, in case of default, lenders lack recourse under the Insolvency and Bankruptcy Code — adding this would improve credit discipline and lending appetite.
- Standardise concession agreements for brownfield asset classes to speed up bidding and reduce idiosyncratic risks.
- Empower ministry-level working groups to identify, value and transact assets with clear accountability.
- User charge governance. Charges must be investment-linked and reasonable, balancing recovery with affordability.
Latest developments (2024-26)
- Cumulative monetisation realisations crossed Rs 3.5 lakh crore by FY25, ahead of the phased schedule.
- Budget 2025-26 outlined a second asset monetisation plan worth Rs 10 lakh crore for FY26-30.
- Successful InvIT issuances from NHAI and PowerGrid have shown that institutional investor appetite exists when contracts are clean and cash flows are visible.
- The National Highways Authority of India has completed multiple ToT bundles, including toll plazas with traffic data of 20+ years.
UPSC Relevance
NMP is a high-yield topic for GS III. Candidates must be able to explain the difference between NMP (core assets, operating rights), NLMC (non-core assets, land/buildings) and privatisation (ownership transfer). Answers should cite the original Rs 6 lakh crore target, the new Rs 10 lakh crore plan for FY26-30, InvIT and REIT structures, and the role of an independent regulator. Prelims may test which sectors are covered under NMP, the difference between ToT and OMDA, and the legal treatment of InvITs. Essay and Mains questions on infrastructure financing almost always expect NMP to be integrated into the answer.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.