Warehousing is the silent backbone of supply chains. While it accounts for only 15-35 percent of total logistics costs, it determines inventory efficiency, lead times, product availability, and food security. India's warehousing sector has long been fragmented, sub-scale, and largely unorganised — the 2018 KPMG-CII benchmark estimated that around 90 percent of warehousing space was controlled by small, unorganised players. The implementation of GST (2017) removed the long-standing state-tax-driven distortion of multiple small warehouses, opening the door for large, organised, multi-modal Grade A warehouses. The National Logistics Policy 2022, PM Gati Shakti, and Multi-Modal Logistics Parks (MMLPs) have accelerated the transformation. This article tracks status, challenges, reforms, and 2024-26 updates essential for UPSC GS-III on infrastructure, agriculture, and external sector.
Why Warehousing Matters
Warehousing intersects almost every UPSC theme:
- Food security — buffer stocks of FCI, state procurement, PDS depots.
- Agriculture — cold storage for perishables, post-harvest losses, Operation Greens.
- Manufacturing and industrial growth — Make in India needs efficient inventory.
- External trade — bonded warehouses, port-side container depots.
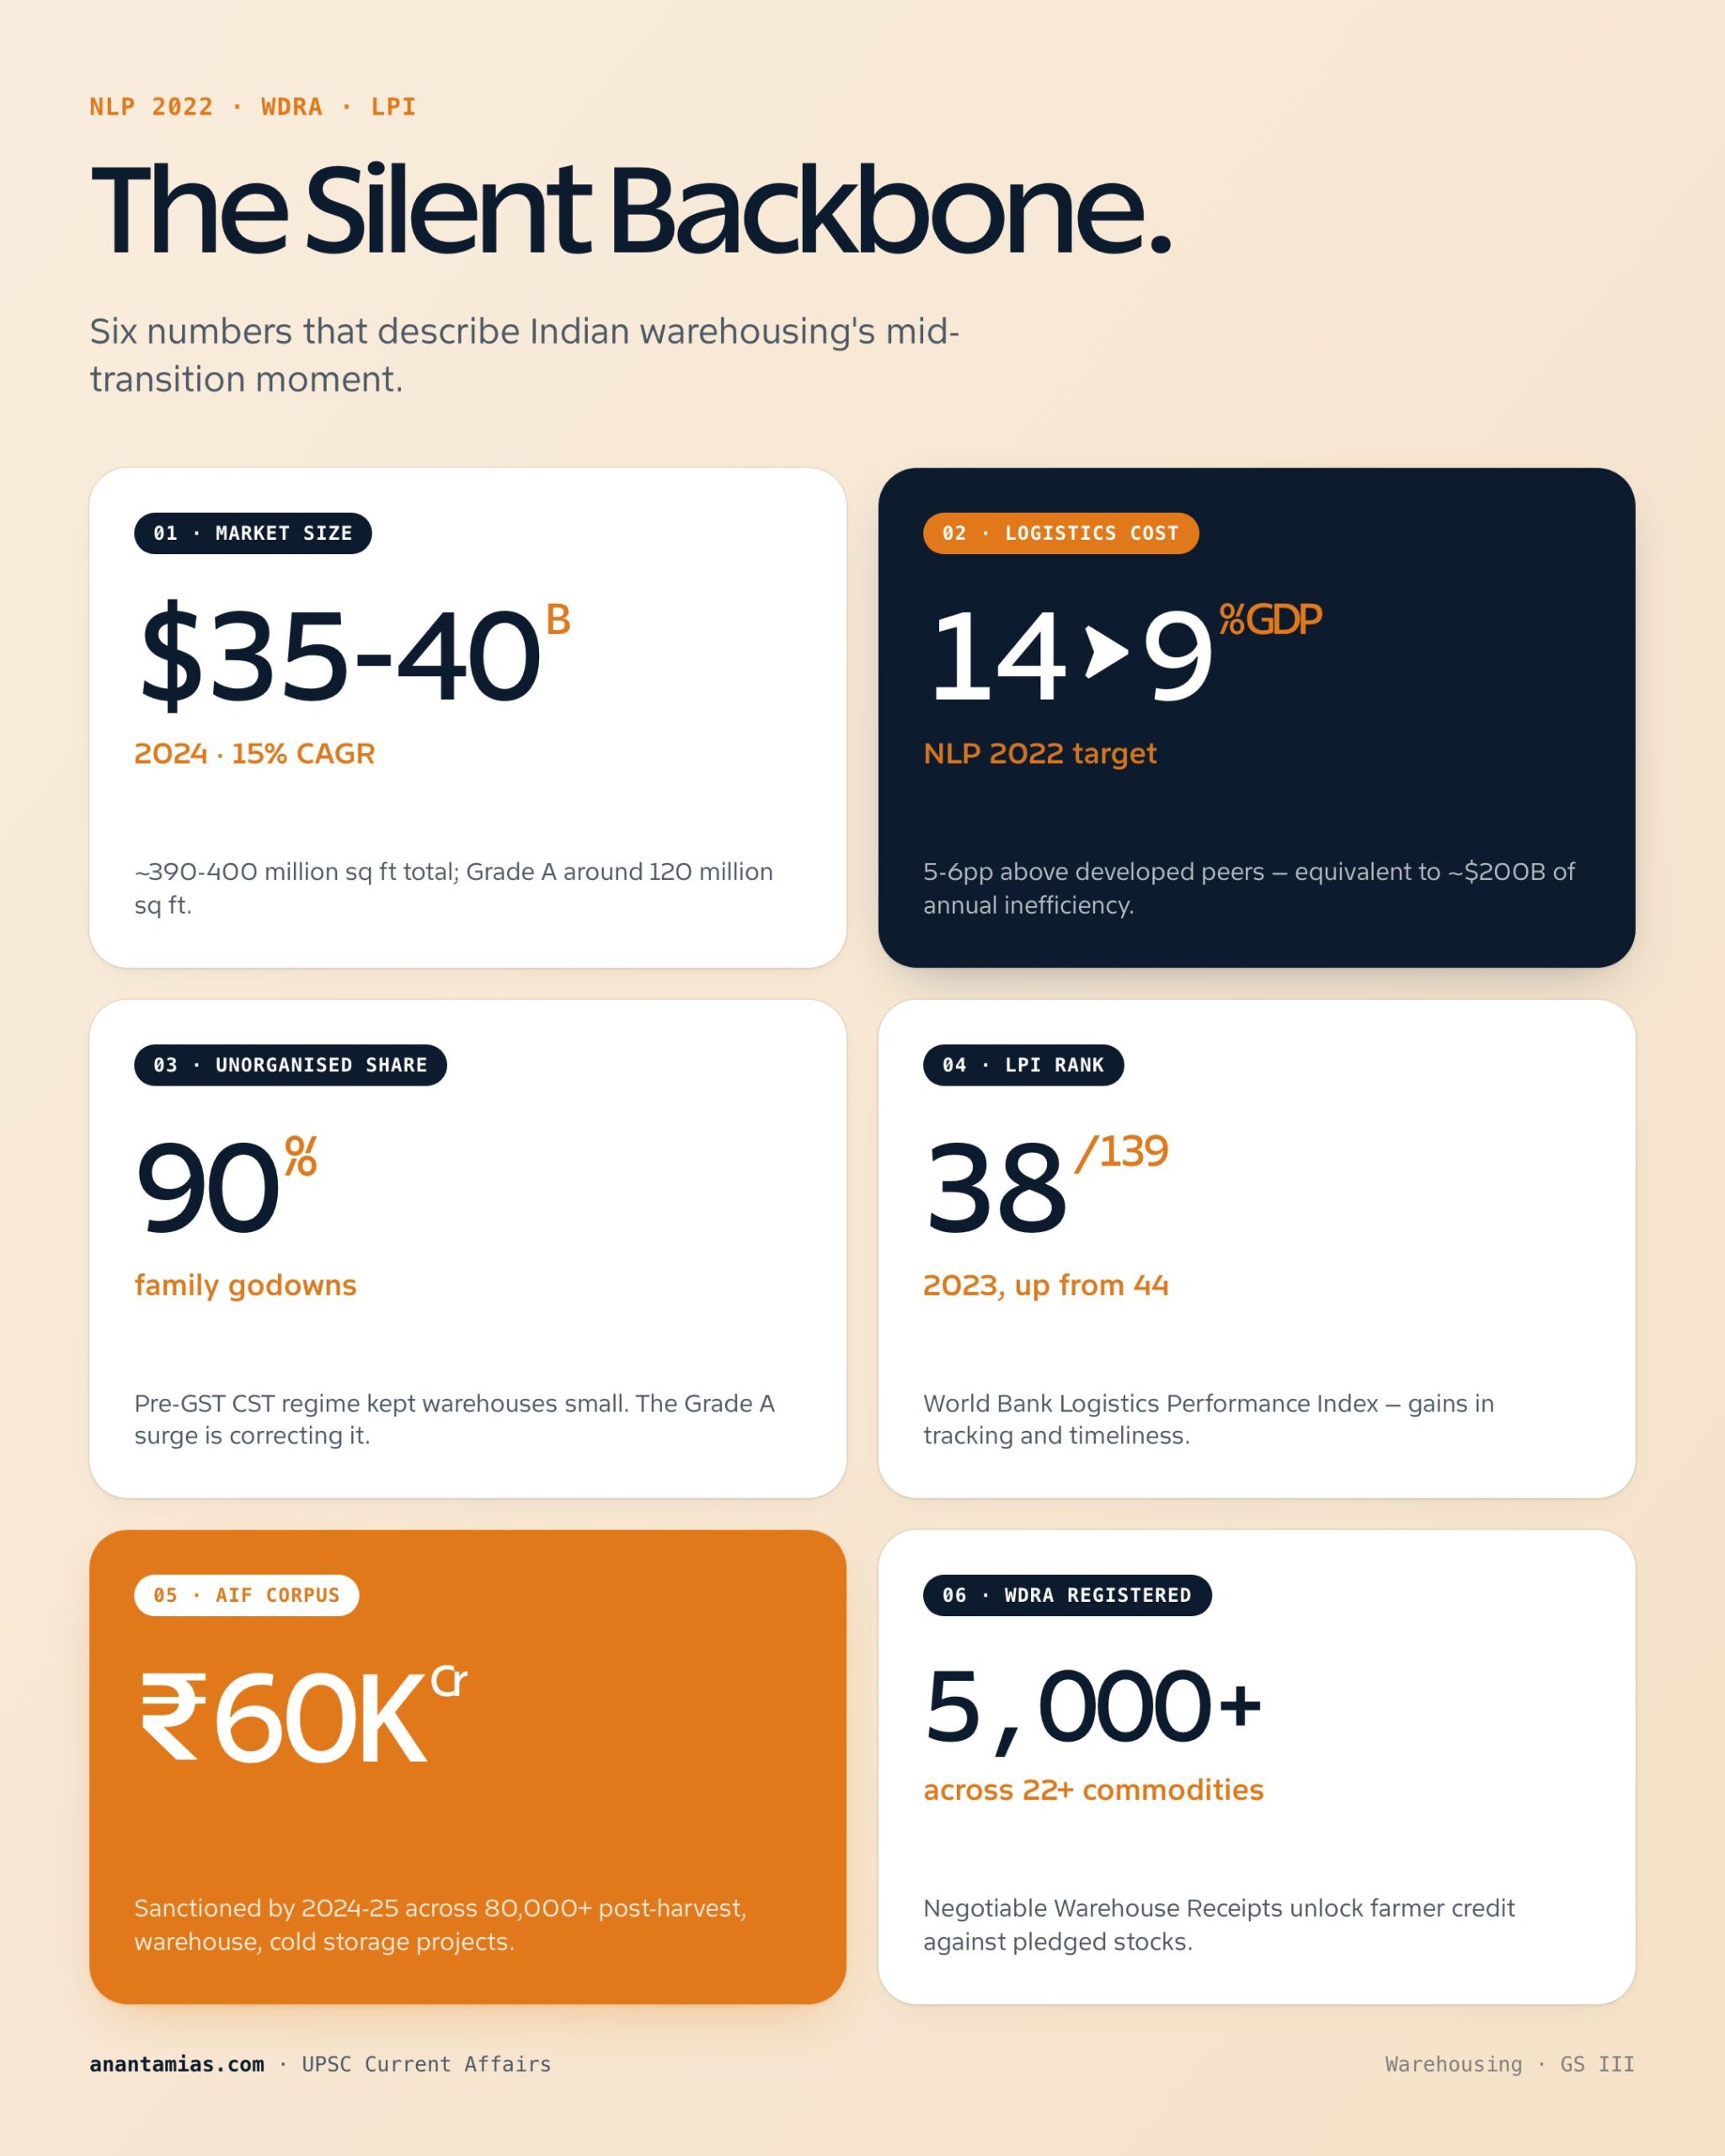
- Logistics costs — India's 14 percent of GDP is among the highest globally; target is 9 percent.
Warehousing is 15-35 percent of total logistics costs but determines whether the rest of the supply chain — transport, sorting, last-mile delivery — runs smoothly.
Status of Indian Warehousing
Market Size
- Indian warehousing market size estimated at USD 35-40 billion in 2024, growing 15 percent CAGR.
- Total warehousing space: ~390-400 million square feet by 2024 (Grade A + B + C).
- Grade A (modern, mechanised, MNC-grade) — ~120 million sq ft.
- Grade A space concentrated in Delhi-NCR, Mumbai-MMR, Bengaluru, Chennai, Pune, Hyderabad and emerging Tier-2 hubs.
Segments
| Segment | Drivers | Examples |
|---|---|---|
| Industrial / general warehousing | Manufacturing, e-commerce | Ambuja, Mahindra Logistics |
| Cold storage | Pharma, perishables, dairy | Snowman, ColdEx |
| Bonded warehouses | International trade, customs | Adani Logistics, JWL |
| Agri-warehousing | FCI, state procurement, WDRA-registered | CWC, SWCs |
| Container Freight Stations (CFS) | Port logistics | Allcargo, Gateway |
| Multi-Modal Logistics Parks (MMLPs) | Multi-mode handling | Bharatmala-anchored MMLPs |
Challenges in Indian Warehousing
1. Fragmentation and Small Scale
- The domestic warehousing market is highly fragmented, with most warehouses under 10,000 square feet.
- Pre-GST, this was driven by the inter-state CST (Central Sales Tax) regime that incentivised firms to keep stock in each consuming state to avoid cascade taxation.
- Small warehouses lack scale economies in mechanisation, IT, and labour productivity.
2. Dominance of Unorganised Players
- Approximately 90 percent of warehousing space is controlled by unorganised players — local landlords, family-owned godowns.
- These warehouses have weak compliance, no IT systems, no professional management.
- Organised, institutional players (Mahindra Logistics, DHL, IndoSpace, ESR) have grown post-GST but still hold a minority share.
3. Limited Mechanisation
- High dependence on manual loading, unloading, and sorting.
- Limited use of conveyor systems, AS/RS (automated storage and retrieval systems), forklifts, racking.
- Productivity per worker is 3-5x lower than China or Southeast Asia.
4. Lower IT Adoption
- Limited adoption of Warehouse Management Systems (WMS), Transportation Management Systems (TMS), barcode/RFID tracking, and IoT sensors.
- Real-time cargo visibility is the exception, not the norm.
5. Higher Storage Costs and Handling Losses
- Storage costs for agricultural produce in India are estimated at 5-10 percent of value annually, versus 2-3 percent in advanced economies.
- Post-harvest losses in fruits, vegetables, and grains estimated at 5-16 percent of output (NITI Aayog 2022; ICAR data).
6. Inadequate Cold Chain
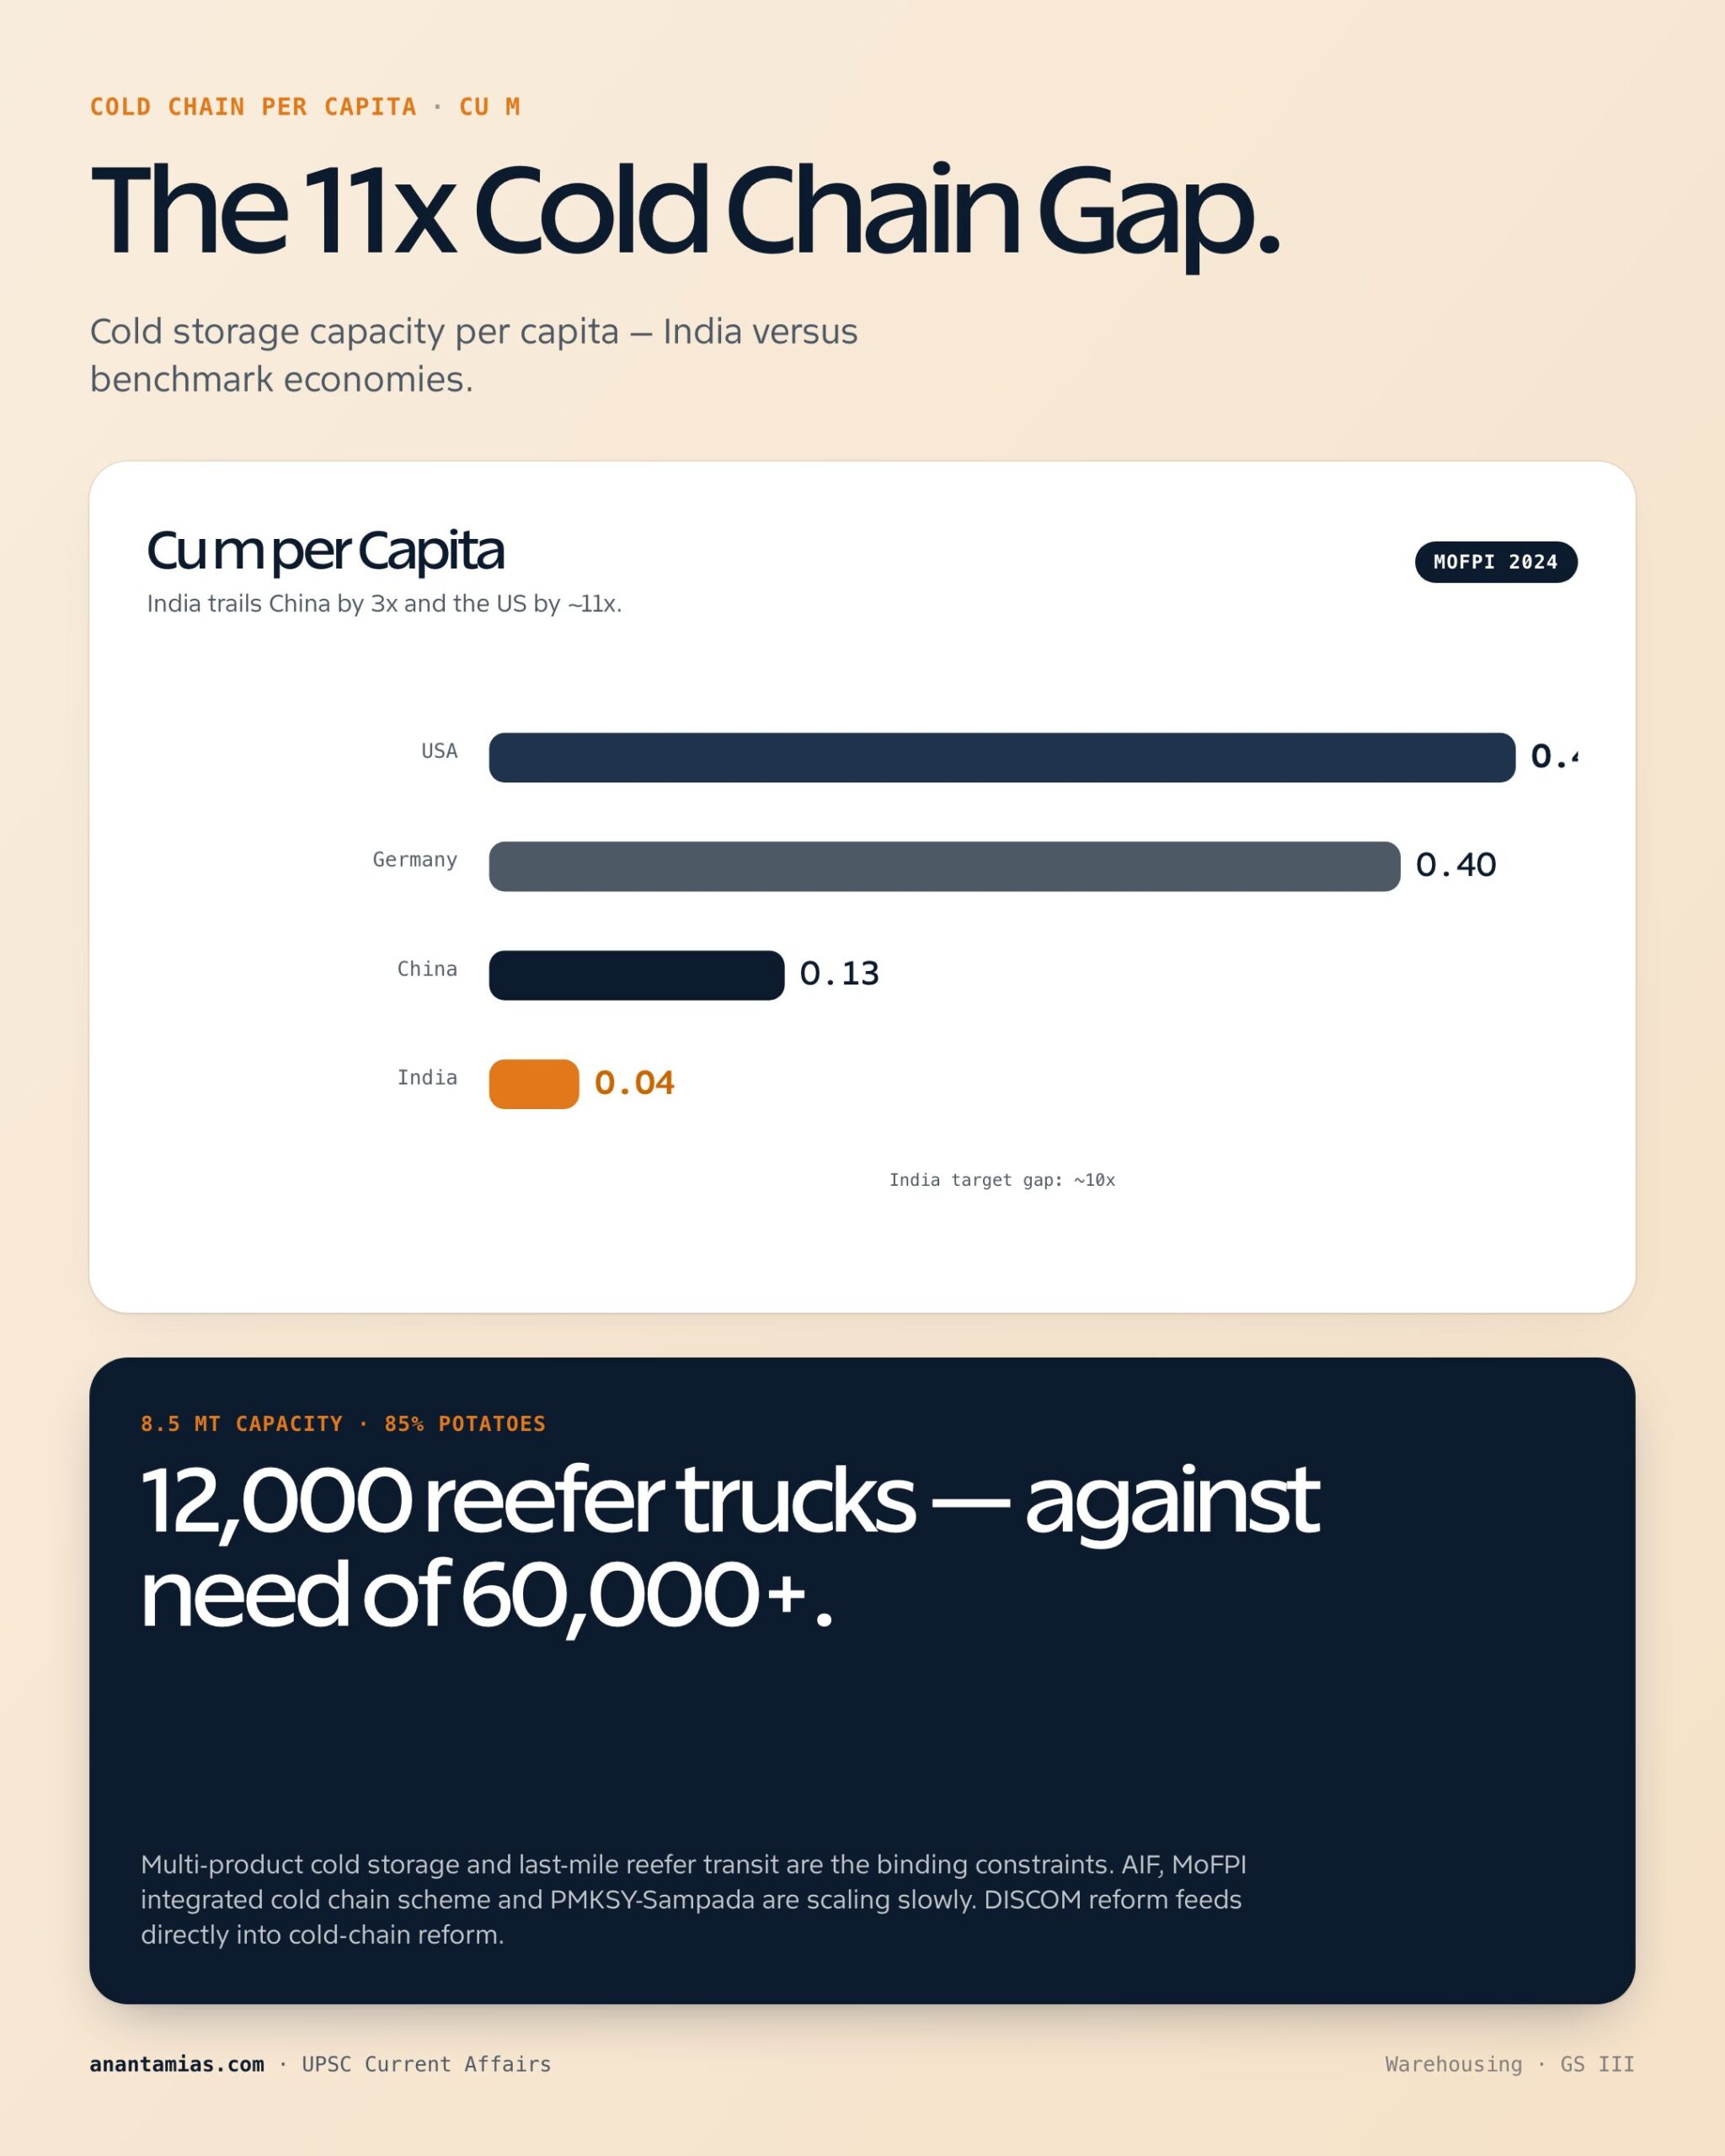
- India has around 8.5 million MT of cold storage capacity (Ministry of Food Processing 2024), concentrated in only a few states (UP, Punjab, Maharashtra).
- Most cold stores serve potatoes only — multi-product cold stores are rare.
- Temperature integrity in transit (reefer trucks, last-mile) is the binding constraint, not just static storage.
7. Underdeveloped 3PL/4PL Market
- Third-Party Logistics (3PL) providers — single firms managing the entire logistics function — have grown but penetration is still low.
- 4PL (consulting plus full management) is still emerging.
- Indian 3PL market size: estimated USD 60-70 billion (2024); CAGR ~12 percent.
8. Land Acquisition
- Land prices near urban demand centres are high; small parcels make Grade A development hard.
- Zoning regulations in many states do not support large logistics parks.
Government Initiatives and Reforms
GST as a Game-Changer (2017)
- The single GST regime removed the inter-state tax cascade.
- Companies could now consolidate stock in fewer, larger, strategically-located warehouses near consumption hubs (Bhiwandi, Hosur, Nagpur, NCR).
- This structural shift triggered the rise of Grade A logistics.
Warehousing Development and Regulatory Authority (WDRA)
- Warehousing (Development and Regulation) Act, 2007.
- WDRA — statutory regulator established in 2010 under the Ministry of Consumer Affairs.
- Issues Negotiable Warehouse Receipts (NWRs) which farmers and traders can pledge against bank loans.
- Over 5,000 warehouses registered with WDRA by 2024-25 across 22+ commodities.
National Logistics Policy 2022
- Released 17 September 2022.
- Goals: cut logistics cost from 14 percent to ~9 percent of GDP; rank in top 25 in World Bank Logistics Performance Index (LPI) by 2030.
- Components: Integrated Digital Logistics Platform (ULIP), Comprehensive Logistics Action Plan (CLAP), Service Improvement Group.
PM Gati Shakti National Master Plan (2021)
- GIS-based platform integrating 36 ministries for infrastructure project planning.
- Spatial planning of MMLPs along major corridors (Delhi-Mumbai, Eastern Dedicated Freight Corridor).
Multi-Modal Logistics Parks (MMLPs)
- 35 MMLPs planned under Bharatmala Phase II at strategic nodes.
- First MMLP commissioned at Jogighopa (Assam) in 2023, with multi-modal connectivity to roads, rail, river (Brahmaputra), and air.
- Hyderabad, Chennai, Indore MMLPs under construction.
PMKSY (Food Processing) and Pradhan Mantri Krishi Sampada Yojana
- Mega Food Parks, Cold Chain Schemes, Agri-Logistics components under MoFPI.
- Cumulative capex: Rs 25,000+ crore by 2025.
PM Agri-Infrastructure Fund (AIF)
- Rs 1 lakh crore agriculture infrastructure financing facility (2020-2032).
- Includes post-harvest infrastructure, warehouses, cold storage.
- By 2024-25: over Rs 60,000 crore sanctioned across 80,000+ projects.
Integrated Cold Chain Infrastructure under MoFPI
- Schemes for integrated cold-chain projects with grants up to 50 percent of project cost.
- Coverage of 600+ projects by 2024.
Recent Developments (2024-26)
- Logistics Performance Index (LPI) 2023: India improved to rank 38 (from 44 in 2018), with notable gains in tracking and timeliness.
- National Logistics Policy rollout: Logistics Data Bank, ULIP (Unified Logistics Interface Platform) onboarded multiple ministries by 2024.
- MMLPs: progress on Indore, Bengaluru, Nagpur, Anantapur.
- Budget 2024-25: Capital outlay for railways at Rs 2.55 lakh crore, port modernisation under Sagarmala, expansion of Inland Waterways.
- Budget 2025-26: Continued rail capex (Rs 2.65 lakh crore), National Manufacturing Mission to support warehousing/factory ecosystems, Critical Minerals Mission with bonded-warehouse implications.
- E-Commerce demand: Quick-commerce (Blinkit, Zepto, Instamart) has triggered demand for dark stores and micro-fulfilment centres in metro micro-markets.
- Foreign investment in warehousing: IndoSpace, ESR, Blackstone, GLP, CapitaLand, Ascendas continue to scale Grade A portfolios.
- REIT structures: Embassy Industrial REIT, Brookfield, and others exploring industrial REIT listings.
- PMFME (formalisation of micro food enterprises) drove demand for cold storage among micro food processors.
Strategy: Way Forward
- Develop warehousing zones outside major cities using NHAI land banks, with PPP development of MMLPs.
- Accelerate WDRA registration and the use of Negotiable Warehouse Receipts to unlock farmer credit.
- Expand cold chain integrated infrastructure under MoFPI and AIF, especially for fruits, vegetables, dairy.
- Scale 3PL and 4PL through tax incentives and skilled workforce.
- Digitise through ULIP, eAWB, eDOCS, RFID-tracked containers.
- Skill development at NSDC's logistics sector skill council; specialised cold chain training.
- Land aggregation through state policies (Tamil Nadu, Maharashtra, Telangana have warehousing-friendly land policies).
- Sustainability — green warehousing with solar rooftops, IGBC-certified buildings.
International Comparisons
| Country | Logistics Cost (% of GDP) | Cold Chain Capacity per Capita (cu m) |
|---|---|---|
| USA | 8% | ~0.45 |
| Germany | 8% | ~0.40 |
| China | 11% | ~0.13 |
| India | 14% (target 9% by 2030) | ~0.04 |
India's logistics costs are 5-6 percentage points of GDP higher than developed peers — equivalent to USD 200 billion of annual inefficiency. Closing the gap unlocks competitiveness for manufacturing, agriculture, and exports.
UPSC Relevance
GS-III Mapping
- Infrastructure: Energy, Ports, Roads, Airports, Railways.
- Major crops, cropping patterns, e-technology in farming, storage, transport and marketing.
- Land reforms in India (warehousing land aggregation).
- Effects of liberalisation on the economy (GST and warehousing transformation).
- Food security and storage — FCI, buffer stocks.
Prelims Pointers
- WDRA — statutory body under Warehousing (Development and Regulation) Act, 2007.
- Negotiable Warehouse Receipts (NWRs) — pledgeable instruments under WDRA.
- National Logistics Policy — September 2022.
- PM Gati Shakti — October 2021.
- Multi-Modal Logistics Parks under Bharatmala.
- Logistics Performance Index — World Bank; India rank 38 in 2023.
- Agriculture Infrastructure Fund — Rs 1 lakh crore (2020-2032).
Mains Hooks
- "Examine the structural challenges of Indian warehousing and the role of GST, WDRA and the National Logistics Policy in modernising it." (GS-III)
- "Discuss the cold chain infrastructure deficit in India and its implications for agriculture and food security."
- "How does warehousing inefficiency contribute to India's high logistics costs? Suggest reforms."
- "What role can Multi-Modal Logistics Parks play in reducing India's trade and logistics costs?"
Indian warehousing is mid-transition. The structural enablers — GST, NLP, Gati Shakti, MMLPs, AIF are in place. The commercial enablers — Grade A players, REITs, FDI in industrial real estate are scaling. What remains is execution at scale, particularly for cold chain and rural agri-warehousing. For UPSC, master the challenges, GST-led shift, regulatory architecture (WDRA, NWR), and the 2024-26 reform package, and you will hold strong answers for any GS-III logistics or food-security question.
Warehouse Grades — A Quick Reference
| Grade | Specifications | Primary Use |
|---|---|---|
| Grade A | 32+ ft clear height, mechanised, IT-enabled, high-quality flooring, dock levellers, fire systems | E-commerce, FMCG, automotive, pharma |
| Grade B | 25-32 ft, partial mechanisation, basic IT | General manufacturing, MSME |
| Grade C | 18-25 ft, minimal infrastructure | Local trade, agricultural produce |
| Cold Storage | Temperature-controlled (-25°C to 15°C), insulated panels, refrigeration | Pharma, dairy, fruits, vegetables, frozen food |
| Bonded Warehouse | Customs-controlled storage of imported/export goods | Trade, ports, EOUs |
Modern e-commerce and quick-commerce demand have shifted demand sharply toward Grade A and a new category of dark stores (small, urban-edge fulfilment centres for 10-30 minute delivery).
E-Commerce as a Driver
- E-commerce GMV crossed USD 110-120 billion in 2024, projected to reach USD 350 billion by 2030.
- Quick-commerce alone (Blinkit, Zepto, Swiggy Instamart) is creating demand for dark stores in metro micro-markets, often <5,000 sq ft each but with high turnover.
- Reverse logistics infrastructure for returns and repairs has emerged as a sub-category.
- E-commerce has driven warehousing demand in Tier-2 and Tier-3 cities for last-mile fulfilment.
Agri-Warehousing and Food Security
The Food Corporation of India (FCI) and Central Warehousing Corporation (CWC), State Warehousing Corporations (SWCs) together hold around 80 million MT of foodgrain storage. Yet:
- Storage losses remain 3-5 percent annually.
- Many older godowns lack pest control, ventilation.
- Modern silos under PEG (Private Entrepreneurs Guarantee scheme) are scaling.
- Wheat silos at Kaithal, Moga, Khanna, Karwar, Whitefield, etc.
- Hub-and-spoke silo network across procurement-heavy states would cut losses significantly.
Cold Chain Specifics
- Indian cold storage capacity: ~8.5 million MT (2024).
- Concentration in potatoes (~85 percent capacity).
- Multi-product cold storage is the bottleneck.
- Reefer trucks in service: ~12,000 (vs need of 60,000+).
- Last-mile cold transport is the weakest link.
- AIDF (Agri Infrastructure Development Fund) and MoFPI integrated cold chain scheme are scaling capacity, but slow.
- Cold chain growth needs uninterrupted power — DISCOM reform feeds into cold chain reform.
Real Estate Investment Trusts (REITs)
- Embassy Office Parks REIT, Mindspace REIT, Brookfield REIT — listed since 2019.
- Industrial REITs are emerging — Embassy Industrial Parks preparing for listing.
- REITs provide public-market funding for warehousing and lower the cost of capital.
- Foreign capital flows in through both FDI in industrial parks and FPI in REIT units.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.