Why in News?
After a four-month retreat, Foreign Portfolio Investors (FPIs) turned net buyers of Indian equities in early July, prompting a debate on whether India’s roughly two-year market underperformance can really be blamed on the global AI rally and geopolitics, or whether it reflects stretched valuations and weak earnings.
An Indian Express Explained piece reported that FPIs bought Indian shares worth about $1.6 billion in the first ten days of July, even as brokerages including Kotak Institutional Equities called the AI-and-geopolitics explanation for India’s lag ‘superficial’.
The distinction matters for policy and for aspirants alike: if the weakness is cyclical — driven by where global money happens to be flowing — it should reverse on its own; if it is structural — rooted in overpriced stocks and thin profit growth — no return of foreign flows will fix it, and the fix must come from the real economy.
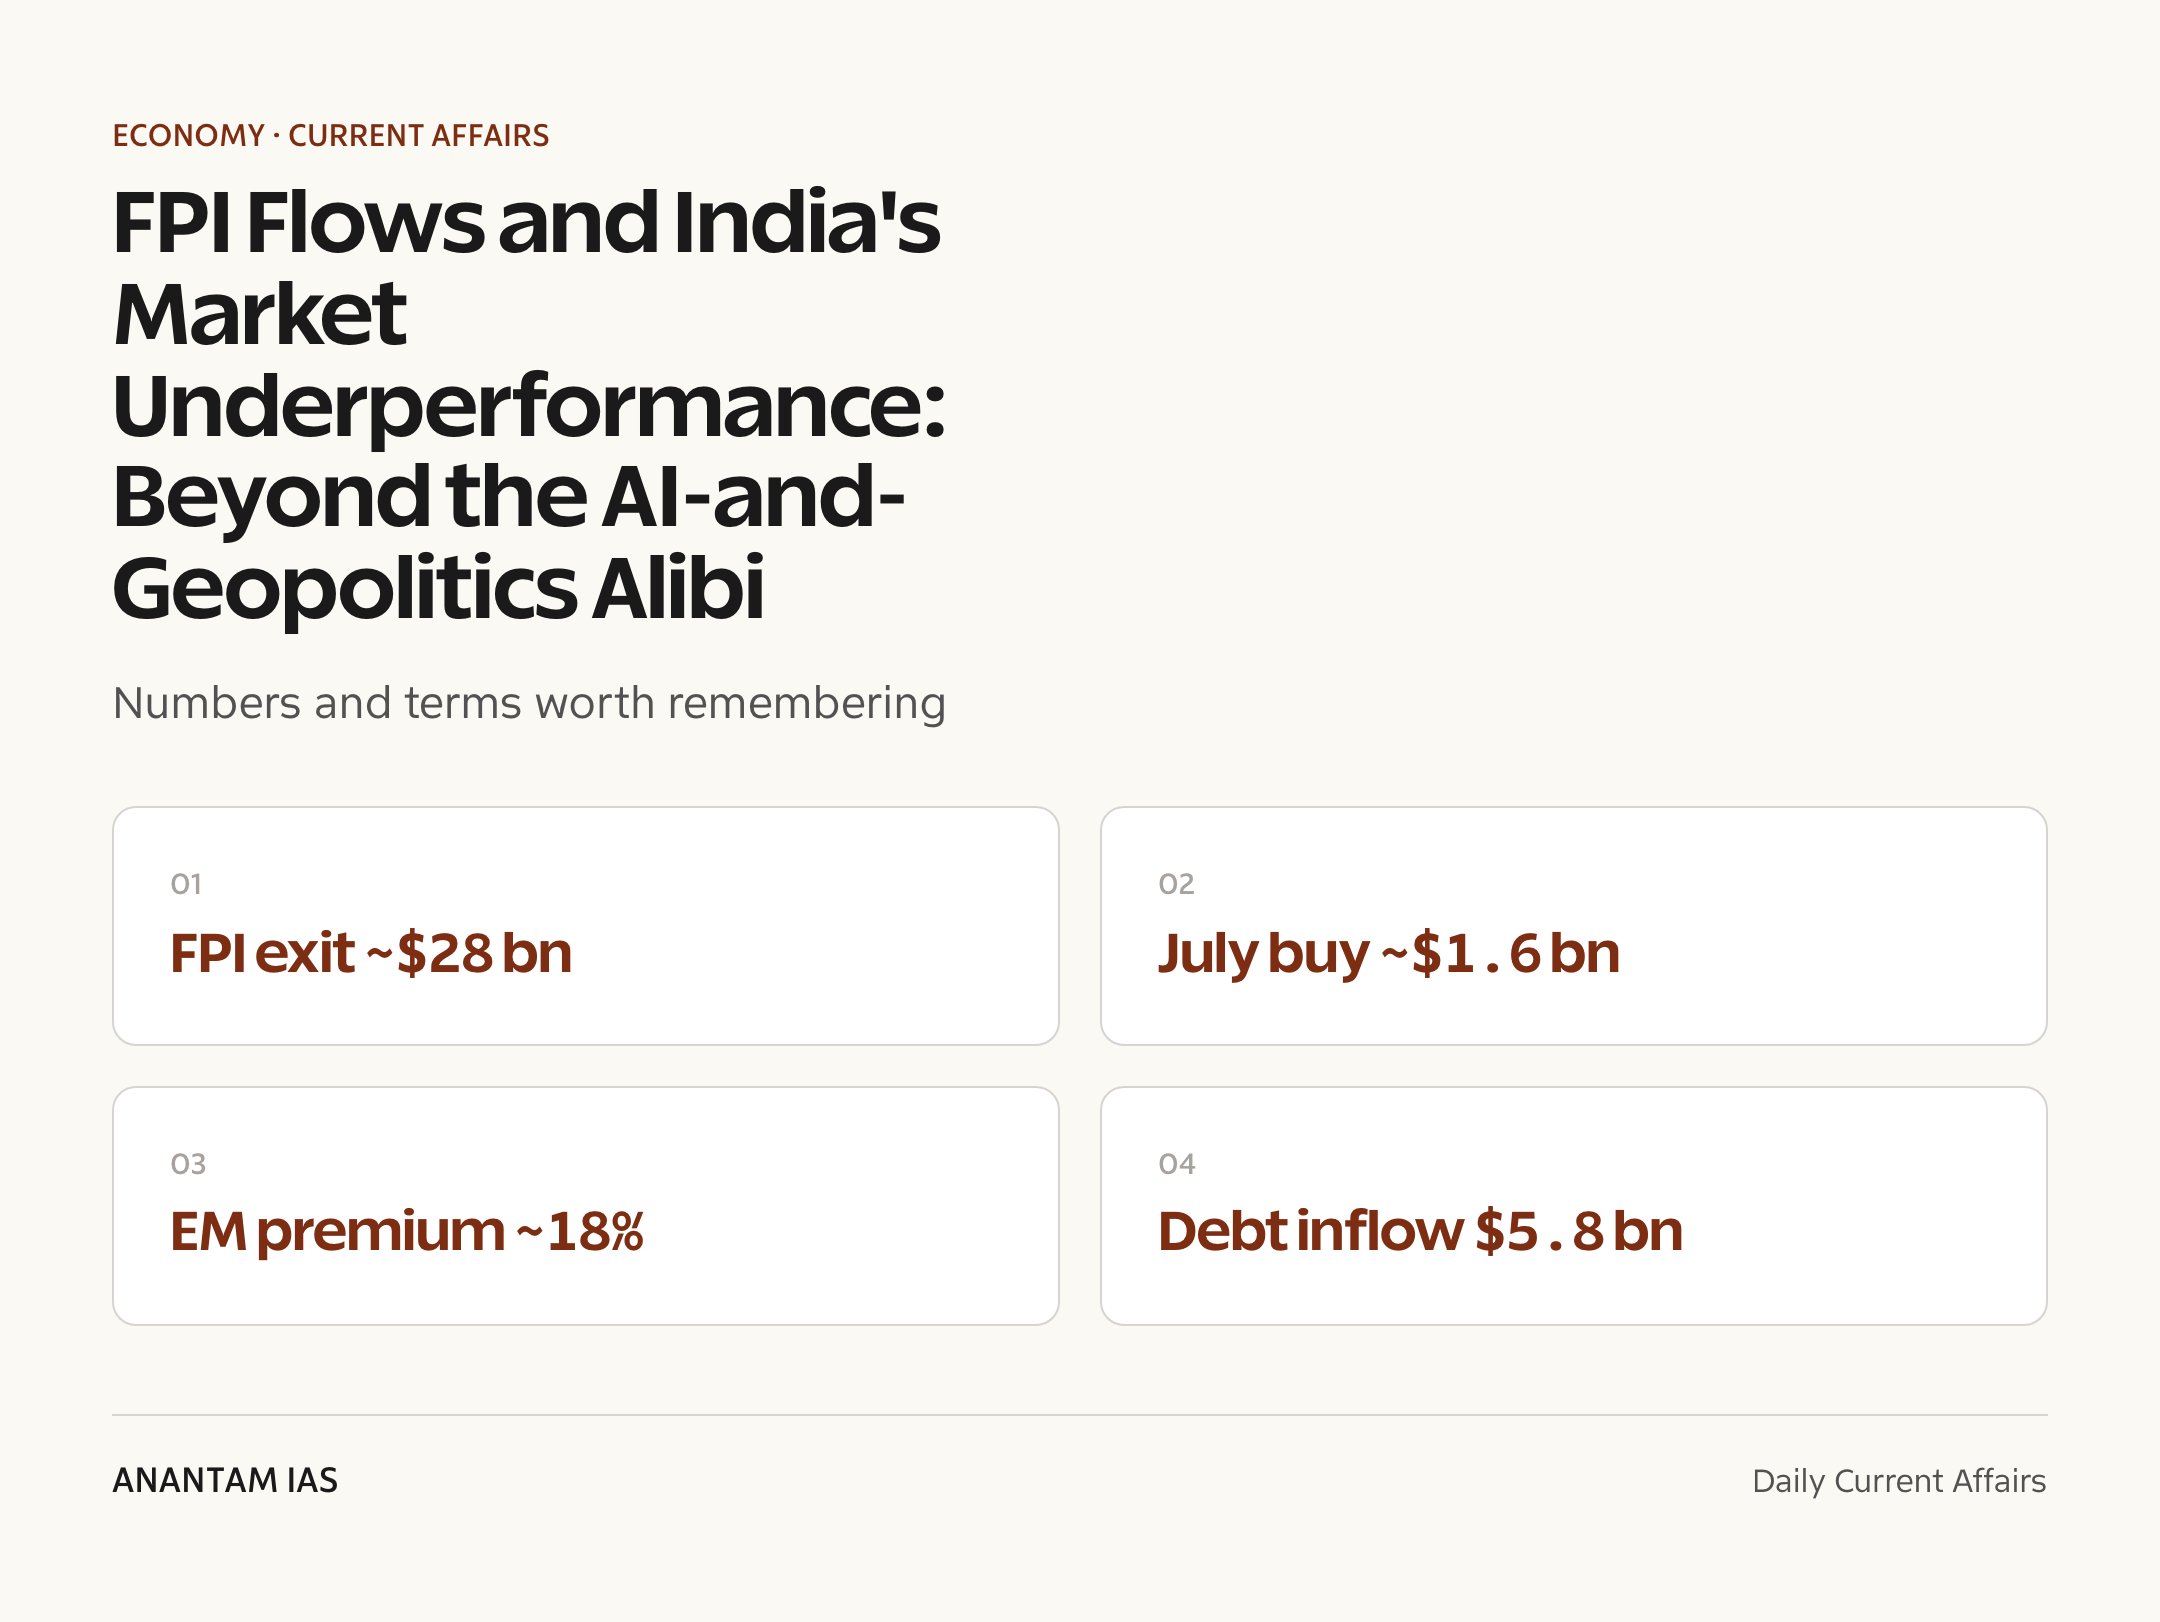
- A West Asia conflict in late February triggered a roughly $28-billion FPI exit from Indian equities over the following four months.
- Sentiment turned after a US-Iran de-escalation around mid-June; the second half of June saw net inflows of about $1.1 billion after outflows of $6.7 billion in the first half.
- India’s equity valuation premium over emerging-market peers compressed to a historic low of about 18% in June, well below its long-term average near 73% and a CY22 peak of 147%, per Motilal Oswal.
- Foreign inflows into the debt market jumped to roughly $5.8 billion in June from just $291 million in May, aiding a steadier rupee.
The development matters in the context of:
- FPI is the classic ‘hot money’ whose sudden entry and exit swings the Sensex, Nifty, the rupee and the Balance of Payments — a core GS3 external-sector theme.
- The episode tests whether market weakness is a cyclical global-flows story or a structural earnings-and-valuation problem.
UPSC Relevance
Prelims Relevance
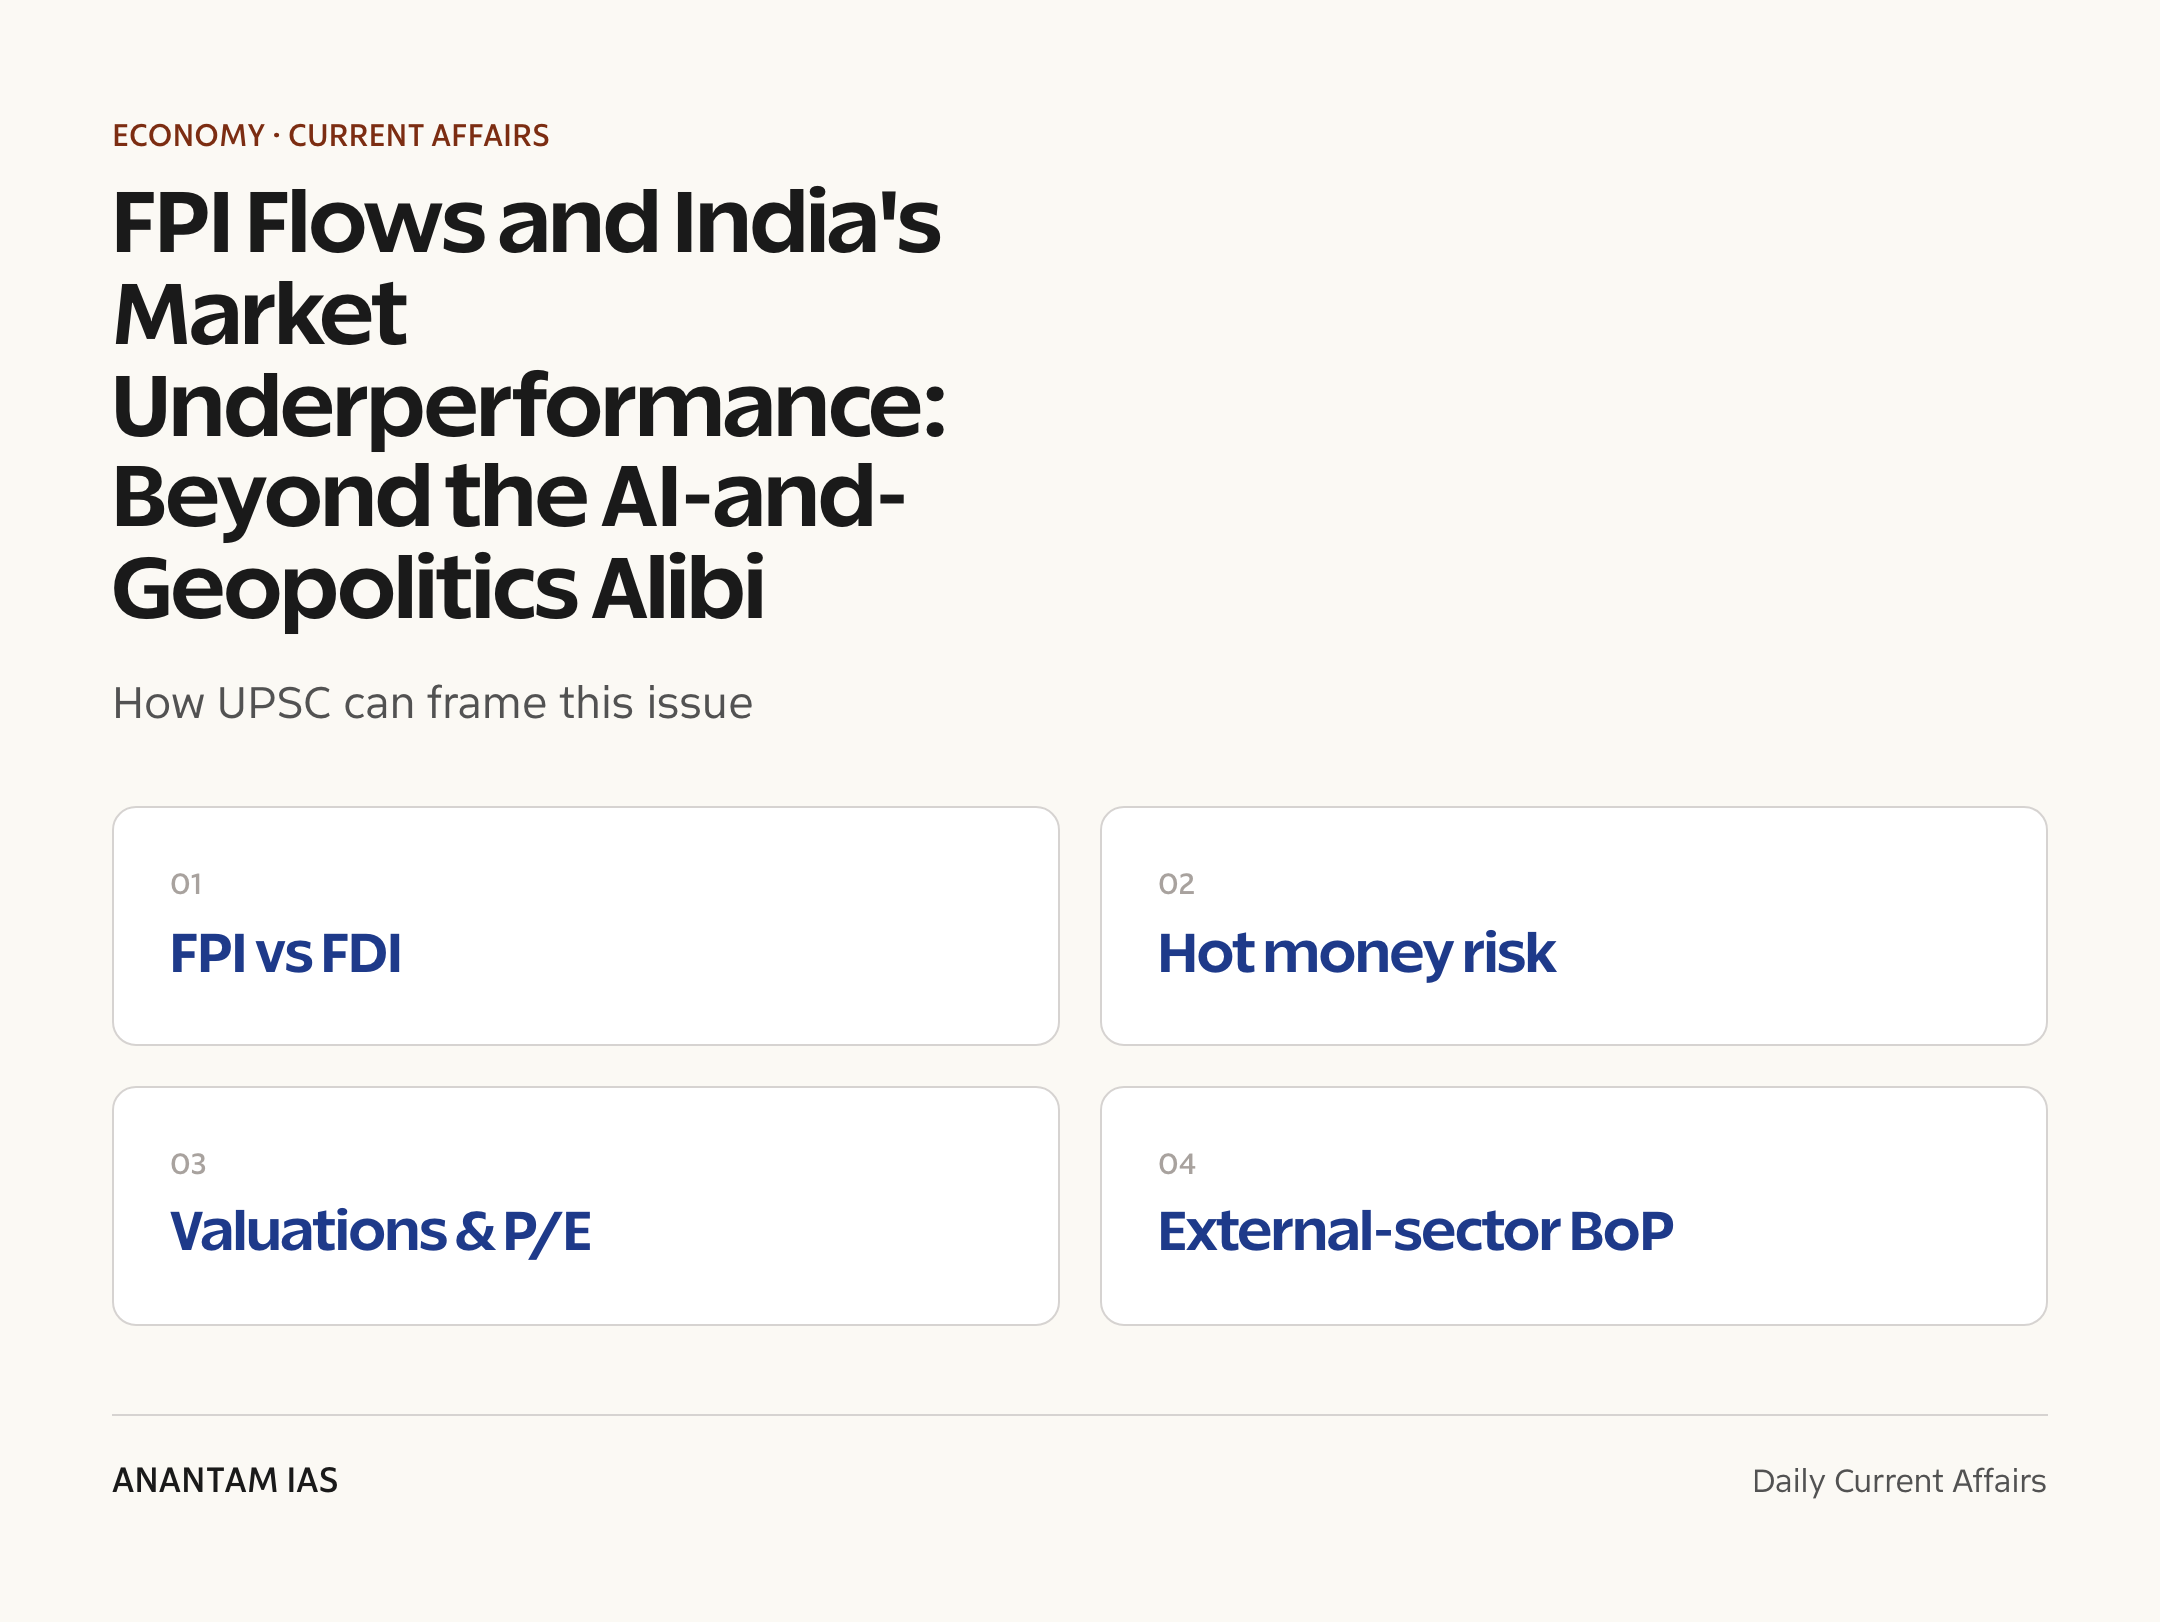
- FPI — investment below 10% stake in listed securities, regulated by SEBI under the FPI Regulations, 2019 and by the RBI under FEMA, 1999.
- FDI — investment of 10% or more with a lasting interest/management intent, under the FDI Policy and FEMA.
- FII (Foreign Institutional Investor) — the older term now subsumed under the FPI framework.
- MSCI Emerging Markets Index — China carries the largest weight (near a third); India is among the top components.
- Hot money — short-term, volatile capital that chases yield and exits fast.
- Balance of Payments (BoP) — FPI is recorded in the capital account; FDI too, but with different stability.
- Price-to-earnings (P/E) ratio — a valuation gauge; India’s forward P/E has hovered near its long-run average.
- Capital-gains tax on listed equity — STCG at 20% and LTCG at 12.5% (post-2024 rates).
Mains Relevance
GS Paper 3
- The role of FPI in India’s capital markets and external sector — liquidity benefits versus ‘hot money’ volatility.
- Whether India’s market underperformance is cyclical (global flows) or structural (earnings, valuations, business-model risk).
GS Paper 2
- SEBI and RBI as co-regulators of foreign capital — governance of markets and investor protection.
Essay
- Markets reward substance, not narratives — the limits of the ‘story stock’ in a real economy.
- Openness with resilience: managing volatile capital in a globalised economy.
Background and Context
FPI versus FDI — the durable distinction
The single most-tested idea here is how portfolio money differs from direct investment, in both intent and stability.
- FDI is a lasting stake — typically 10% or more of equity — carrying management interest; it builds factories, jobs, technology and supply chains and does not exit quickly.
- FPI is passive investment in listed shares and bonds below the 10% threshold, purely for financial returns, with no control over the company.
- Regulator split: FDI falls under the government’s FDI Policy and FEMA (RBI); FPI is governed by SEBI under the FPI Regulations, 2019, alongside RBI’s FEMA rules.
- The older term FII (Foreign Institutional Investor) has now been merged into the single FPI category to simplify the framework.
- Both flows are recorded in the capital account of the Balance of Payments, but they behave very differently under stress.
- Because FPI can be pulled out in days, it is called ‘hot money’ — it deepens markets and lowers the cost of capital in good times, but amplifies shocks when it flees, transmitting global sentiment straight into Indian asset prices.
What the numbers show
The flow data frames the story of exit, return and a shrinking premium.
- A late-February West Asia conflict set off a roughly $28-billion FPI outflow from equities over four months.
- A mid-June US-Iran de-escalation flipped sentiment; June’s second half saw about $1.1 billion of net inflows against $6.7 billion of outflows in its first half.
- In the first ten days of July, FPIs bought about $1.6 billion of Indian shares.
- The recovery was fragile — equities fell over 2% mid-week on renewed West Asia tension, underlining how geopolitics whipsaws sentiment.
The valuation angle
India has long traded at a premium to peers on the promise of faster growth; that cushion has thinned sharply.
- A valuation premium means investors pay more per rupee of earnings for Indian stocks than for peers, betting on stronger future growth.
- Per Motilal Oswal, India’s valuation premium over emerging markets fell to a historic low of about 18% in June, versus a long-term average near 73% and a CY22 peak of 147%.
- A lower premium leaves ‘limited downside’, so some desks argue foreigners may treat India as a relatively safe AI alternative after AI-driven markets ran hot.
- The price-to-earnings (P/E) ratio compares share price to per-share profit — a quick gauge of whether a market is cheap or expensive.
- India’s forward P/E has stayed close to its long-run average, but bulls and bears read the same number differently — cheap-relative-to-history versus still-expensive-on-weak-earnings.
The AI and geopolitics 'alibi'
The headline debate is whether external factors truly explain a two-year lag.
- Global money has crowded into AI-heavy markets such as South Korea, drawing flows away from India — a convenient external explanation.
- Kotak Institutional Equities (analysts led by Sanjeev Prasad) called this ‘superficial’, arguing the market was ‘too complacent’ on business-model quality, ‘too generous’ on valuations and ‘too optimistic’ on earnings.
- They flagged the sharp erosion in the market value of IT services firms as evidence of real disruption risk, not just a passing mood.
The earnings problem
Valuations can only be justified by profit growth, and that has disappointed for several quarters.
- Average net profit of Nifty 50 companies grew in mid-to-high single digits in FY26 — better than the 0.8% of a year earlier, but far below the 15-20% seen just after Covid.
- Systematix’s Dhananjay Sinha argued the market stays ‘expensive’ with ‘no earnings growth to match it’, doubting a strong profit rebound from here.
- When prices ran up faster than profits, the gap had to close either through stronger earnings or weaker prices — and so far it is prices that have given way.
- Weak earnings plus high starting valuations is the classic recipe for underperformance regardless of foreign flows.
- This is why analysts frame the slump as at least partly structural — a domestic profit problem that cheap money from abroad cannot paper over.
The debt-inflow and rupee link
Policy nudges on debt indirectly steadied the currency that equity investors watch.
- The government and RBI announced early-June measures to boost debt inflows; foreign debt investment surged to about $5.8 billion in June from just $291 million in May.
- A steadier rupee matters because currency depreciation can ‘significantly erode’ dollar-denominated returns for overseas equity investors.
- Better debt flows also support the Balance of Payments and deeper foreign participation — indirect positives for equities.
Way Forward
Deepen domestic buffers
- Grow the domestic institutional base — mutual funds, SIPs, insurance and pension money — so markets lean less on volatile foreign flows.
- Sustain the shift toward stable, long-term FDI and quality debt inflows over pure portfolio money.
Fix the fundamentals
- Corporate earnings growth, not narrative, is the durable driver — support demand, capex and productivity so profits justify valuations.
- Guard against complacency on business-model disruption risk, especially in export-facing sectors like IT services.
Keep external buffers strong
- Adequate forex reserves, a stable rupee and a manageable current account help absorb sudden FPI reversals.
Conclusion
The return of FPIs is welcome but modest, and it does not settle the deeper question. Blaming India’s two-year lag entirely on the AI rally and geopolitics risks ignoring what analysts see as stretched valuations and soft earnings — a distinction between a passing external mood and a home-grown fundamentals problem.
The policy takeaway is to reduce dependence on volatile foreign flows by deepening the domestic investor base, sustaining stable FDI and quality debt inflows, and keeping external buffers like forex reserves and the rupee strong enough to absorb sudden reversals.
For aspirants, the episode is a clean case study in how hot money, currency and the real economy interact. Markets ultimately track profits and macro fundamentals; foreign flows amplify moves but rarely create value on their own.
UPSC Practice Questions
Prelims MCQ 1
With reference to Foreign Portfolio Investment (FPI) in India, consider the following statements:
- FPI in listed securities is regulated by SEBI under the FPI Regulations, 2019.
- An equity stake of 10% or more by a single foreign investor is treated as FDI rather than FPI.
- FPI is generally regarded as more stable, long-term capital than FDI.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 1 and 2 are correct. FPI is SEBI-regulated under the FPI Regulations, 2019, and a stake of 10% or more is classified as FDI. Statement 3 is wrong — FPI is volatile ‘hot money’; FDI is the more stable, long-term capital.
Prelims MCQ 2
The term ‘hot money’, often used in discussions of India’s external sector, most appropriately refers to:
(a) Currency printed by the RBI during a fiscal deficit (b) Short-term, volatile foreign portfolio capital that can exit rapidly (c) Black money circulating in the domestic economy (d) Long-term foreign direct investment in manufacturing
Answer: (b) Short-term, volatile foreign portfolio capital that can exit rapidly
Explanation:
‘Hot money’ denotes short-term FPI flows that chase returns and can be withdrawn quickly, swinging markets, the rupee and the Balance of Payments.
UPSC Mains Questions
- ‘India’s stock-market underperformance reflects fundamentals more than foreign-flow narratives.’ In light of recent FPI behaviour, examine the roles of valuations, corporate earnings and geopolitics in shaping equity market outcomes. (250 words)
- Distinguish between Foreign Direct Investment and Foreign Portfolio Investment, and assess why an economy dependent on ‘hot money’ faces greater external-sector vulnerability. Suggest measures to reduce this dependence. (150 words)
Sources: The Indian Express (Explained Economics) and SEBI FPI Regulations, 2019.
Frequently Asked Questions
What is the difference between FPI and FDI?
FDI is a lasting stake — usually 10% or more of a company’s equity — that brings management interest and builds real productive capacity like factories and jobs. FPI is passive investment in listed shares and bonds below that threshold, made only for financial returns without control. FDI is stable and long-term; FPI can exit quickly.
Why is FPI called ‘hot money’?
Because it is short-term and highly mobile. Foreign portfolio investors can buy and sell listed securities within days, chasing better returns elsewhere. Large, sudden inflows or outflows swing the Sensex, Nifty, the rupee and the Balance of Payments, making FPI a key source of external-sector volatility for India.
Who regulates FPI in India?
FPI is regulated by SEBI under the SEBI (Foreign Portfolio Investors) Regulations, 2019, and by the Reserve Bank of India under the Foreign Exchange Management Act, 1999. FDI, by contrast, is governed by the government’s FDI Policy and FEMA, with the RBI overseeing the foreign-exchange side.
Why have India’s markets underperformed recently?
Global money crowded into AI-heavy markets, drawing flows away from India, and a West Asia conflict triggered a large FPI exit. But analysts like Kotak argue the deeper reasons are stretched valuations and weak corporate earnings, calling the AI-and-geopolitics explanation ‘superficial’.
How does the rupee affect foreign equity investors?
Overseas investors earn returns in dollars, so a falling rupee erodes those returns even if Indian share prices rise. A stable currency, by protecting dollar returns, encourages foreign equity inflows. Stronger debt inflows and healthy forex reserves help keep the rupee steady, indirectly supporting equity sentiment.
What is the MSCI Emerging Markets Index?
It is a benchmark tracking large and mid-cap stocks across emerging economies. China carries the largest weight, close to a third, and India is among its top components. Global funds allocate money by such index weights, so shifts in the index influence how much foreign capital flows into Indian equities.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.