Why in News?
A science feature in The Hindu revisits a recurring puzzle in India’s clean-energy story: the country has crossed 50 GW of installed wind capacity and ranks among the world’s top four wind markets, yet it operates zero offshore wind turbines and has barely begun repowering its first-generation onshore farms.
Both gaps matter for the headline goal — 500 GW of non-fossil capacity by 2030 (the Panchamrit pledge) — because wind is the natural night-time and monsoon complement to solar, and the cheapest extra wind energy may come from upgrading existing windy sites rather than chasing new land.
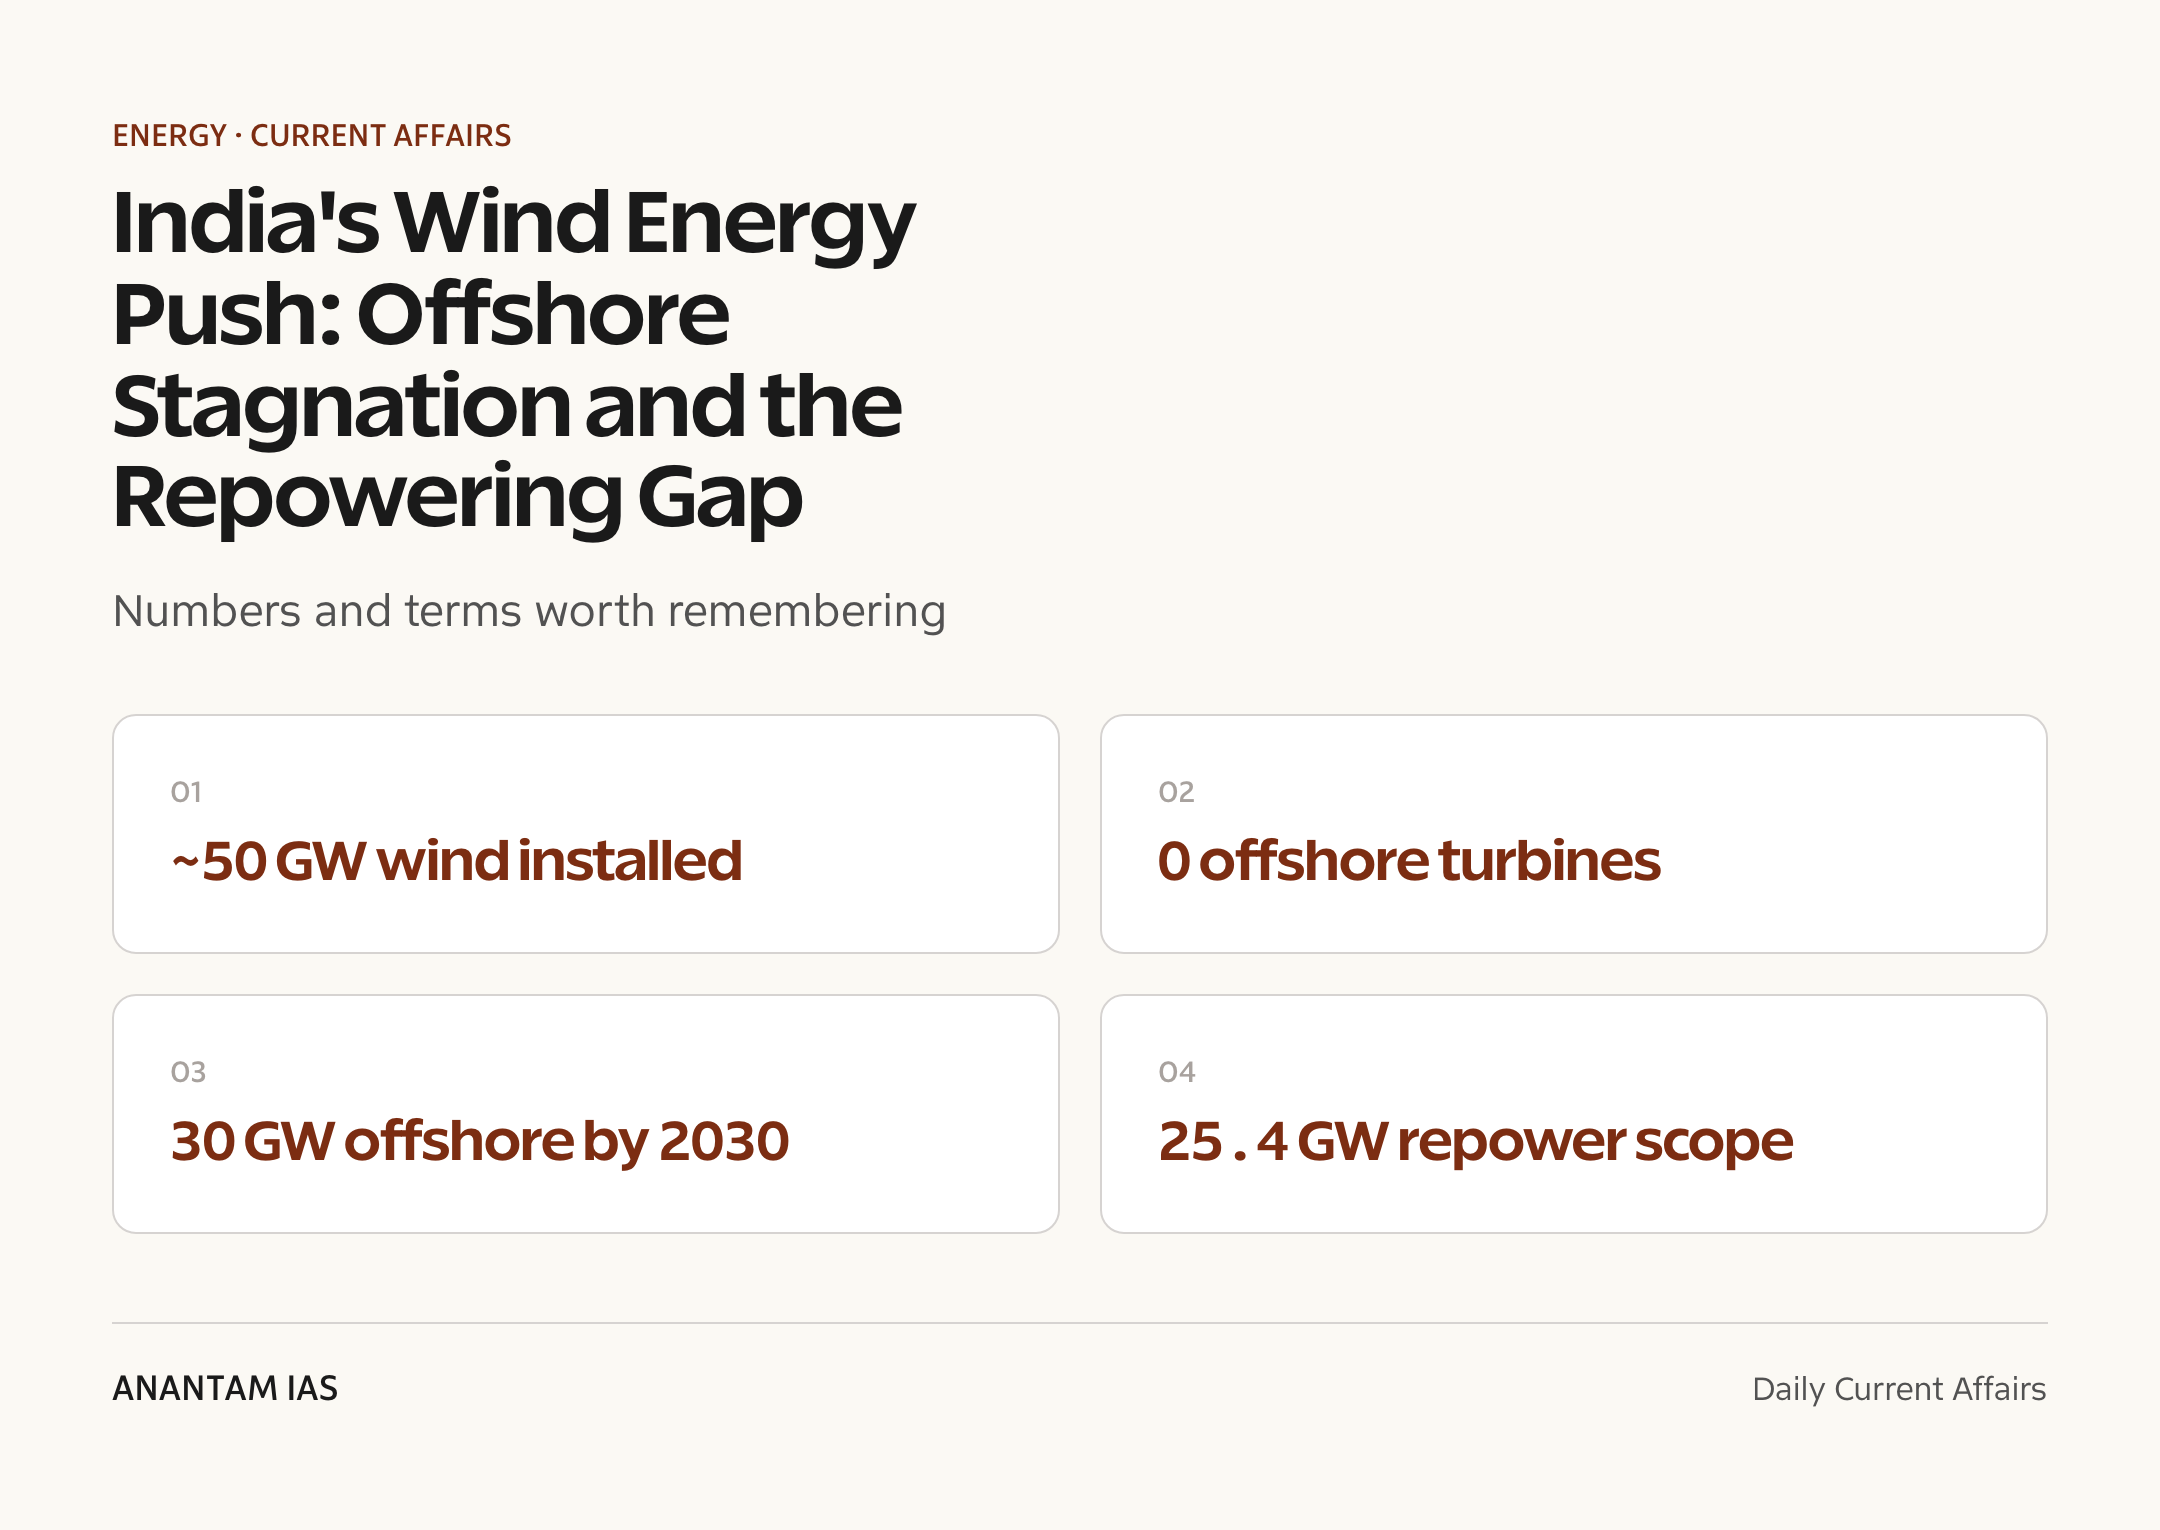
- India’s cumulative wind capacity stood at roughly 50 GW (about 50.04 GW as of April 2025), almost entirely onshore.
- Offshore installed capacity remains effectively zero, despite a policy in place since 2015 and a 30 GW by 2030 offshore target.
- Repowering of old, sub-2 MW turbines at the best windy sites has been slow, even after MNRE revised the repowering policy in December 2023.
- NIWE has assessed national repowering potential at about 25.4 GW, concentrated in turbines below 2 MW.
- Government has approved ₹6,853 crore in Viability Gap Funding for the first 1,000 MW of offshore wind off Gujarat and Tamil Nadu.
The development matters in the context of:
- Wind is a variable renewable: output rises in the monsoon and at night, partly offsetting solar’s daytime-only profile.
- India’s wind fleet is geographically concentrated — Gujarat leads, followed by Tamil Nadu, with the southern and western windy belts dominating.
- Many older farms sit on the windiest land but carry small, low-yield turbines installed in the 2000s — a classic case for repowering.
- Annual wind additions slowed sharply after India switched from fixed feed-in tariffs to competitive reverse auctions around 2017, squeezing margins and stalling new orders.
- Wind sits inside a broader push covered in our note on renewable energy in India, where solar has scaled faster than wind in recent years.
UPSC Relevance
Prelims Relevance
- India’s installed wind capacity is around 50 GW, nearly all onshore; the country is among the top four global wind markets.
- Gujarat has the highest installed wind capacity, followed by Tamil Nadu; the two together account for roughly half the national total.
- The National Offshore Wind Energy Policy was notified in 2015; MNRE is the nodal ministry.
- The National Institute of Wind Energy (NIWE), Chennai, is the implementing/nodal agency for resource assessment and offshore block demarcation.
- India targets 30 GW of offshore wind by 2030; Gujarat (~36 GW) and Tamil Nadu (~35 GW) hold the bulk of identified offshore potential.
- Viability Gap Funding (VGF) of ₹6,853 crore has been approved for the first 1,000 MW of offshore wind.
- The Panchamrit pledge (COP26, Glasgow 2021) commits India to 500 GW non-fossil capacity by 2030 and net zero by 2070.
- Repowering means replacing old, low-capacity turbines with modern high-yield machines at the same site; NIWE pegs the potential at about 25.4 GW.
- SECI (Solar Energy Corporation of India) and tendering agencies run the auctions that price renewable power.
- Capacity factor — actual output as a share of rated capacity — is the key efficiency metric; modern turbines reach much higher factors than 2000s machines.
Mains Relevance
GS Paper 3
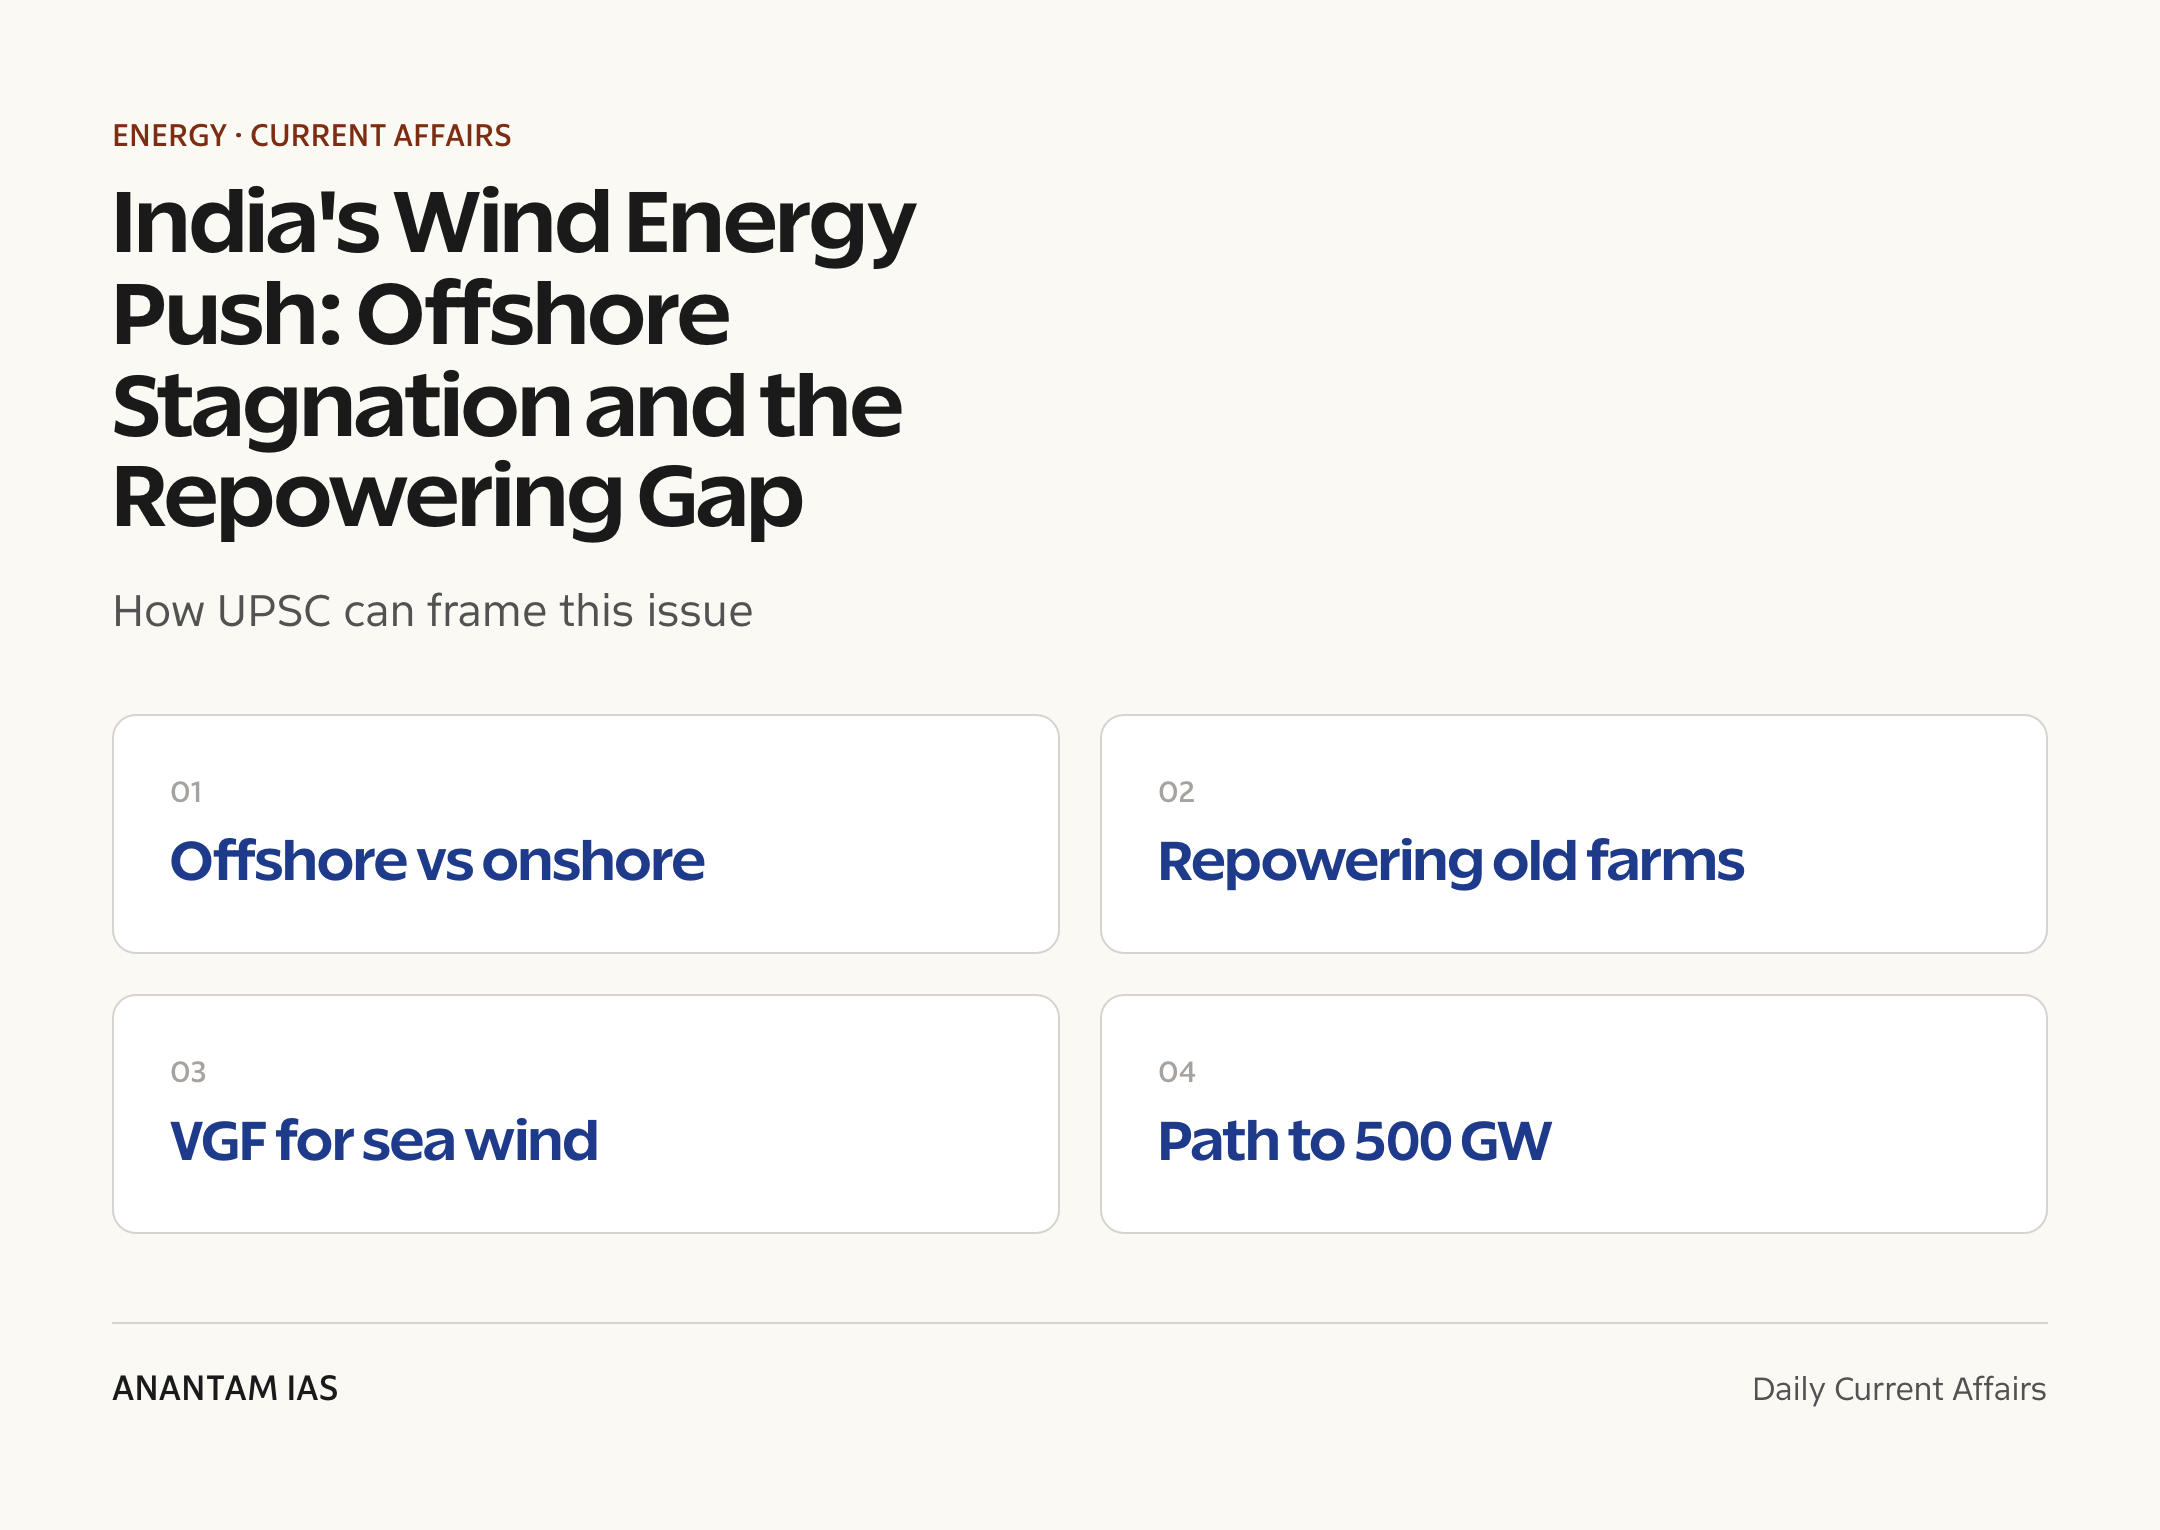
- Examine why India’s offshore wind has stalled despite a decade-old policy — costs, grid evacuation, seabed leasing, and VGF design — and assess corrective measures.
- Evaluate repowering of ageing wind farms as a low-land, high-yield route to the 500 GW non-fossil-by-2030 target, and the policy incentives needed to unlock it.
Essay
- Energy transition and the gap between targets and ground delivery.
- Doing more with less: efficiency, repowering, and the economics of clean energy.
Background and Context
Where India's wind sector stands
A large but lopsided fleet, strong on land and absent at sea.
- Cumulative wind capacity is about 50 GW (50.04 GW as of April 2025), placing India among the world’s top wind markets.
- The fleet is almost entirely onshore, with no operating offshore turbines.
- Gujarat ranks first in installed capacity, followed by Tamil Nadu; the western and southern windy belts dominate.
- Wind complements solar by generating more during the monsoon and at night, smoothing the renewable supply curve.
- After a mid-2010s slowdown tied to the shift from feed-in tariffs to reverse auctions, annual additions have recovered but remain below the pace needed for 2030.
Why offshore wind is stuck
Strong potential on paper, hard economics in the water.
- Offshore turbines stand in the sea, capturing steadier, stronger winds and higher capacity factors than onshore — but at far higher cost.
- Capital costs run well above onshore because of marine foundations, undersea cabling, specialised vessels, and harsh-environment maintenance.
- Grid evacuation from coastal blocks to demand centres needs new transmission, raising the all-in tariff.
- Seabed leasing and clearances were long unsettled; the Offshore Wind Energy Lease Rules were notified only in December 2023.
- To bridge the gap, the government approved ₹6,853 crore in VGF for the first 1,000 MW off Gujarat and Tamil Nadu, but build-out is years away.
- Development follows three frameworks set in the 2023 Strategy Paper — Model-A (government-funded with VGF and a fixed tariff), Model-B (developer-led without central support), and Model-C (developer-identified sites with bidding).
- Eight zones have been identified off each coast, but turbine sizes, water depths, and fishing-ground overlaps make site selection slow and contested.
The repowering challenge
The windiest land is often occupied by the weakest turbines.
- Repowering replaces ageing, low-capacity machines (many below 2 MW) with modern multi-MW turbines on the same windy sites.
- A single repowered site can sharply lift output — modern turbines reach capacity factors of 30-35% versus far lower for 2000s machines.
- NIWE assesses national repowering potential at about 25.4 GW, concentrated in sub-2 MW turbines.
- MNRE revised its 2016 repowering policy in December 2023 to ease replacement at high-resource sites.
- Uptake stays slow: older projects are often fully depreciated, fragmented across owners, and lack a clear financial incentive to scrap working assets.
- Scaling up repowering needs bigger turbines, stronger foundations, and grid upgrades at the same sites, plus fresh power-purchase agreements that older contracts did not anticipate.
- Done at scale, repowering can roughly double or triple energy yield from the very best windy land already secured for generation.
Policy framework and targets
A clear destination, contested by delivery hurdles.
- The National Offshore Wind Energy Policy 2015 set the legal frame, with MNRE as nodal ministry and NIWE as implementing agency.
- India targets 30 GW of offshore wind by 2030; identified potential is about 36 GW off Gujarat and 35 GW off Tamil Nadu.
- The Panchamrit commitments (COP26, 2021) anchor a 500 GW non-fossil target by 2030 and net zero by 2070.
- The updated National Electricity Plan envisages large wind additions alongside solar to approach the 2030 capacity goal.
- Auctions run by SECI and other agencies set tariffs that determine how fast new and repowered wind comes online.
Why it matters for the energy transition
Wind is the hedge that keeps a solar-heavy grid balanced.
- A grid leaning heavily on solar needs night and monsoon generation that wind supplies, reducing reliance on coal and storage.
- Closing the gap to 500 GW non-fossil is hard without faster wind growth, since solar alone cannot meet round-the-clock demand.
- Repowering delivers clean energy with little new land — a major advantage in a land-scarce, densely populated country.
- Offshore wind opens coastal demand centres to high, steady generation and can anchor future green hydrogen hubs near ports.
- Delays raise the risk of locking in fresh fossil capacity to cover demand growth, complicating the net-zero-2070 pathway.
- These commitments connect to India’s wider climate strategy outlined in our explainer on the India climate change policy and its 2070 net-zero goal.
Way Forward
Make offshore bankable
- Front-load transmission and port infrastructure so developers do not price in grid risk.
- Settle seabed leasing timelines and single-window clearances under the 2023 lease rules.
- Stage VGF-backed tenders predictably so the first 1,000 MW seeds a credible pipeline.
Unlock repowering incentives
- Offer clear tariff or accelerated-depreciation incentives so owners replace fully depreciated turbines.
- Ease land and PPA transfer rules to aggregate fragmented old sites for bankable repowering.
- Mandate grid access and evacuation upgrades at high-resource sites flagged by NIWE.
Strengthen the wind ecosystem
- Restore demand visibility through steady SECI auction calendars to revive domestic manufacturing.
- Invest in NIWE resource mapping, met-ocean data, and skilled marine-engineering capacity.
- Pair wind with storage and flexible coal to manage variability across the day.
Conclusion
India’s wind story is one of a strong start and a stalled second act. Crossing 50 GW onshore put the country among the global leaders, but a decade after the 2015 policy there is still no offshore turbine in Indian waters, and the windiest land carries ageing, low-yield machines that few owners have moved to replace.
Both gaps are fixable with predictable auctions, ready transmission, settled seabed rules, and real repowering incentives. Getting wind moving again — at sea and on the best onshore sites — is central to hitting 500 GW of non-fossil capacity by 2030 and staying on the net-zero-2070 path.
UPSC Practice Questions
Prelims MCQ 1
With reference to wind energy in India, consider the following statements:
- India’s installed wind capacity has crossed 50 GW, almost entirely onshore.
- Tamil Nadu has the highest installed wind capacity in the country.
- The National Institute of Wind Energy (NIWE) is the nodal agency for offshore wind resource assessment.
How many of the above statements are correct?
(a) Only one (b) Only two (c) All three (d) None
Answer: (b) Only two
Explanation:
Statements 1 and 3 are correct. Statement 2 is wrong: Gujarat, not Tamil Nadu, leads in installed wind capacity (Tamil Nadu is second). NIWE, Chennai, handles offshore resource assessment and block demarcation.
Prelims MCQ 2
The National Offshore Wind Energy Policy, which provides the framework for offshore wind development in India, was notified in:
(a) 2010 (b) 2015 (c) 2019 (d) 2022
Answer: (b) 2015
Explanation:
The National Offshore Wind Energy Policy was notified in 2015, with MNRE as the nodal ministry and NIWE as the implementing agency. Despite this, India still has no operating offshore wind capacity.
UPSC Mains Questions
- India has crossed 50 GW of wind capacity yet runs no offshore turbines and lags on repowering. Examine the structural reasons and suggest a roadmap to align wind growth with the 500 GW non-fossil-by-2030 target. (GS3, 250 words)
- “For a land-scarce country, repowering ageing wind farms may be the cheapest source of new clean energy.” Critically evaluate, with reference to India’s policy framework. (GS3, 150 words)
Source: The Hindu.
Frequently Asked Questions
How much wind capacity does India have, and how much is offshore?
India’s installed wind capacity is around 50 GW (about 50.04 GW as of April 2025), and it ranks among the world’s top wind markets. Almost all of it is onshore — India currently has no operating offshore wind turbines.
Which states lead India in wind energy?
Gujarat has the highest installed wind capacity, followed by Tamil Nadu. Together they account for roughly half of India’s wind fleet, and they also hold the bulk of the country’s identified offshore potential — around 36 GW off Gujarat and 35 GW off Tamil Nadu.
What is repowering, and why does it matter?
Repowering means replacing old, low-capacity wind turbines (often below 2 MW) with modern high-yield machines on the same windy site. It can sharply raise output without new land. NIWE pegs India’s repowering potential at about 25.4 GW, but uptake has been slow because old projects are fully depreciated and incentives are weak.
Why has offshore wind stalled in India despite a 2015 policy?
Offshore wind costs far more than onshore due to marine foundations, undersea cabling, special vessels, and harsh maintenance, plus the need for new grid evacuation. Seabed leasing rules were settled only in December 2023. The government has approved ₹6,853 crore in Viability Gap Funding for the first 1,000 MW off Gujarat and Tamil Nadu to bridge the cost gap.
What are India’s wind and non-fossil targets?
India targets 30 GW of offshore wind by 2030. Under the Panchamrit pledge (COP26, 2021), it aims for 500 GW of non-fossil capacity by 2030 and net zero by 2070, with wind as a key complement to solar.
Why is wind important when India is adding so much solar?
Wind generates more during the monsoon and at night, when solar output falls. A grid leaning heavily on solar needs wind to stay balanced round the clock, cutting reliance on coal and reducing storage costs — which is why slow wind growth threatens the 2030 and net-zero goals.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.