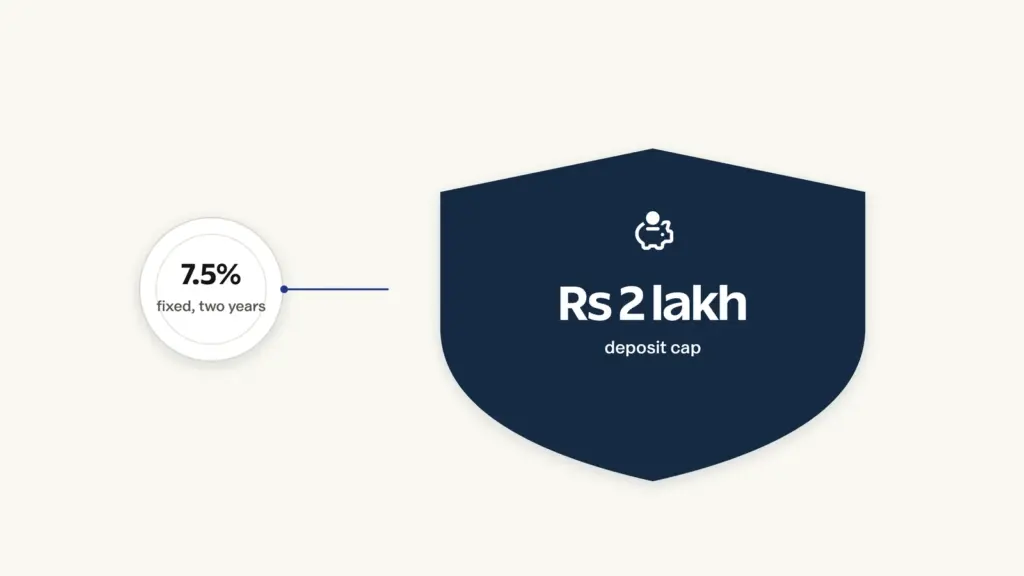
Start with the fact that matters most: the Mahila Samman Savings Certificate is closed to new deposits. The scheme notification allowed accounts to be opened only up to 31 March 2025, and that window has not been extended. If you already hold an account, nothing changes — it keeps earning 7.5% a year, compounded quarterly, until it matures two years from the date of deposit. If you are looking to open one now, you cannot, and the rest of this guide will point you at what is still open.
What MSSC was
The scheme was notified on 31 March 2023 by the Ministry of Finance, Department of Economic Affairs, under section 3A of the Government Savings Promotion Act, 1873, as the *Mahila Samman Savings Certificate, 2023* (G.S.R. 237(E)). It was announced as a two-year window for a two-year deposit, aimed squarely at women and girls who were outside the formal savings system.
| Feature | Rule |
|---|---|
| Who could open | A woman for herself, or a guardian on behalf of a minor girl |
| Account type | Single holder only |
| Opening window | Applications on or before 31 March 2025 — now closed |
| Minimum deposit | ₹1,000, and in multiples of ₹100 |
| Maximum deposit | ₹2,00,000 across all accounts of one holder |
| Further deposits | Not allowed in an account after the initial deposit |
| Multiple accounts | Allowed, with a gap of three months between one account and the next |
| Interest | 7.5% a year, compounded quarterly and credited to the account |
| Tenure | Two years from the date of deposit |
| Partial withdrawal | Up to 40% of the eligible balance, once, after one year |
| Where held | Post offices and authorised banks |
Because deposits could be made until 31 March 2025 and each deposit runs for exactly two years, the last MSSC accounts mature by 31 March 2027. The scheme has a natural end date built into it.
If you hold an account: the rules that still apply
Interest. Deposits bear 7.5% per annum, compounded quarterly and credited to the account. That rate is fixed by the scheme itself, not reset every quarter like most small savings instruments, so a rate revision elsewhere does not touch it. One catch worth knowing: if an account or a deposit was made in a way that did not conform to the scheme — say it pushed the holder past the ₹2 lakh ceiling — the interest on it is payable only at the Post Office Savings Account rate.
Maturity. The deposit matures on completion of two years from the date of deposit. You claim it by submitting Form-2 to the account office. Maturity value is rounded to the nearest rupee.
Partial withdrawal. You may withdraw up to 40% of the eligible balance, once, after one year from the date of opening and before maturity, using Form-3. Where the account is in a minor girl’s name, the guardian applies and certifies that the money is needed for the girl’s use and welfare and that she is alive on that date.
Premature closure. The account is not meant to be closed early. The exceptions are narrow:
- On the death of the account holder. Interest is paid at the scheme rate.
- On extreme compassionate grounds — medical support in a life-threatening disease of the account holder, or the death of the guardian — where the post office or bank is satisfied, after complete documentation, that continuing the account is causing undue hardship. Interest is again at the scheme rate.
- For any other reason, closure is allowed any time after six months from opening, on Form-4, but the balance then earns two percentage points less than the scheme rate — that is, 5.5%.
Tax treatment
This is where MSSC was routinely oversold. The deposit does not qualify for a deduction under section 80C, and the interest is taxable — added to the holder’s income and taxed at her slab rate.
What confused people is TDS. Interest from post office schemes falls under section 194A, but tax is deducted only above the prescribed threshold. On the scheme’s maximum ₹2 lakh deposit over two years, the interest earned stays below that threshold, so in practice no TDS is deducted. No TDS is not the same as no tax: the interest still has to be declared in the return.
What is still open instead
The obvious comparison is with the girl-child scheme that MSSC was often confused with.
| Feature | Mahila Samman Savings Certificate | Sukanya Samriddhi Account |
|---|---|---|
| Status for new accounts | Closed since 31 March 2025 | Open |
| Who it is for | Any woman, or a minor girl through a guardian | A girl child below 10 years, through a guardian |
| Interest rate | 7.5%, fixed by the scheme | 8.2% for the July–September 2026 quarter, reset quarterly |
| Tenure | 2 years | 21 years from opening, deposits for 15 years |
| Deposit limit | ₹2 lakh in total, one-time | ₹1.5 lakh a year |
| Section 80C deduction | No | Yes |
| Tax on interest | Taxable at slab rate | Exempt |
| Partial withdrawal | 40% once, after one year | 50% after the girl turns 18 or passes Class 10 |
| Best suited to | Parking a lump sum for two years | Long-horizon saving for a daughter |
Small savings rates were left unchanged for the July–September 2026 quarter, the ninth consecutive quarter without a revision, with Sukanya Samriddhi and the Senior Citizens’ scheme at 8.2%, NSC at 7.7%, KVP and the five-year deposit at 7.5% and PPF at 7.1%. The full guide to the Sukanya Samriddhi account explains its deposit and withdrawal rules in detail. If your goal is a guaranteed monthly income in old age rather than a lump sum, the Atal Pension Yojana works on a completely different design and is still open for enrolment. For a broader survey of what is currently available, see this list of government schemes.
Scheme rules and the current rate table for every national savings instrument are published by the National Savings Institute, and accounts are operated through India Post and authorised banks.
Frequently Asked Questions
Can I still open a Mahila Samman Savings Certificate account?
No. The scheme notification permitted applications only up to 31 March 2025, and the window has not been extended. Post offices and banks are not accepting new MSSC deposits.
My account is still running. Will it be closed early or the rate cut?
No. An account opened before the deadline runs its full two-year term at 7.5%, compounded quarterly. The rate is written into the scheme and does not move with quarterly small savings revisions.
When exactly does my account mature?
Two years from the date of deposit, not from the end of a financial year. An account opened in, say, October 2024 matures in October 2026. The last possible accounts, opened on 31 March 2025, mature by 31 March 2027.
How much can I withdraw before maturity?
Up to 40% of the eligible balance, once, after one year from opening and before maturity, on Form-3. Anything beyond that requires closing the account.
What happens if I close the account early?
On death of the holder, or on documented compassionate grounds such as a life-threatening illness or the death of the guardian, you get interest at the full scheme rate. For any other reason, closure is allowed after six months from opening, and interest drops to two percentage points below the scheme rate — 5.5%.
Is MSSC interest tax-free?
No. The interest is taxable at the holder’s slab rate and the deposit never qualified for a section 80C deduction. TDS is generally not deducted because the interest on the maximum permitted deposit stays under the threshold, but the income still has to be reported.
What should I do with the money when it matures?
That depends on the horizon. For a daughter under ten with a long runway, Sukanya Samriddhi pays more and is tax-exempt. For general savings with liquidity, a post office time deposit or a bank fixed deposit is the closest match to what MSSC did. Compare the current published rate, the lock-in and the tax treatment together, not the headline rate alone.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.