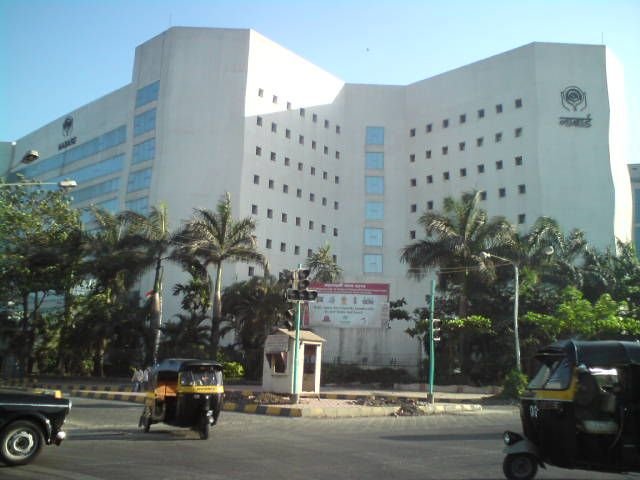
NABARD — the National Bank for Agriculture and Rural Development — is India’s apex development financial institution for the rural economy, the body that refinances every cooperative bank, regional rural bank and a sizeable share of commercial bank lending to the countryside. Established on 12 July 1982 on the recommendations of the Sivaraman Committee (1979), NABARD inherited the agricultural credit functions of the RBI and the refinancing function of the erstwhile Agricultural Refinance and Development Corporation. As of FY25 its balance sheet exceeds ₹9 lakh crore, making NABARD one of the largest development banks in Asia. For UPSC GS-III, NABARD is the indispensable companion topic to rural credit, priority-sector lending and financial inclusion, paired with regulators like SEBI and IRDAI in the broader DFI architecture.
Origins of NABARD
The genesis of NABARD lies in the Committee to Review Arrangements for Institutional Credit for Agriculture and Rural Development (CRAFICARD), set up by the RBI in March 1979 under the chairmanship of B. Sivaraman, a former Cabinet Secretary. The Sivaraman Committee submitted its interim report in November 1979 and recommended a single apex institution to provide undivided attention to rural credit — an integrated body that would combine the RBI’s Agricultural Credit Department, the Rural Planning and Credit Cell, and the Agricultural Refinance and Development Corporation (ARDC).
Parliament enacted the National Bank for Agriculture and Rural Development Act, 1981, and NABARD began operations on 12 July 1982 with an initial paid-up capital of ₹100 crore, jointly contributed by the Government of India and the RBI. Successive amendments raised the authorised capital, and in 2017 the Government of India bought out the RBI’s residual shareholding, making NABARD a wholly Government of India-owned development financial institution. The authorised capital today stands at ₹30,000 crore.
Mandate and Functions
NABARD’s statutory mandate, set out in the NABARD Act, is sweeping — promoting integrated rural development by providing credit for agriculture, small-scale industries, cottage and village industries, handicrafts and other allied economic activities in rural areas.
In practice, NABARD’s functions are grouped into three broad heads.
Credit Functions
- Refinance to State Cooperative Banks (SCBs), Regional Rural Banks (RRBs), commercial banks, and State Cooperative Agriculture and Rural Development Banks (SCARDBs) for short-term and long-term agricultural credit.
- Direct lending to state governments under the Rural Infrastructure Development Fund and to producer companies and federations.
- Co-financing with commercial banks for high-value rural infrastructure and agribusiness projects.
Developmental Functions
- SHG-Bank Linkage Programme, launched in 1992 — the single largest microfinance programme in the world.
- Watershed development, tribal development, and farmer producer organisation (FPO) promotion through dedicated funds.
- Kisan Credit Card (KCC) support and training of cooperative bank staff through the Bankers Institute of Rural Development (BIRD), Lucknow.
Supervisory Functions
- On-site inspection of State and District Central Cooperative Banks and RRBs under Section 35 of the Banking Regulation Act, 1949 (delegated by the RBI).
- Off-site surveillance of cooperative banks through CAMELS-style supervisory frameworks.
- Resolution and turnaround support to weak cooperative banks.
NABARD is therefore a hybrid — part bank, part development agency, part supervisor. This three-in-one design was the deliberate intent of the Sivaraman Committee.
The Rural Infrastructure Development Fund
The Rural Infrastructure Development Fund (RIDF) is the flagship NABARD-administered fund, set up in 1995-96 from the shortfall by commercial banks in meeting their priority-sector targets. Commercial banks that fall short of their agriculture or weaker-section sub-targets deposit the shortfall with NABARD at concessional rates. NABARD on-lends these resources to state governments at slightly higher rates to finance rural infrastructure — roads, bridges, irrigation, drinking water, soil conservation, primary schools, primary health centres and rural haats.
Since inception, RIDF has cumulatively sanctioned more than ₹5 lakh crore in tranches I through XXX (FY25), funding over 8 lakh projects across 35 states and union territories. RIDF XXX in the Union Budget 2025-26 received an allocation of ₹40,000 crore. The fund is structured so that recoveries from state governments rotate back into fresh sanctions, making it a quasi-revolving facility. Sister funds modelled on RIDF — the Long Term Irrigation Fund, Micro Irrigation Fund, Dairy Processing and Infrastructure Development Fund, Warehouse Infrastructure Fund and NABARD Infrastructure Development Assistance — extend the same architecture into specific sub-sectors.
Refinance to the Cooperative and RRB Architecture
NABARD’s refinance is the lifeline of the cooperative credit structure and the RRB system. The flows broadly take three shapes.
Short-Term Refinance
For seasonal agricultural operations (SAO) — the financing of cropping cycles — NABARD provides short-term refinance to SCBs which in turn fund DCCBs and PACS, and to RRBs directly. Short-term refinance is priced at concessional rates linked to the RBI’s repo rate and the government’s interest subvention scheme that holds farmer borrowing at an effective 4 per cent for prompt repayers. The mechanics of how the repo rate and the cash reserve ratio interact with NABARD’s cost of funds is central to rural-credit transmission and is debated at every monetary policy committee meeting.
Long-Term Refinance
For investment credit — farm mechanisation, plantation, dairy, fisheries, allied activities, rural housing and non-farm rural enterprises — NABARD extends long-term refinance to commercial banks, RRBs and SCARDBs with tenors of 3 to 15 years.
Conversion and Rephasement
In years of widespread crop failure or natural calamity declared by the state, NABARD permits the conversion of short-term production loans into medium-term loans, easing repayment pressure on affected farmers. This counter-cyclical facility is a structural cushion in the rural credit system.
The SHG-Bank Linkage Programme
The single most consequential developmental intervention by NABARD is the Self-Help Group (SHG) Bank Linkage Programme, launched in 1992 as a pilot connecting 500 SHGs to formal banks. As of FY25 the programme had over 14 lakh SHGs with savings-linked accounts, savings deposits exceeding ₹70,000 crore, and credit-linked cumulative disbursement crossing ₹15 lakh crore. The programme has been recognised by the World Bank and others as the world’s largest microfinance initiative, mobilising overwhelmingly women members — over 80 per cent of linked SHGs are women’s groups. The model fuses social mobilisation with formal credit, and is closely intertwined with state-level missions such as Kerala’s Kudumbashree and the National Rural Livelihoods Mission.
Funding Sources of NABARD
NABARD funds its operations through a mix that has shifted markedly over time:
- Equity capital — fully held by the Government of India after 2017.
- Bonds and debentures — including tax-free bonds in earlier years, and capital-gains-eligible bonds at present.
- Borrowings from the RBI — historically the General Line of Credit; reduced sharply in recent years.
- Deposits from commercial banks — RIDF and similar funds.
- External assistance — concessional lines from the World Bank, ADB, KfW, JICA for specific projects.
The shift away from RBI lines has pushed up NABARD’s cost of funds and tightened its refinance spreads, a structural pressure that recurs in every Annual Report.
Recent Challenges and Reforms
NABARD’s recent challenges are layered. The cost of funds has risen as cheap RBI lines have shrunk. The rise of fintech and microfinance institutions has compressed the traditional refinance space at the lower end. The transition of cooperative banks to Core Banking Solutions remains uneven and several DCCBs are under PCA-equivalent restrictions. Climate adaptation and natural-farming finance are emerging priorities for which dedicated facilities are still being designed. Recent reforms include the NABARD Climate Action Plan (2023), the launch of the JLG Bhuvan portal for digital monitoring of joint liability groups, and an expansion of the AgriClinic-AgriBusiness scheme to support agri-entrepreneurs. The interplay of NABARD funding with the Centre’s fiscal deficit is increasingly relevant, since RIDF interest payments are now a measurable line item in state budgets.
Frequently Asked Questions
When was NABARD established?
NABARD was established on 12 July 1982 under the NABARD Act, 1981, on the recommendations of the Sivaraman Committee (CRAFICARD) of 1979. It is headquartered in Mumbai.
Who owns NABARD today?
Since 2017, NABARD is wholly owned by the Government of India. The RBI’s residual shareholding was bought out by the Centre that year. The authorised capital stands at ₹30,000 crore.
What is the Rural Infrastructure Development Fund?
RIDF is a NABARD-administered fund created in 1995-96, capitalised by the shortfalls of commercial banks in meeting their priority-sector targets. It on-lends to state governments for rural roads, irrigation, drinking water, and other social infrastructure.
What is the SHG-Bank Linkage Programme?
A NABARD-pioneered programme launched in 1992 to link Self-Help Groups — primarily of women — to formal banks for savings, credit and other services. It is the world’s largest microfinance programme.
What is NABARD’s role in cooperative banks?
NABARD refinances State Cooperative Banks and District Central Cooperative Banks for short-term and long-term agricultural credit, supervises them under powers delegated by the RBI, and provides developmental support including digitisation and HR.
Does NABARD lend directly to farmers?
No, NABARD does not lend directly to individual farmers in most cases. It refinances the lending done by banks and cooperatives. Direct lending is largely to state governments, producer companies, and large agribusiness projects.
What is NABARD’s relationship with the RBI?
NABARD took over the agricultural credit functions of the RBI in 1982. The RBI continues to delegate inspection of cooperative banks and RRBs to NABARD. The RBI no longer holds equity since 2017.
What are NABARD’s current challenges?
Rising cost of funds after the contraction of RBI lines, competition from fintechs in the microfinance space, the uneven CBS adoption of cooperative banks, and the new mandate of financing climate adaptation in agriculture.
Tell Google you want more of this.
Add Anantam IAS as a preferred sourceOne tap, and this site shows up more often in your own Top Stories, AI Overviews and AI Mode. Remove it any time.